Clients, friends, and colleagues:
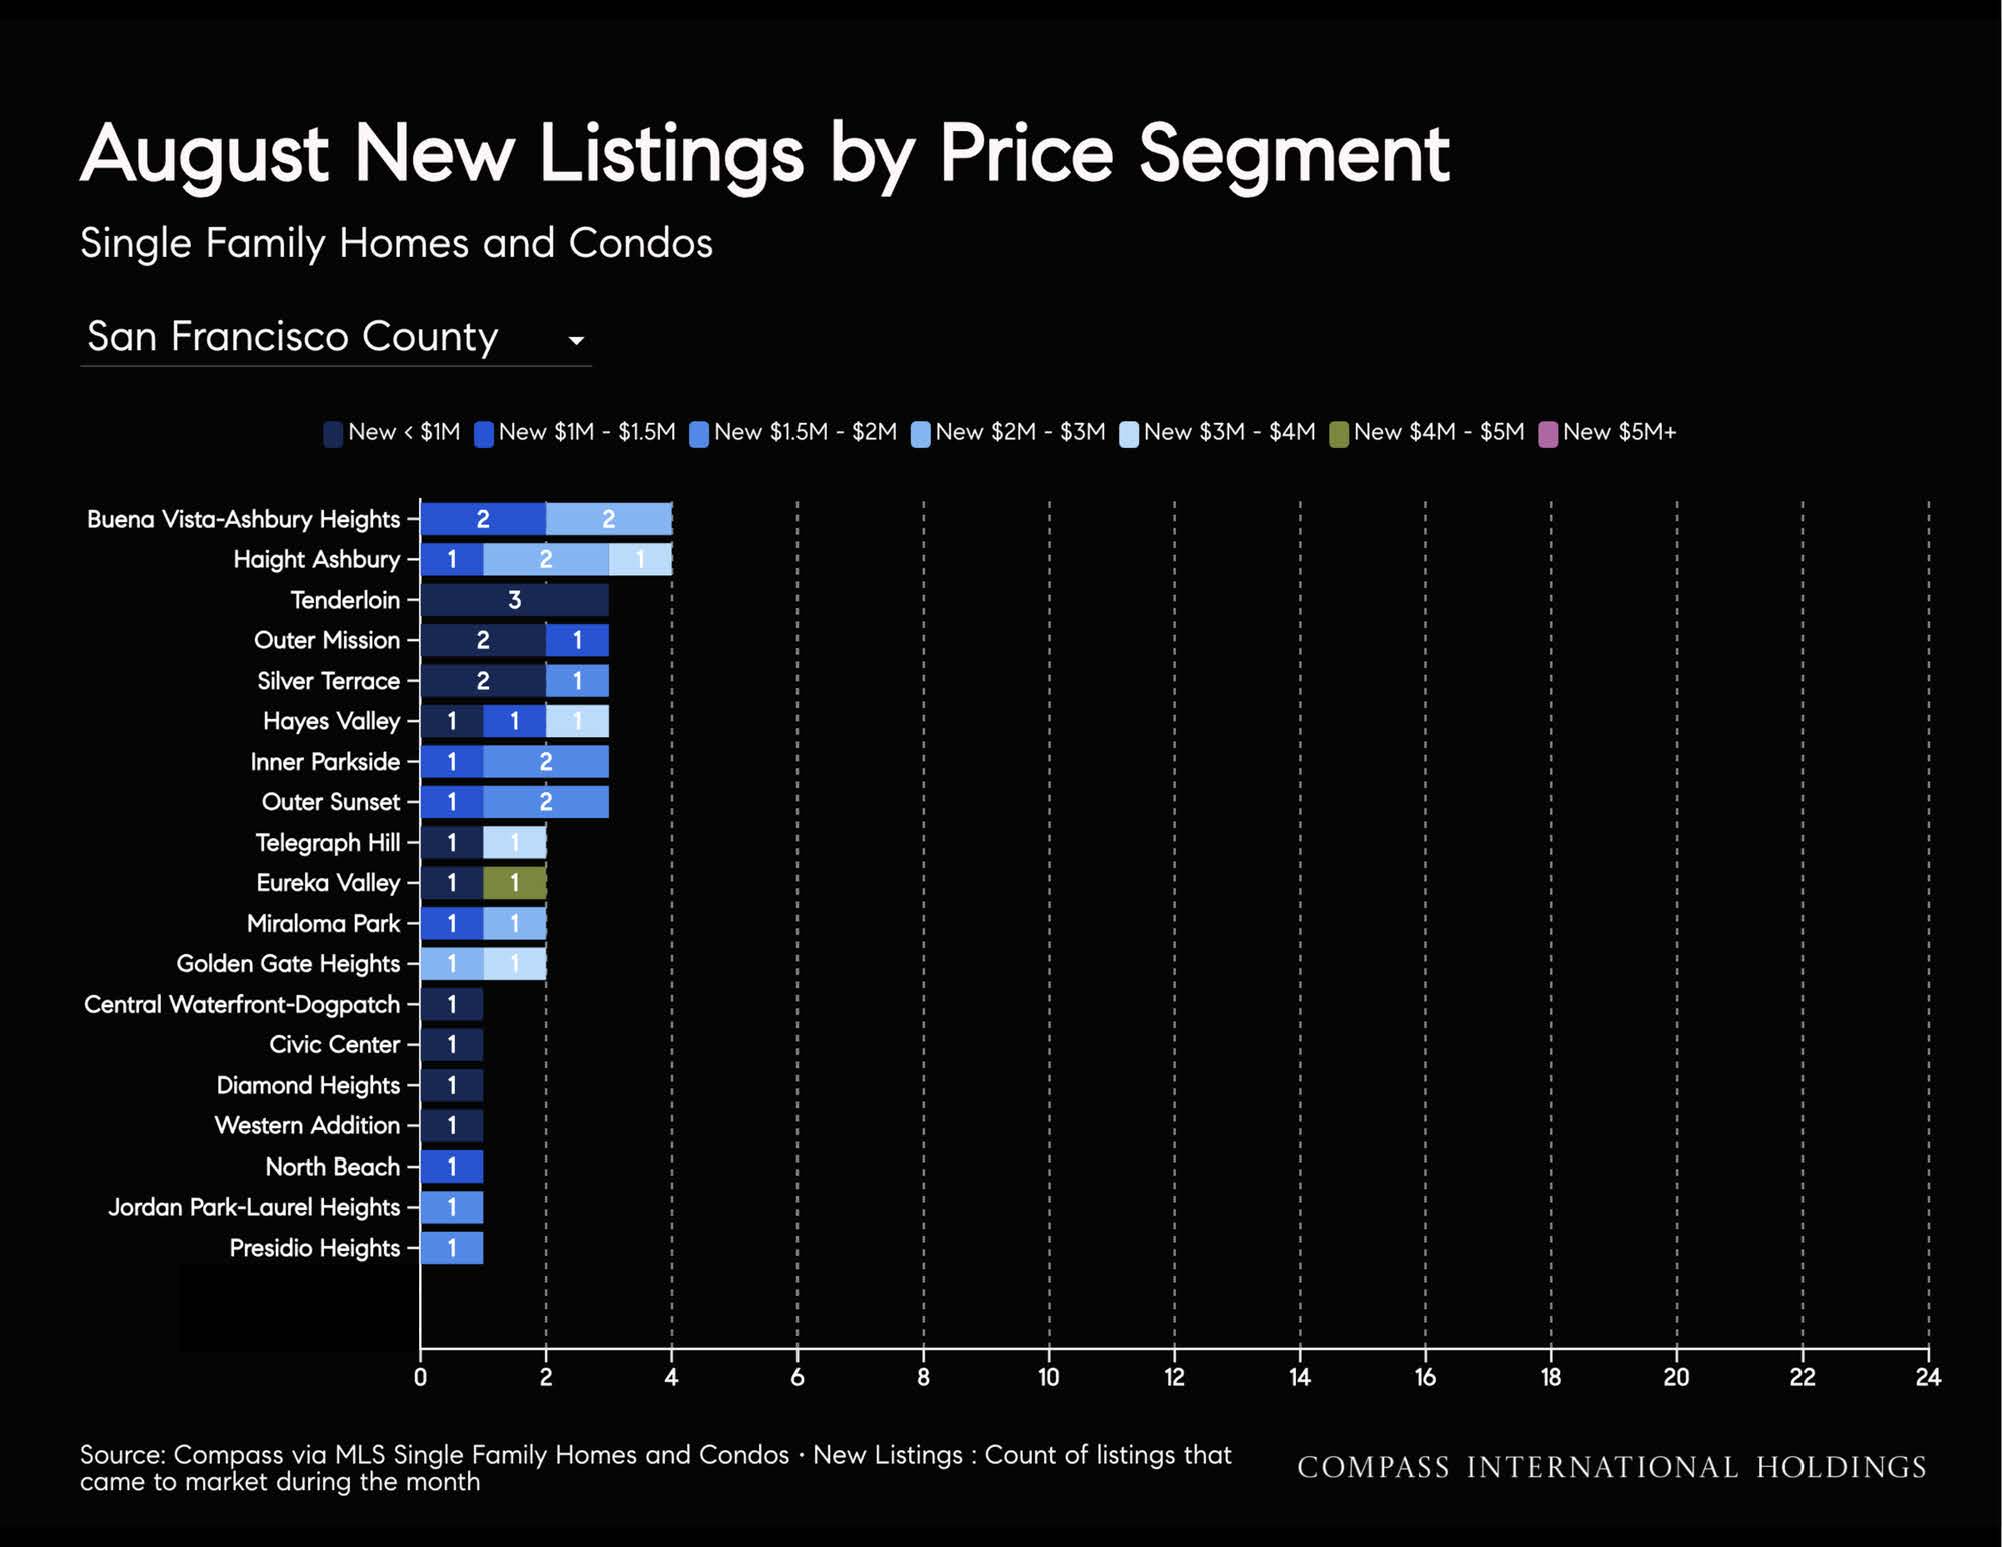
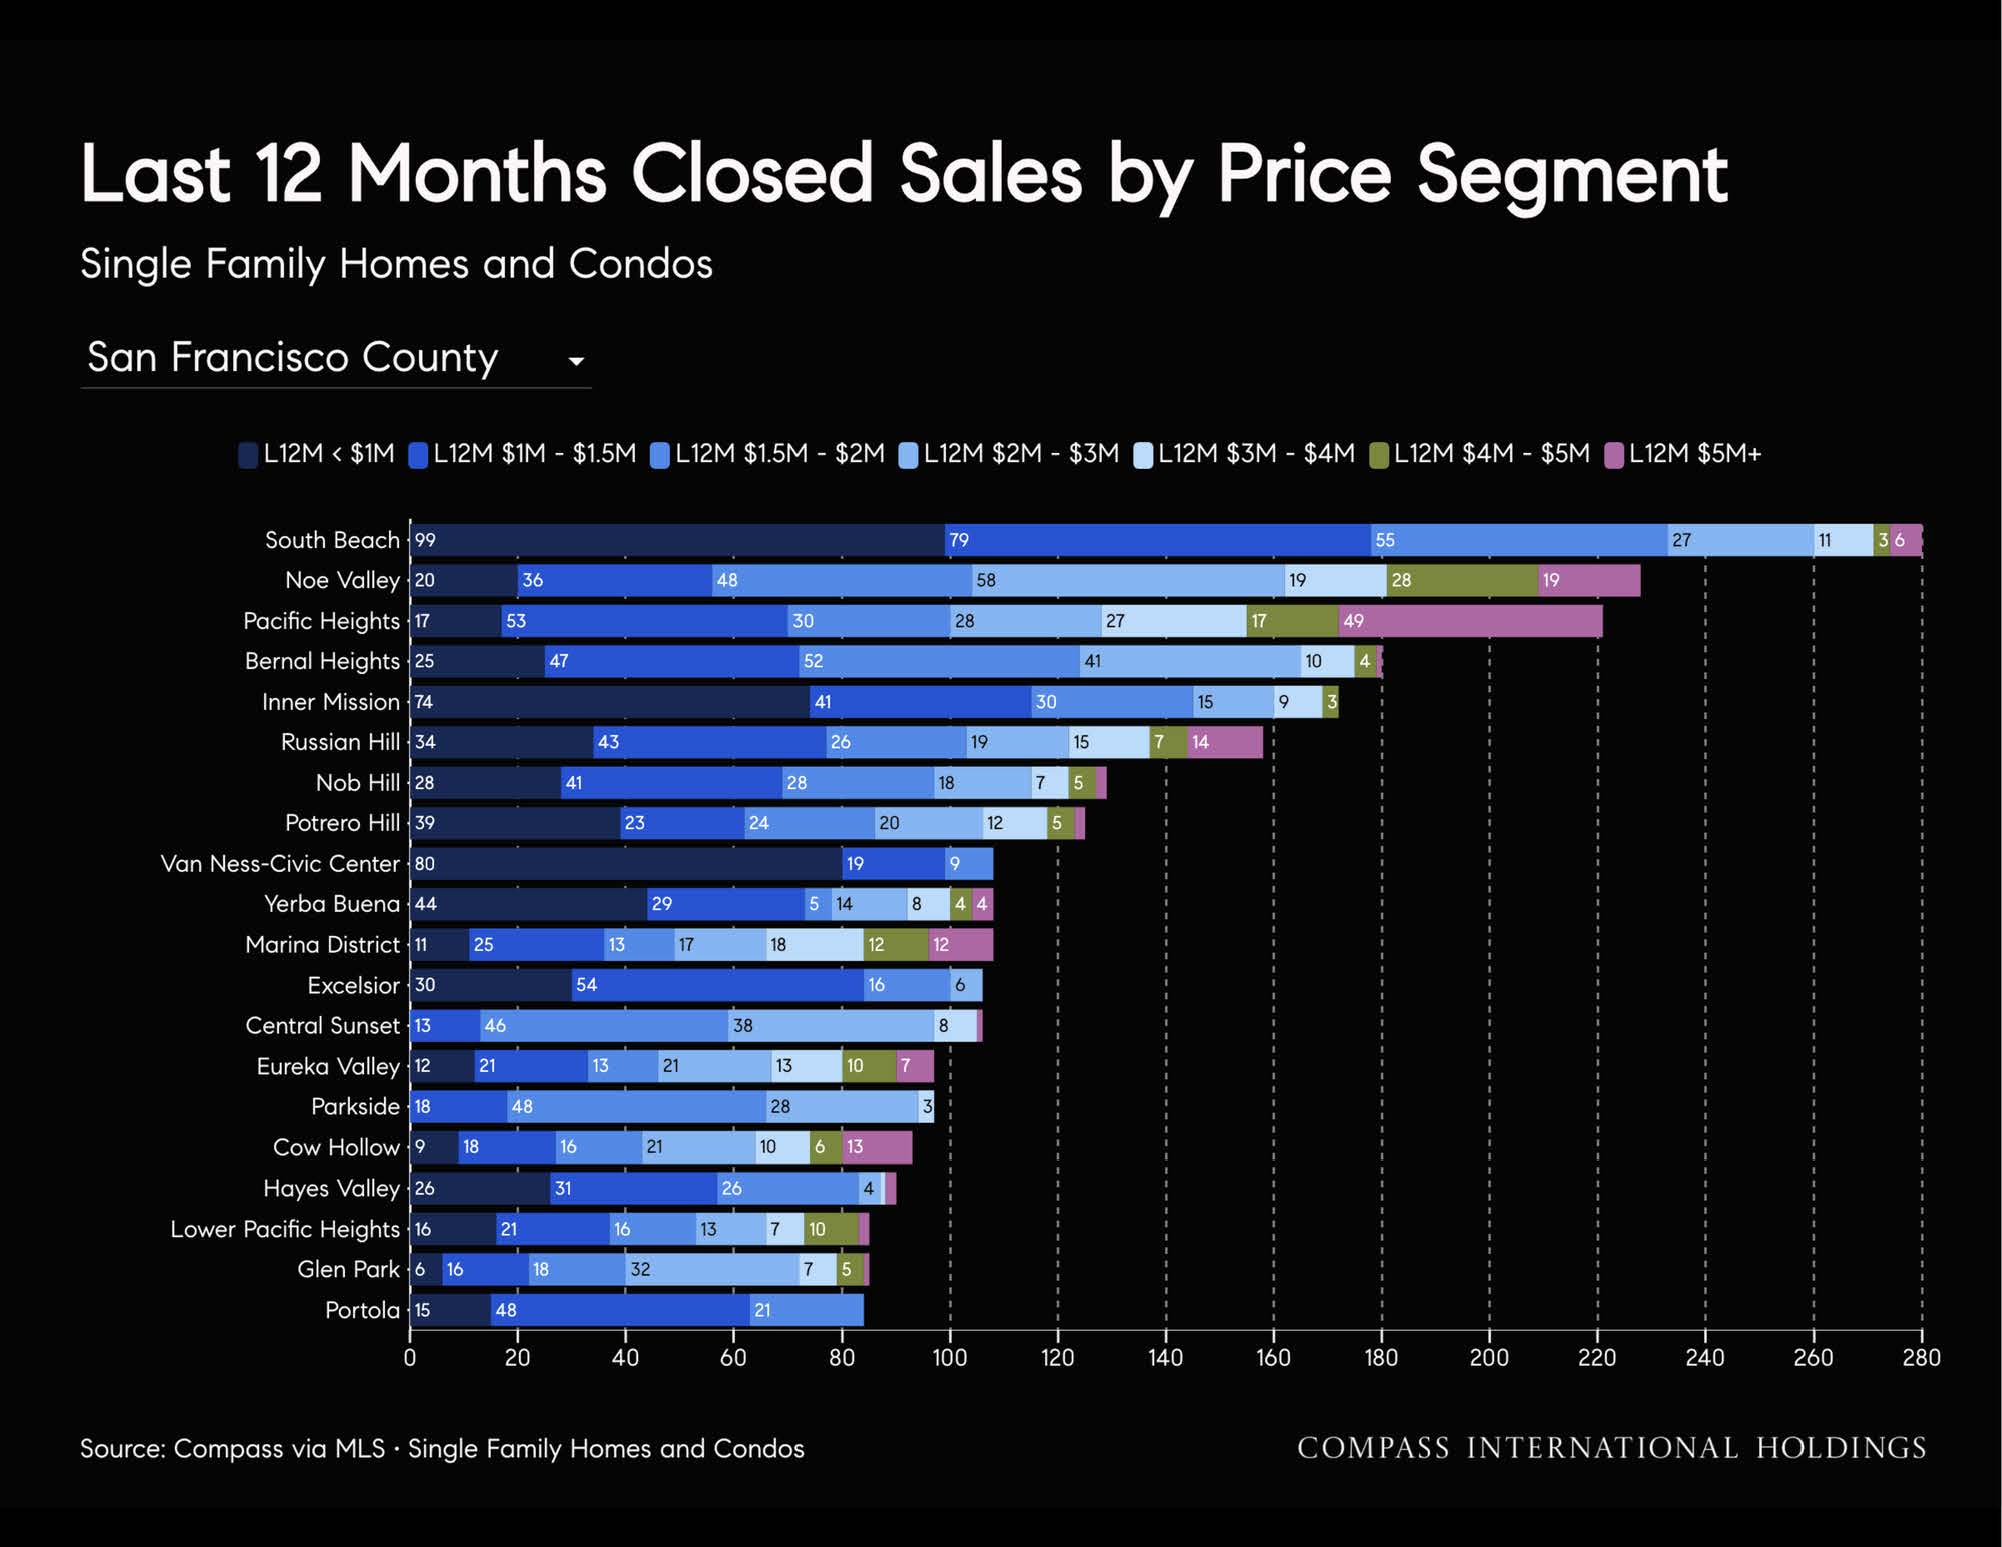
Some quick cliff notes on the current state of our market here in San Francisco:
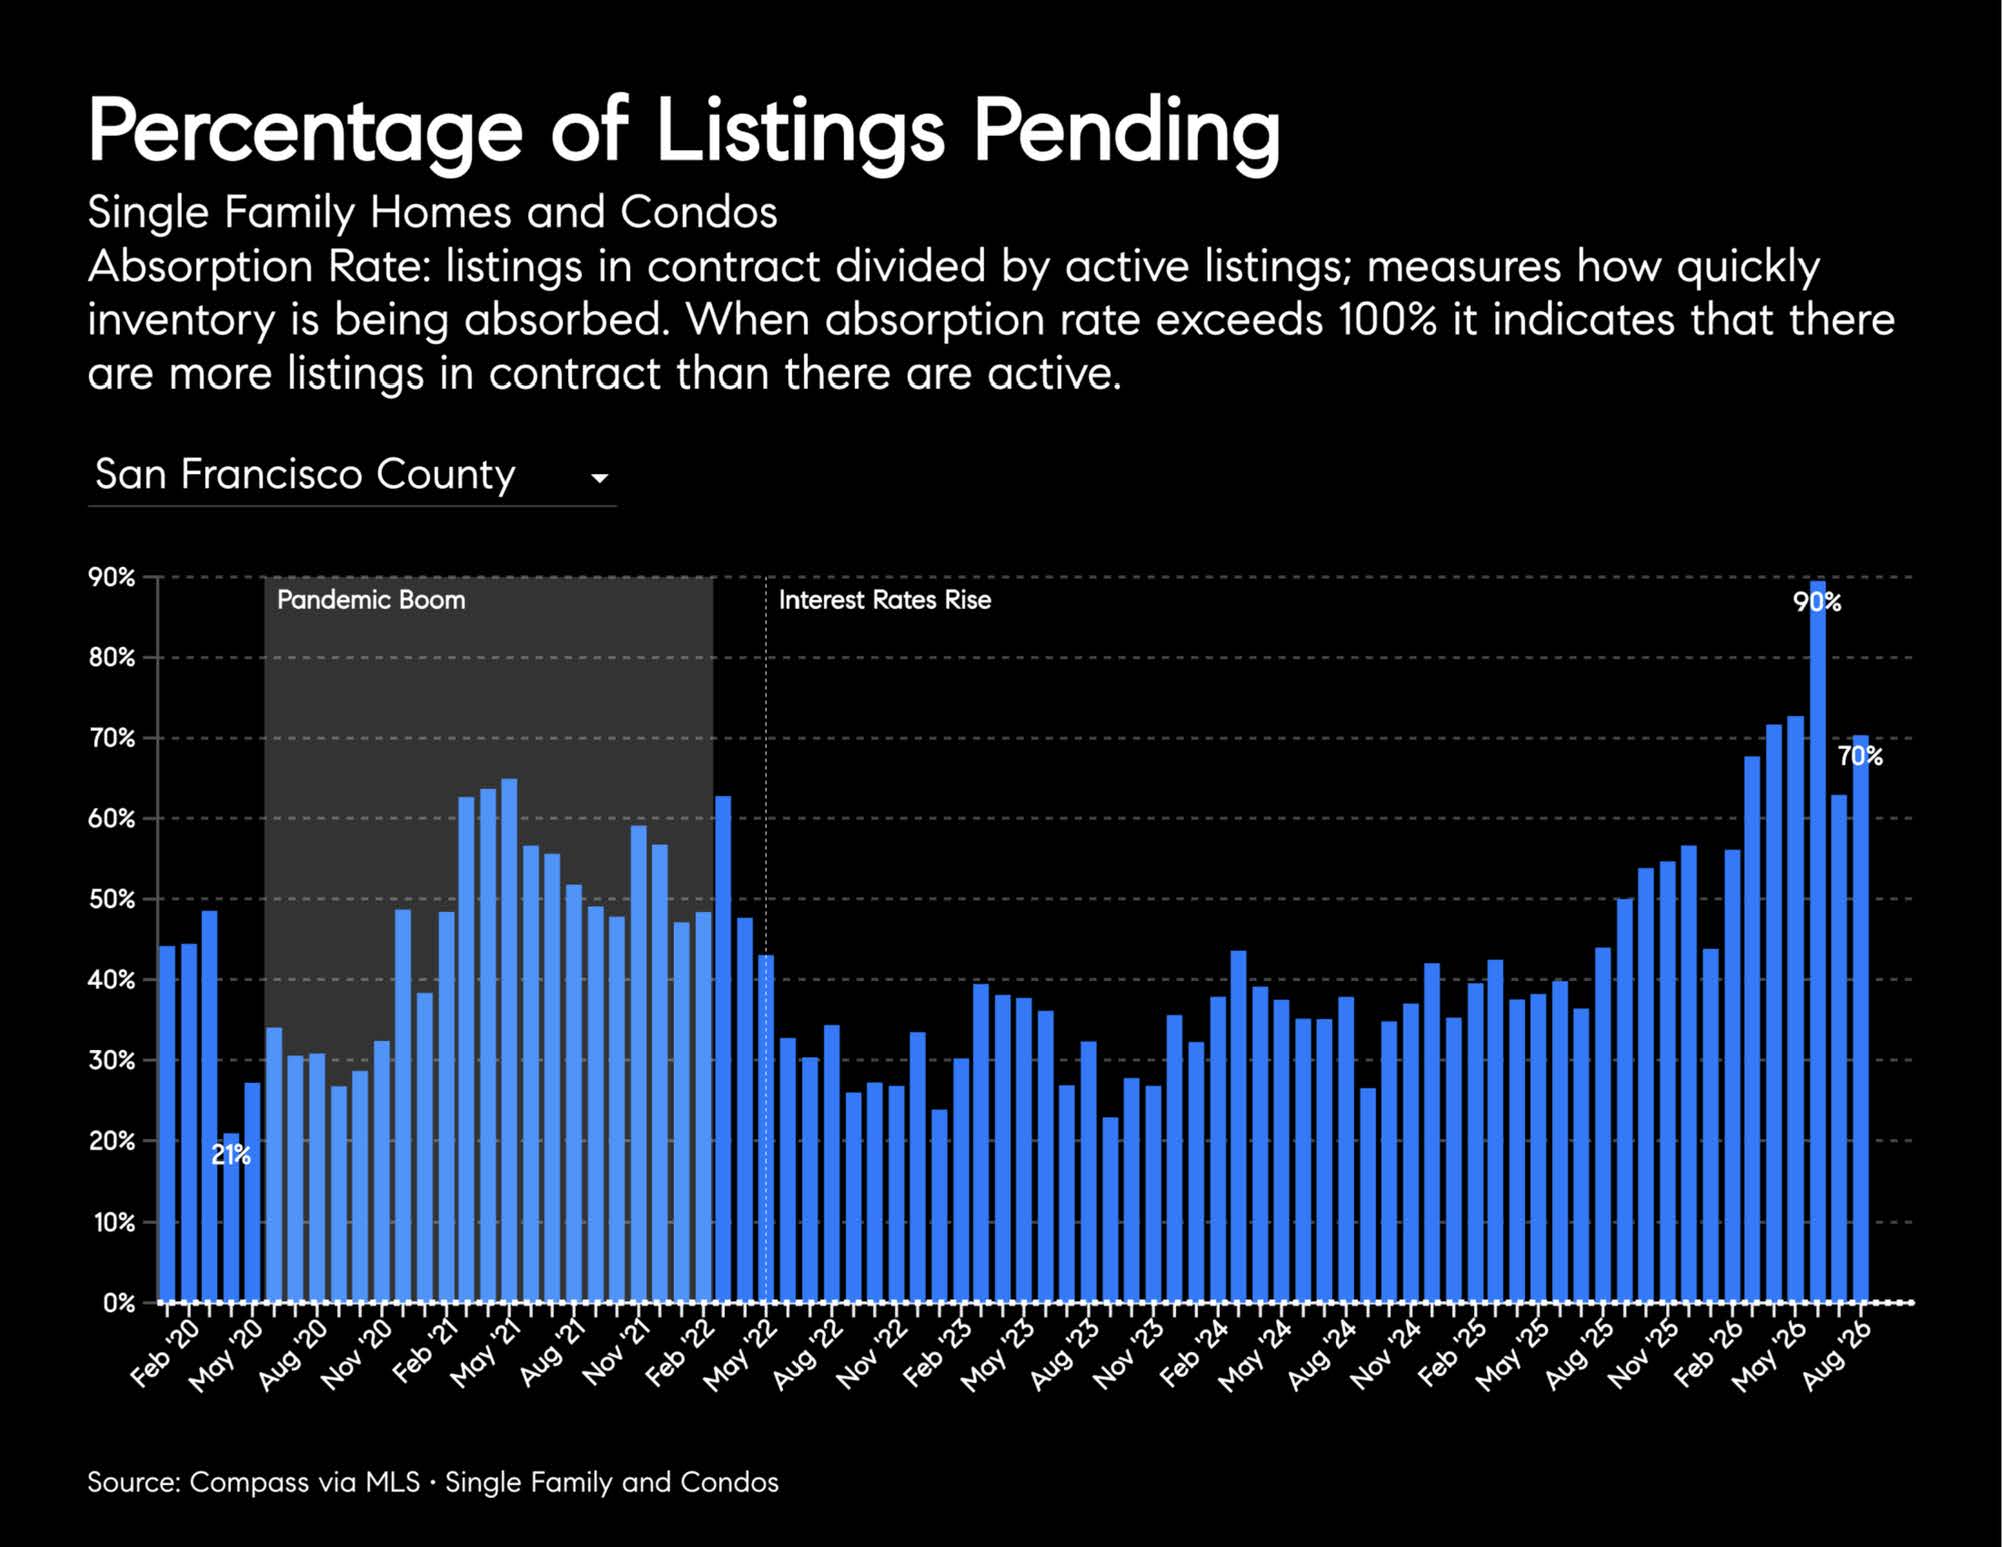
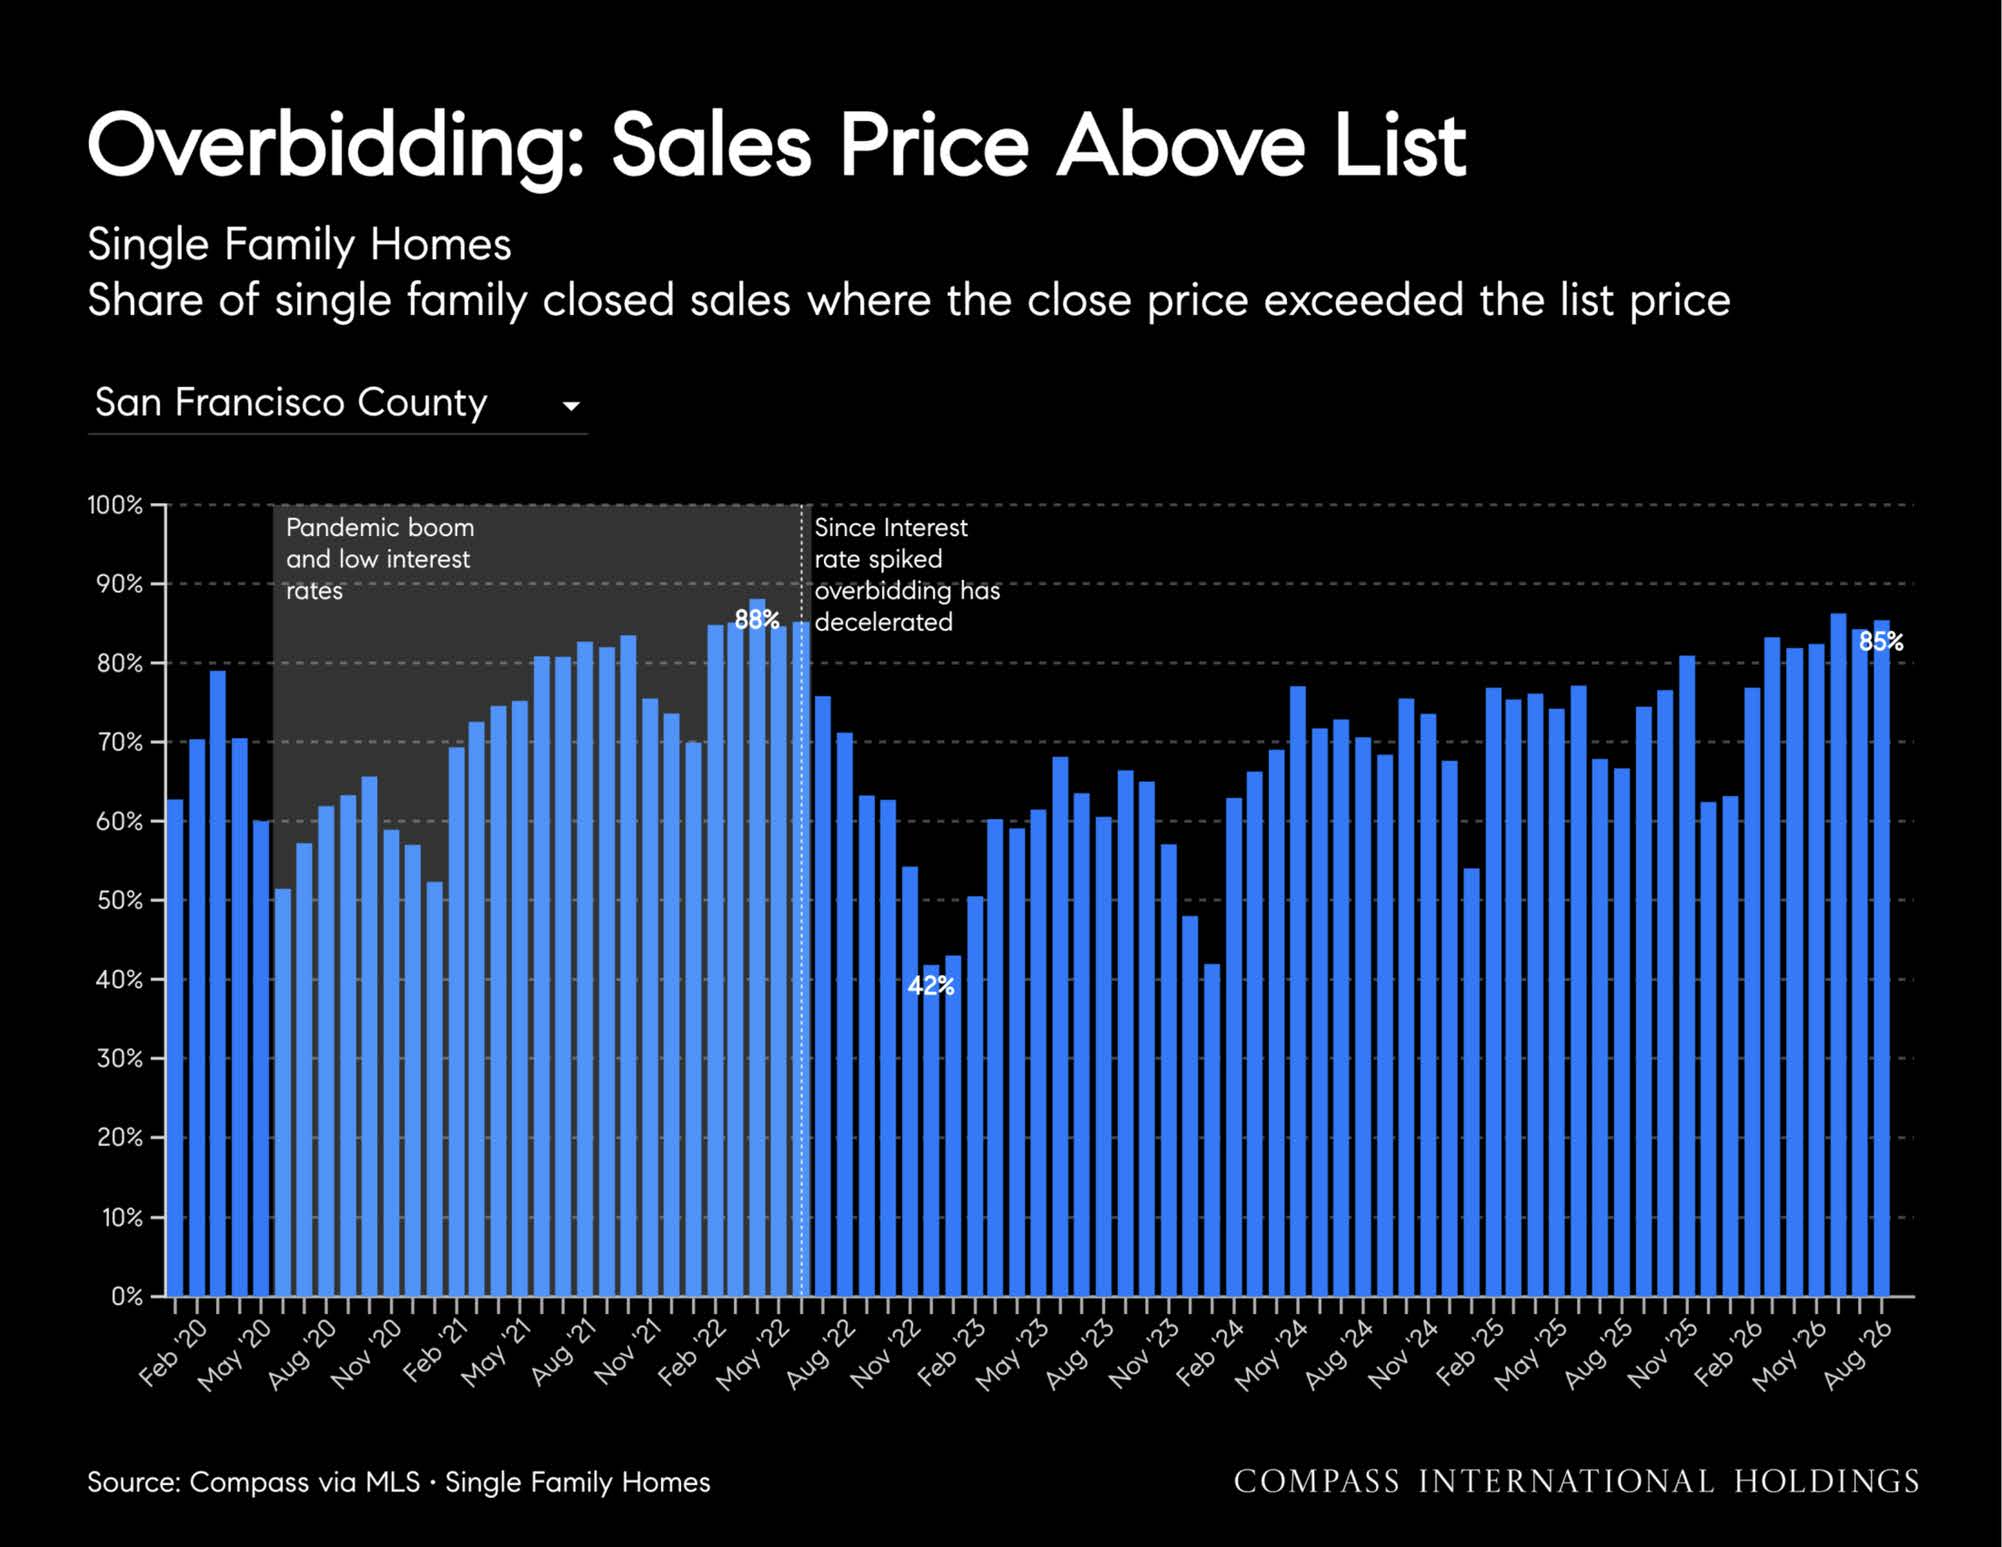
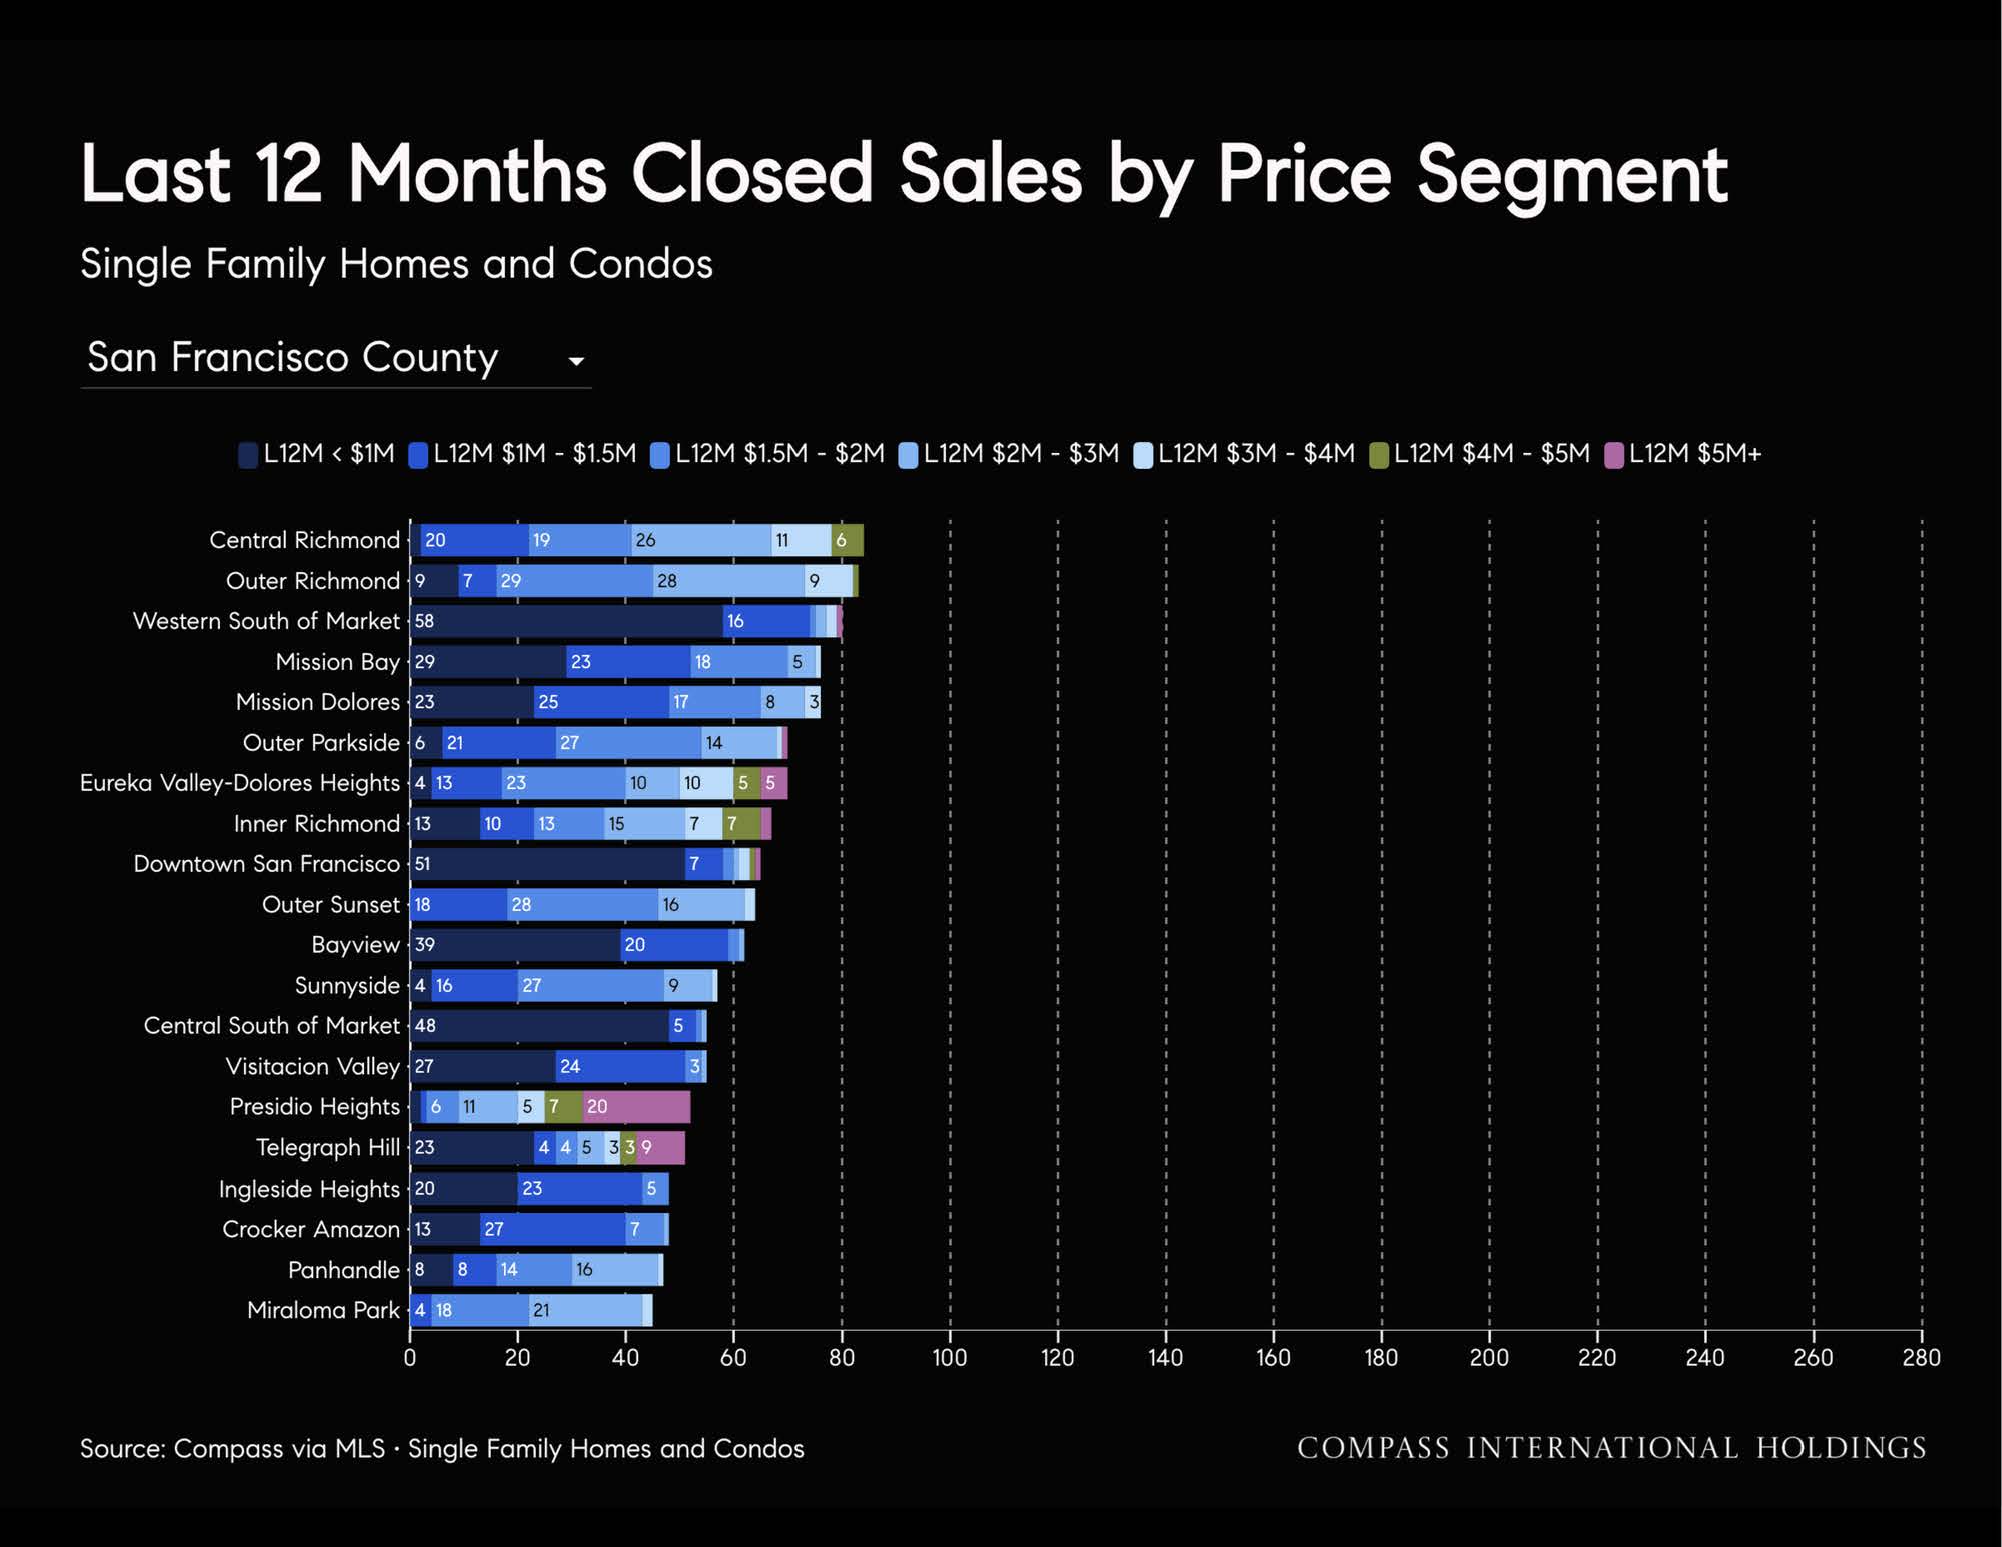
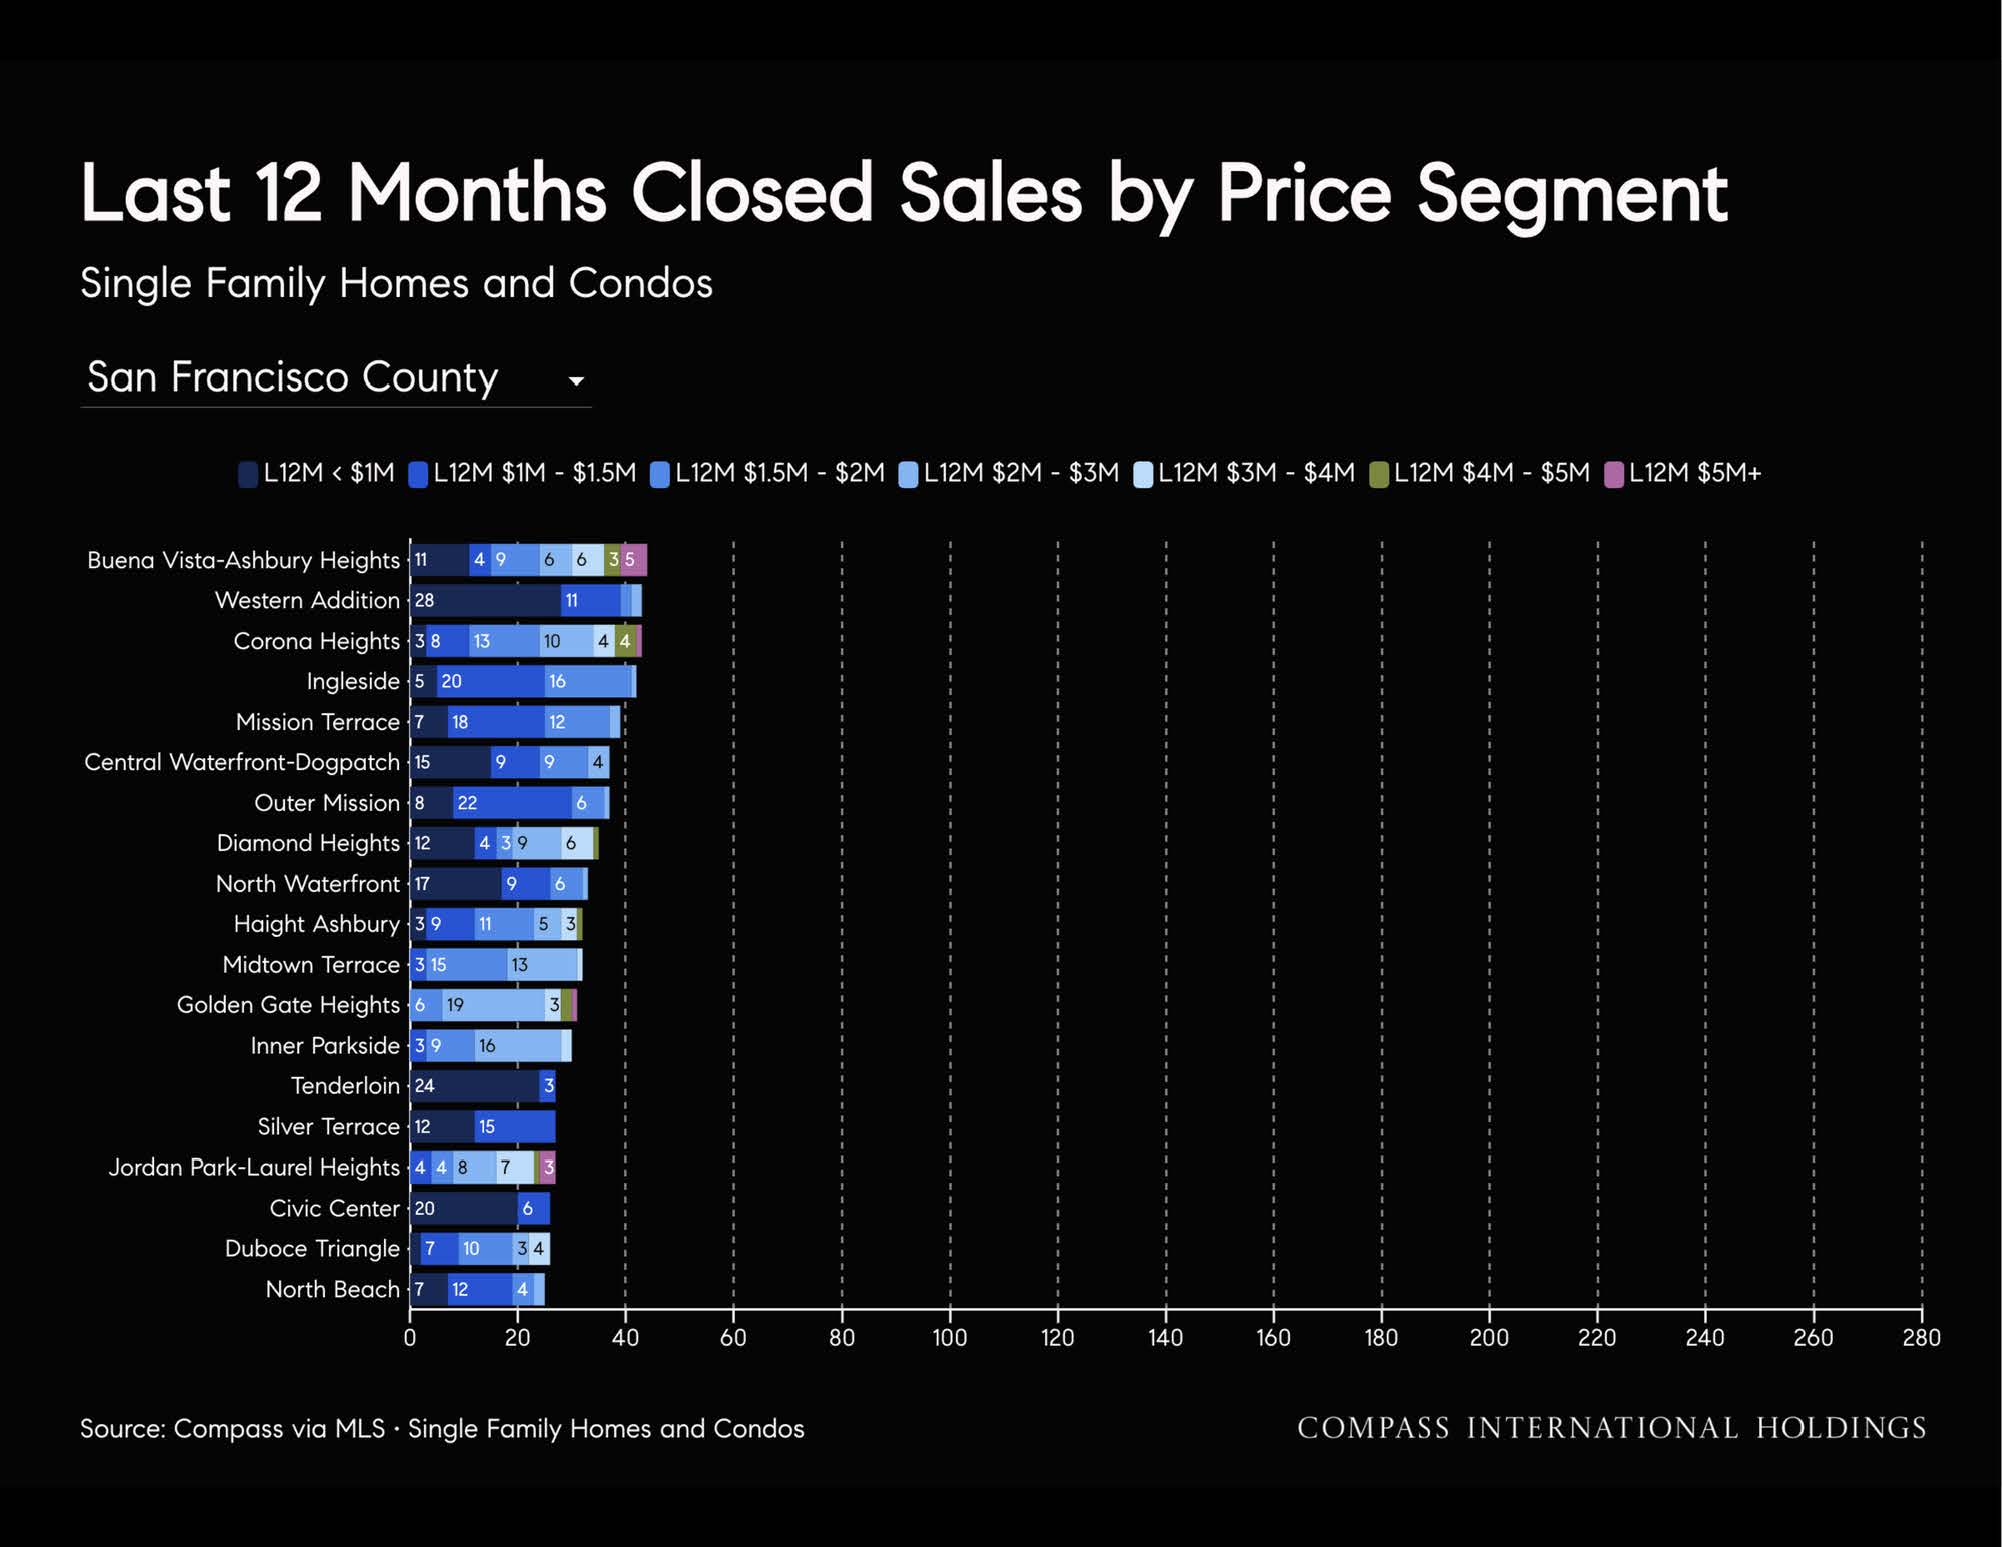
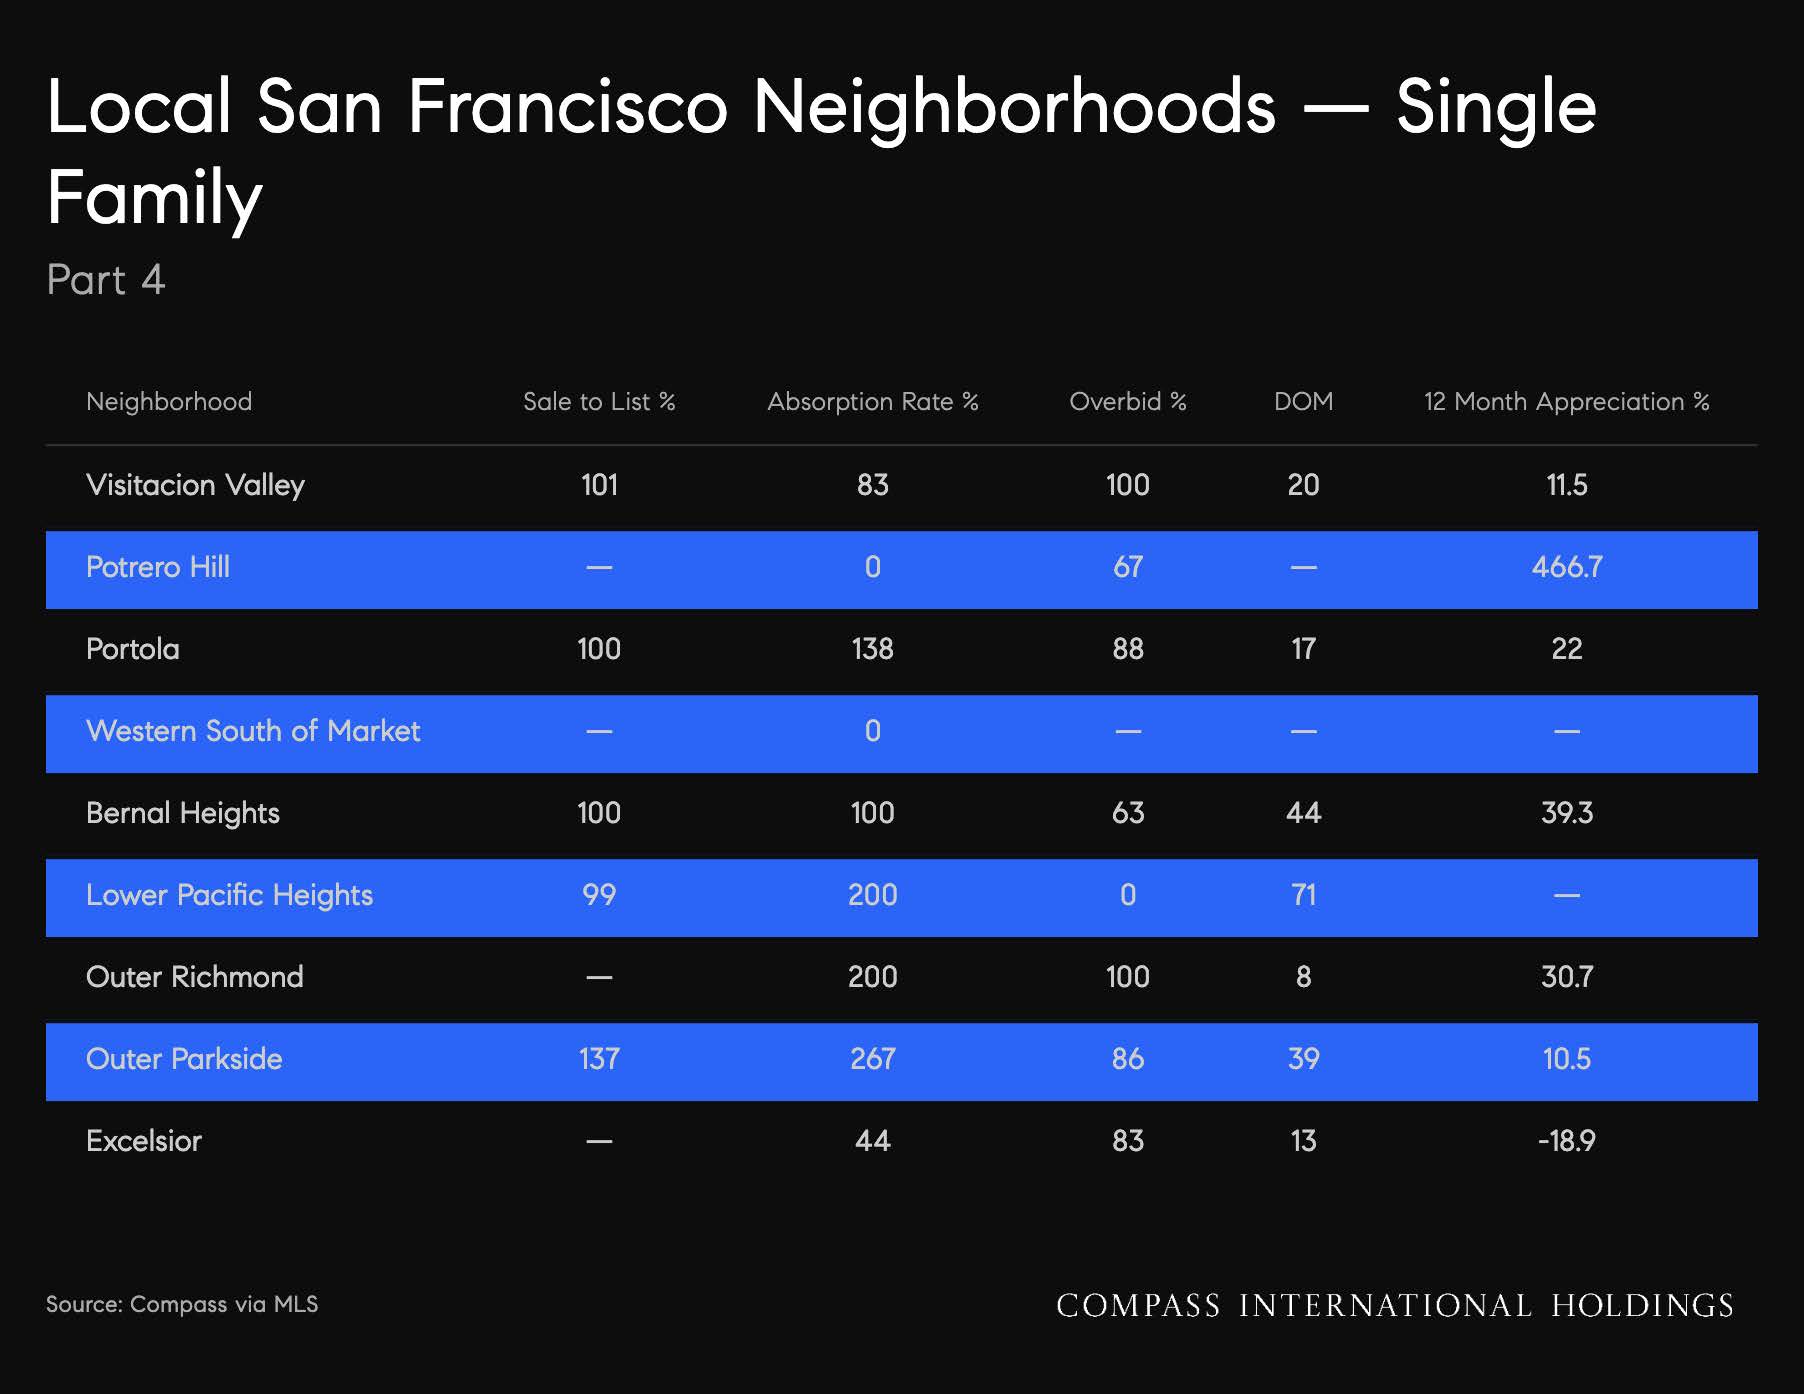
1) Buyer demand remains exceptionally strong in the hottest sectors of the market, particularly single-family homes and desirable boutique condos. Through September 14, 205 San Francisco properties had closed for at least $1 million over asking, including 162 single-family homes. That means roughly one in ten house sales this year has closed $1 million or more above its asking price. For perspective, the previous high over the past decade was just 40 such sales in 2022.
2) San Francisco rents are up 25%+, adding further pressure to the purchase market.
3) At the same time, some new headwinds are emerging, including challenges in AI and rising interest rates.
Interest rates have risen to their highest level in more than 14 months, with the 30-year fixed hovering around 7%. The Fed unanimously raised rates by 0.25% one week ago and has projected additional rate hikes in 2026.
While that is difficult news for most housing markets across the country, San Francisco’s supply-and-demand dynamics remain very much in favor of sellers, particularly in the strongest segments of the market.
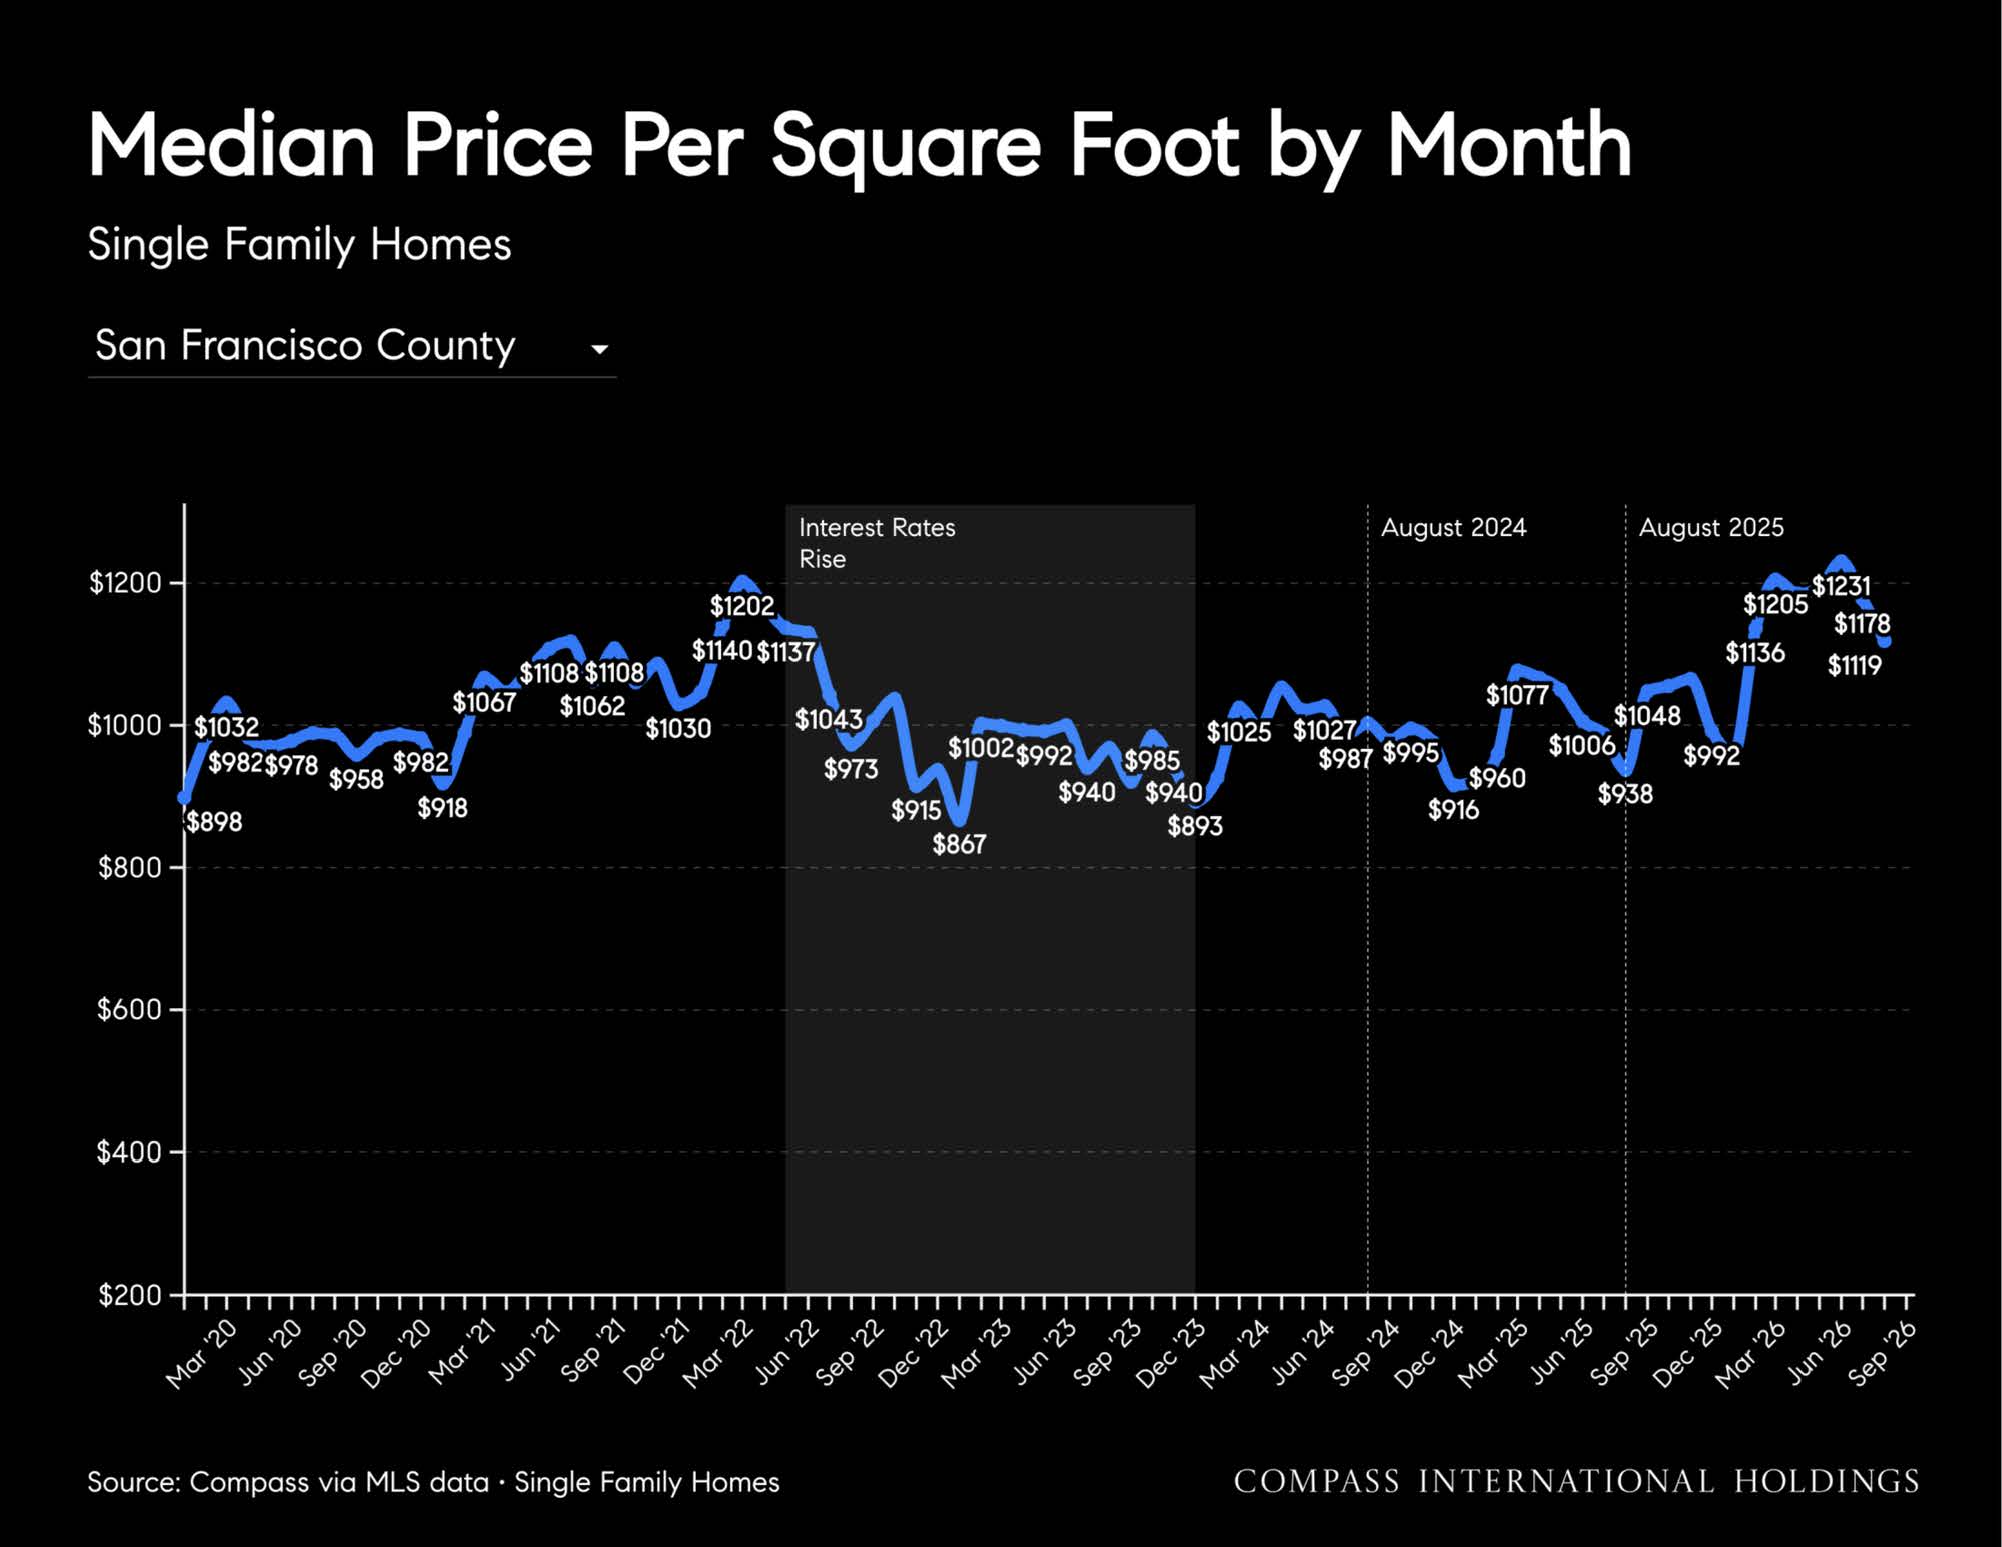
Here are some quick year-over-year figures based on San Francisco’s most recent data, compiled through the end of August:
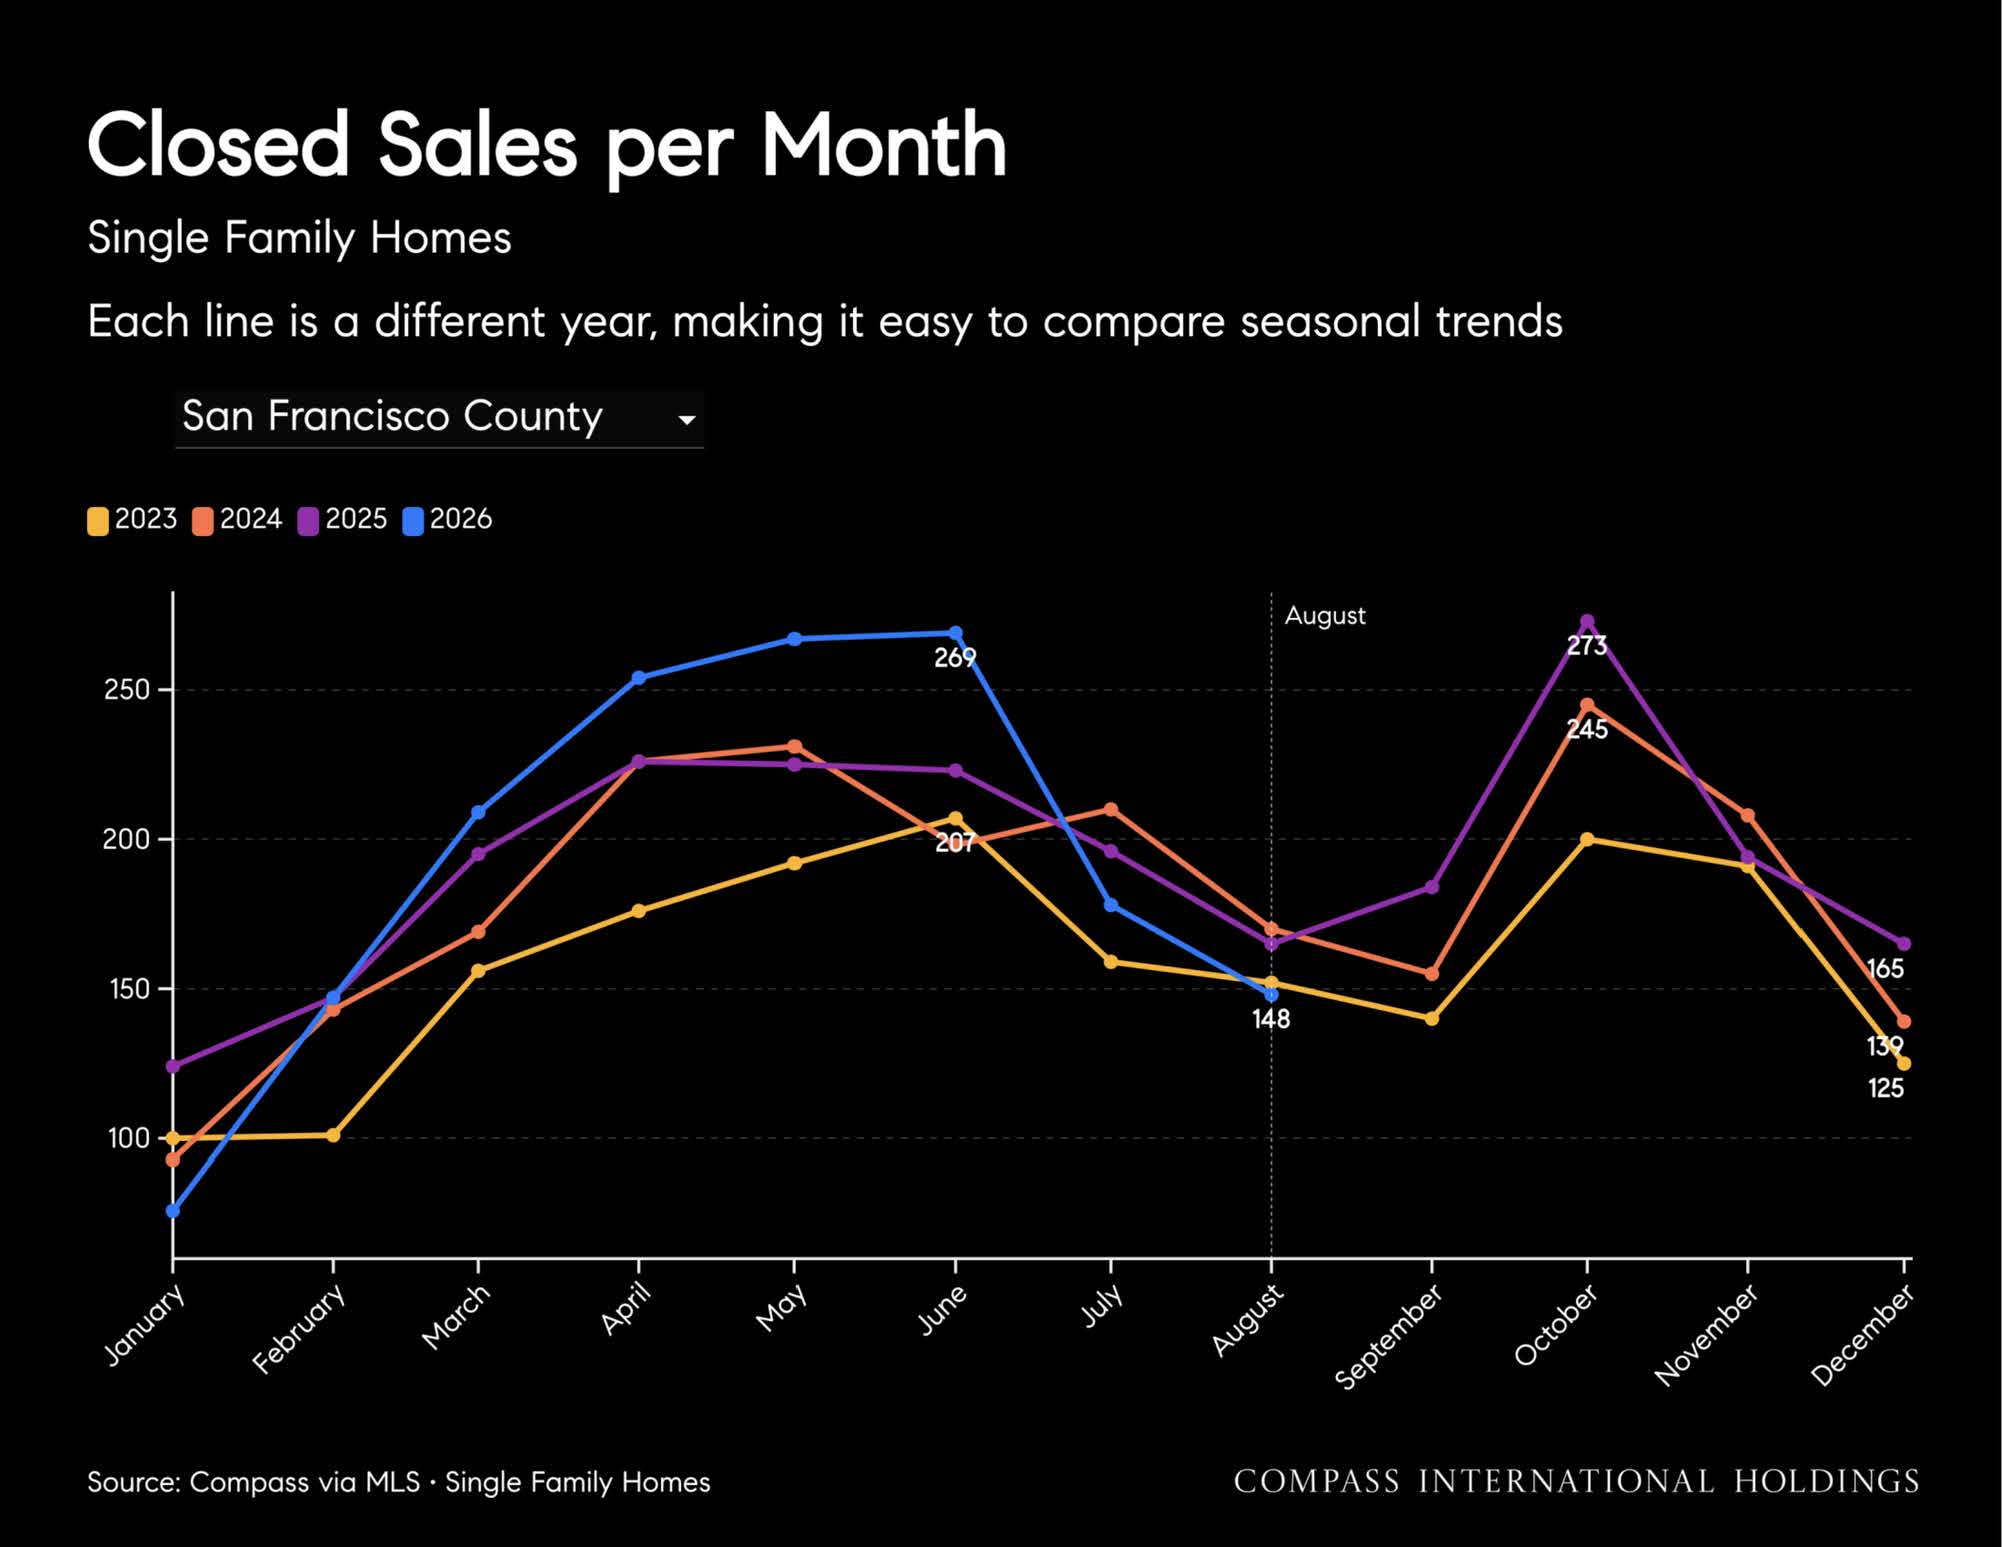
Single-family homes
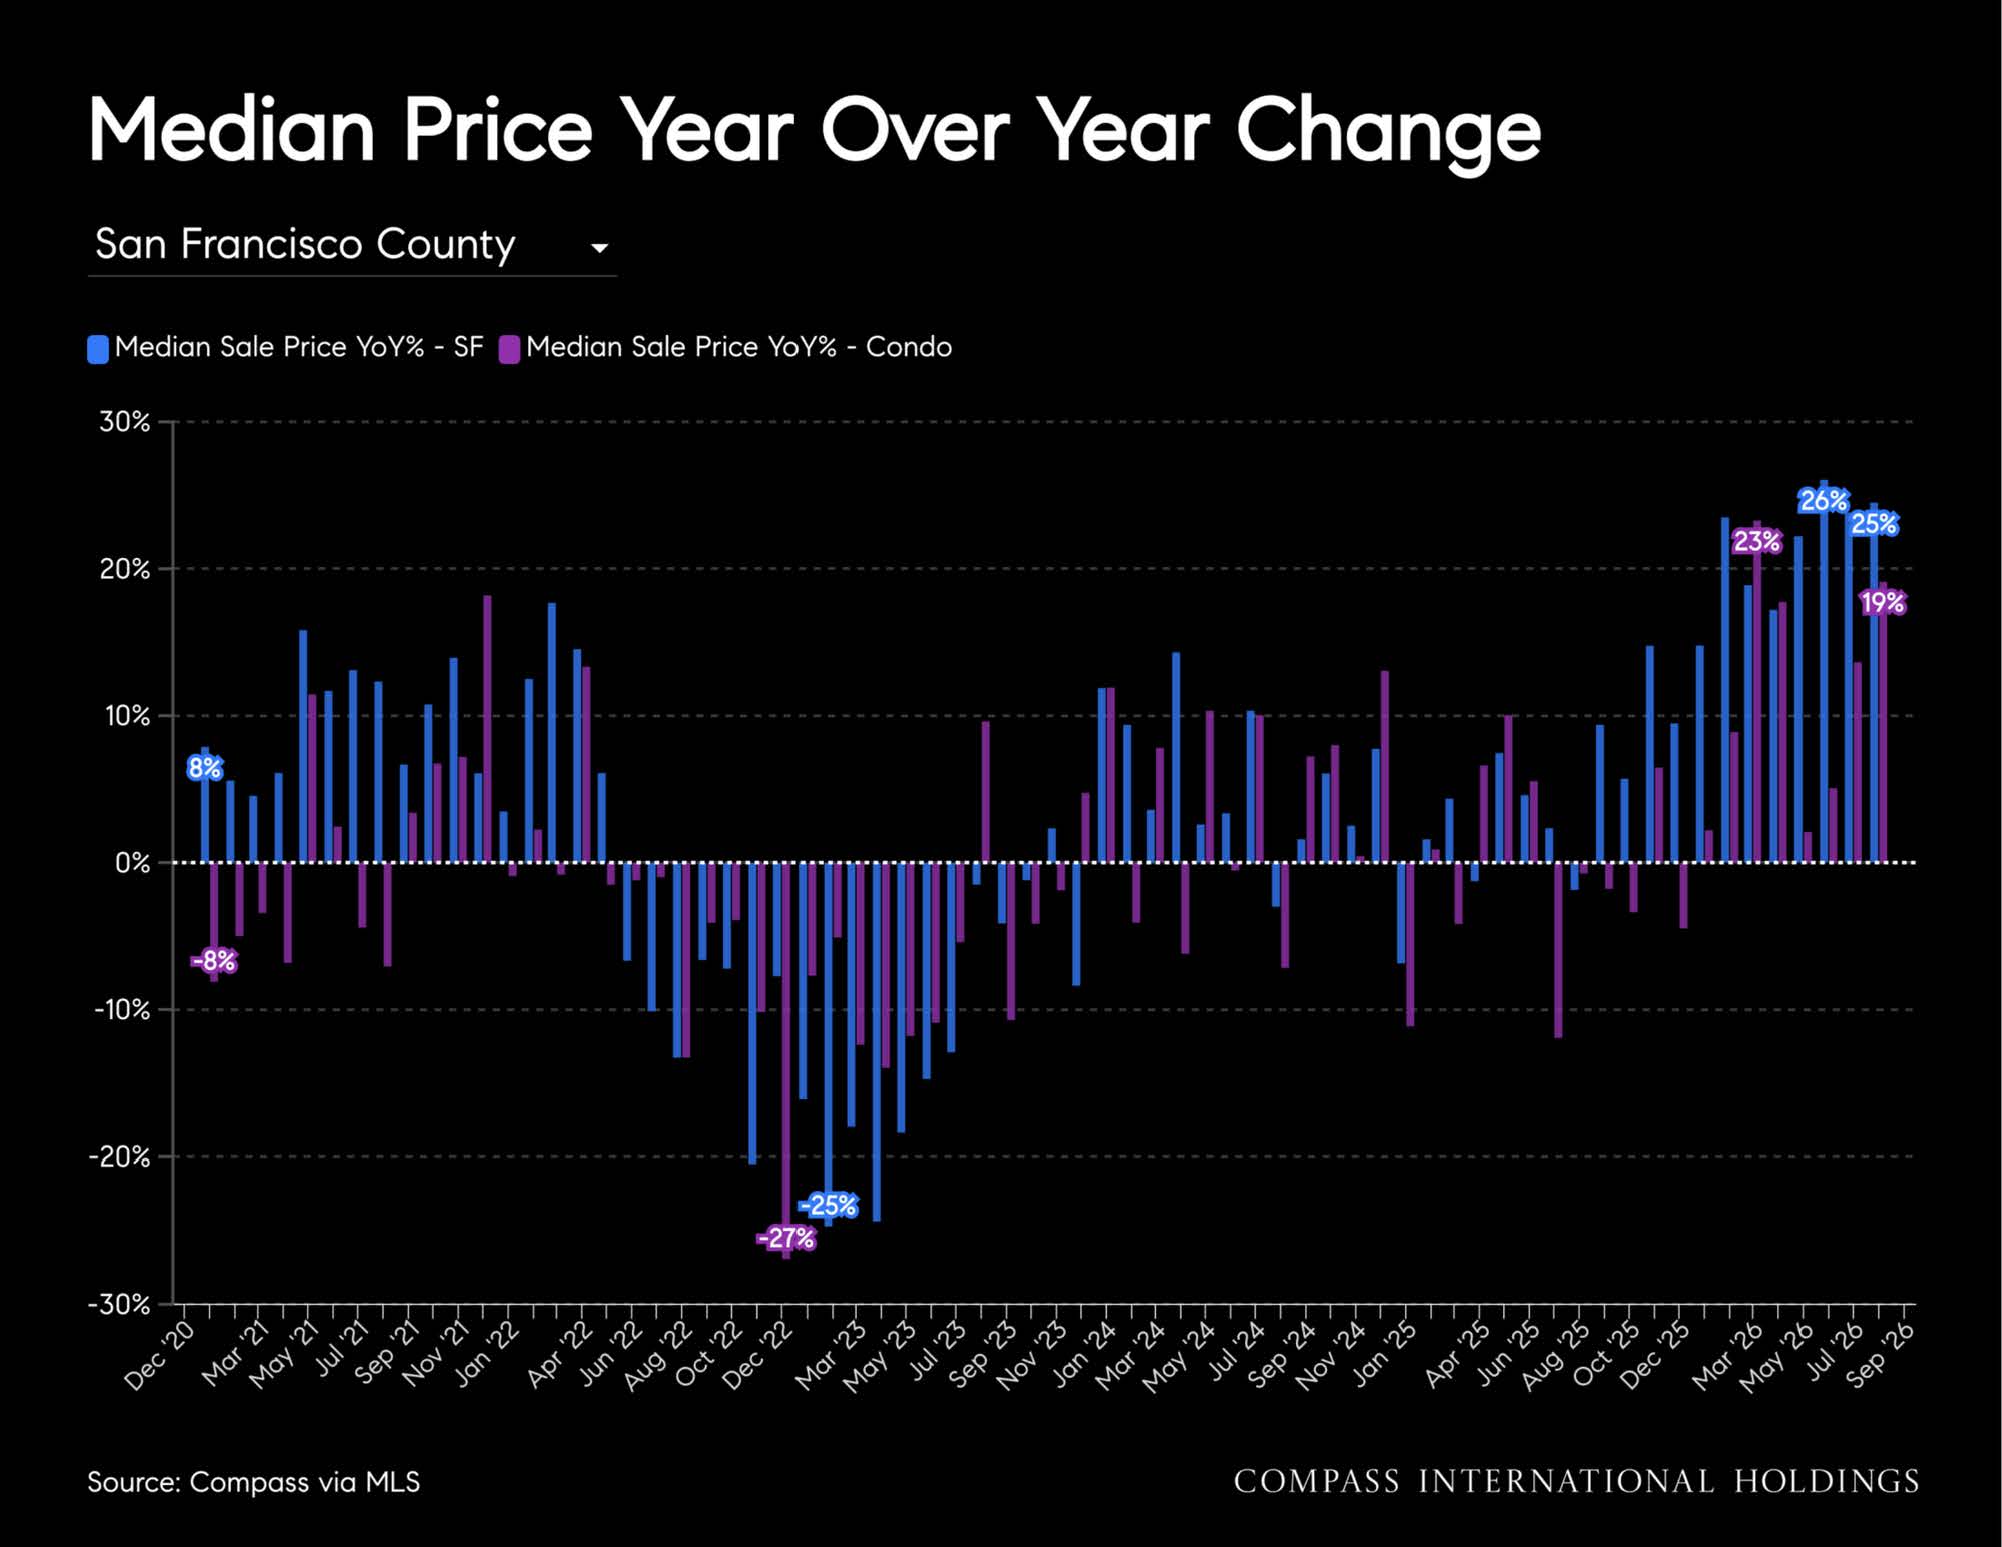
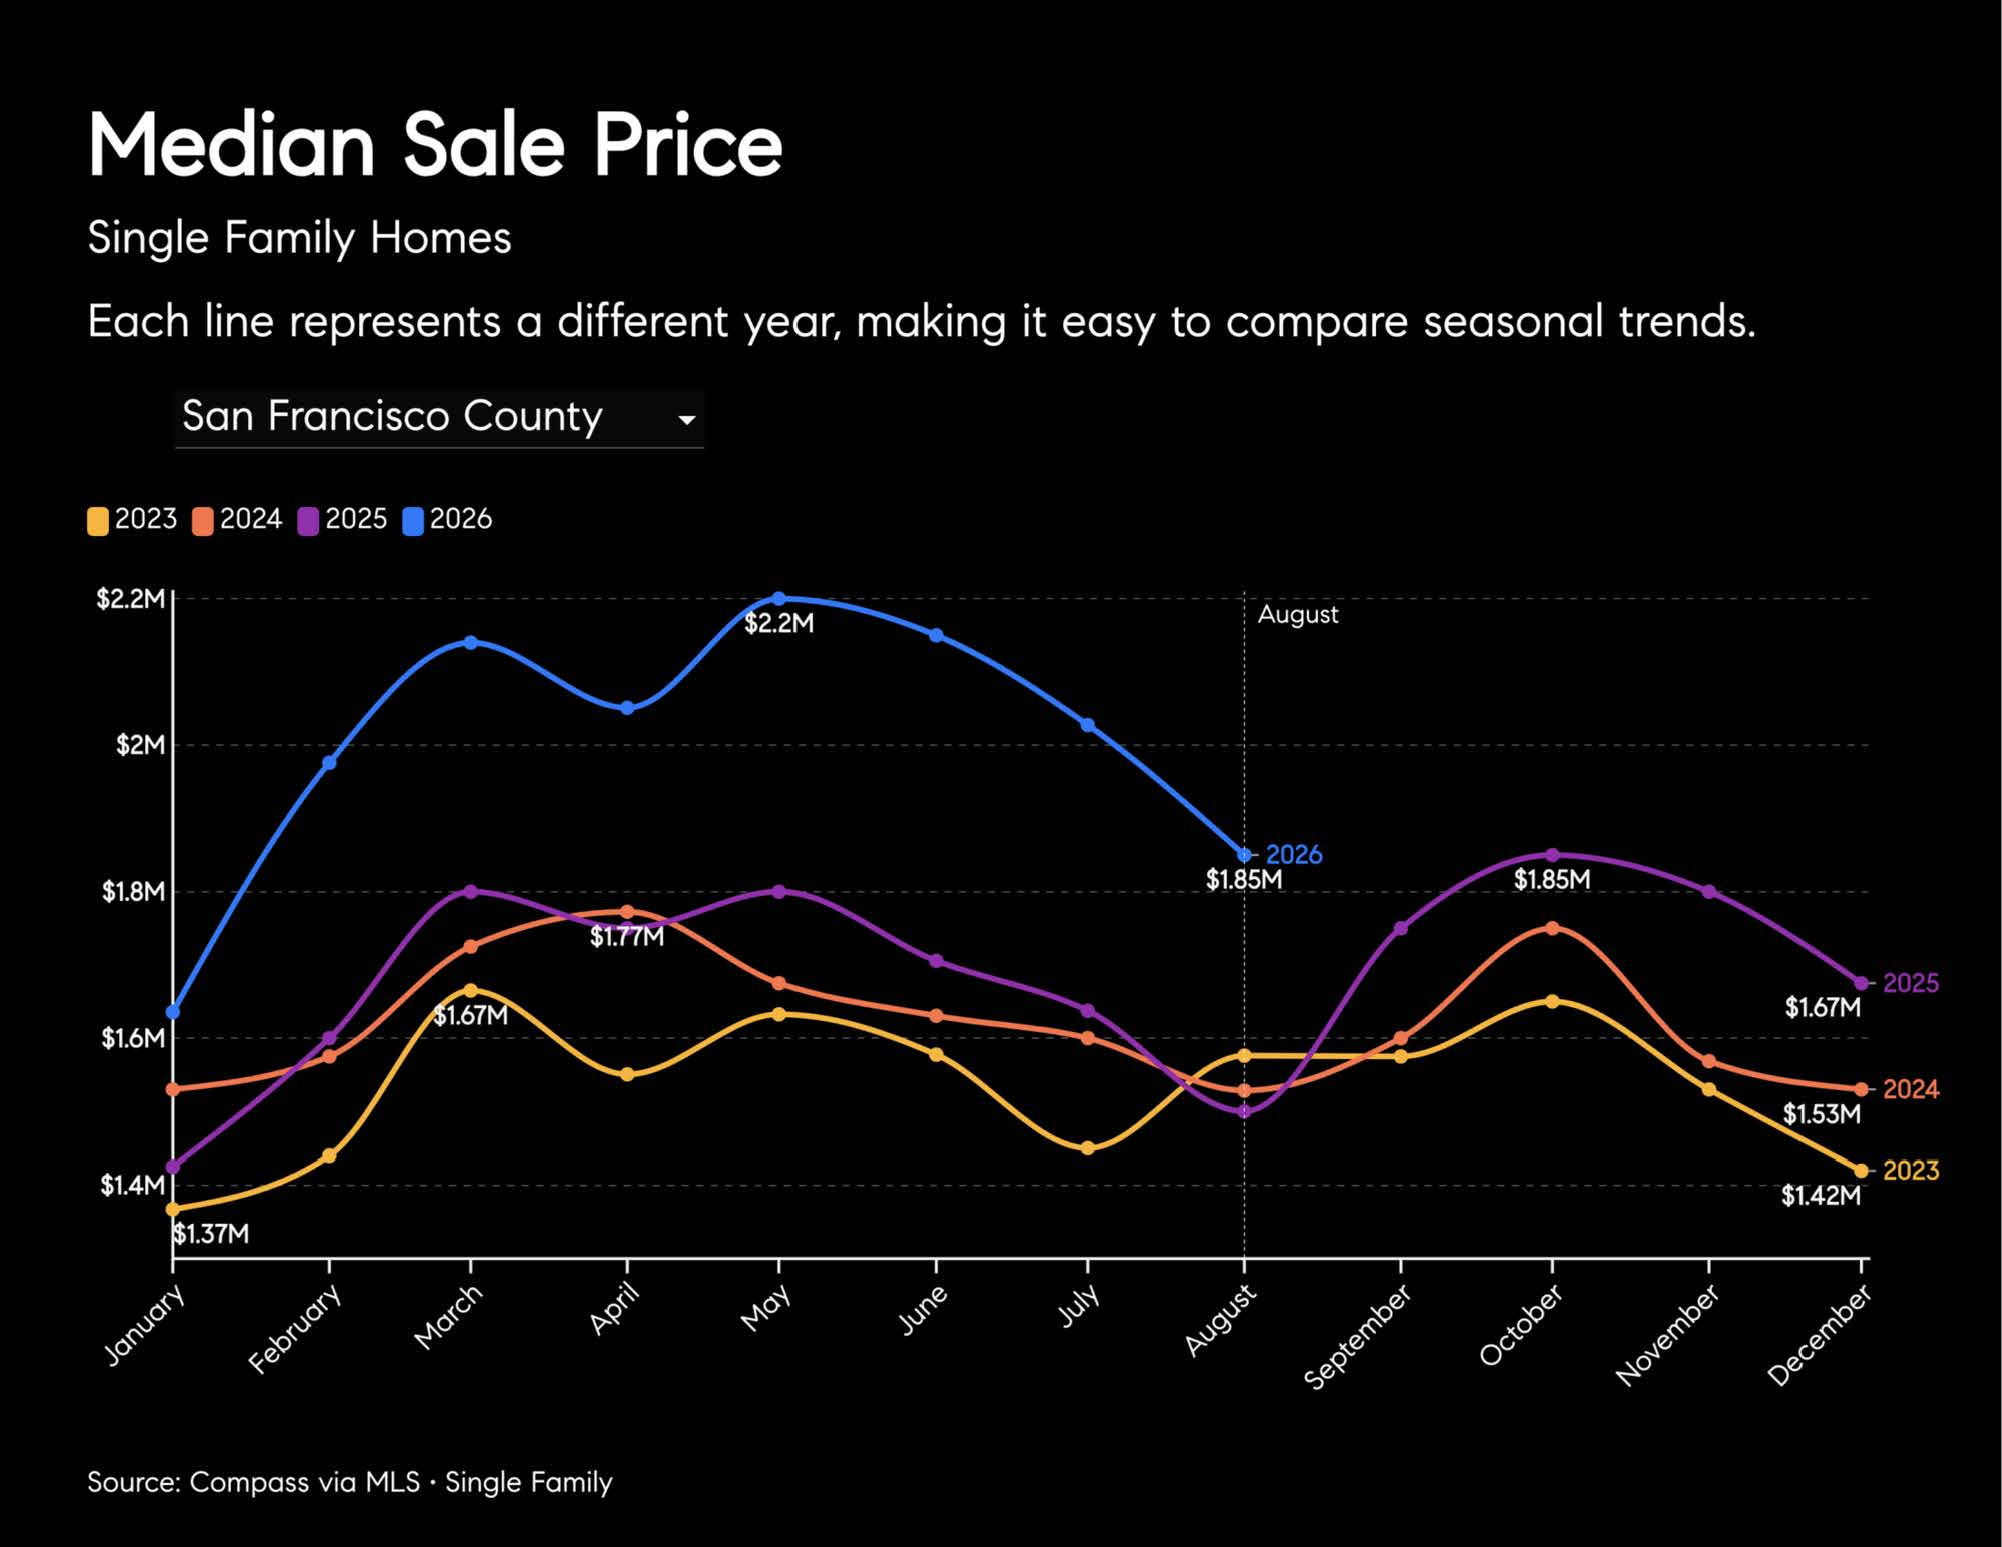
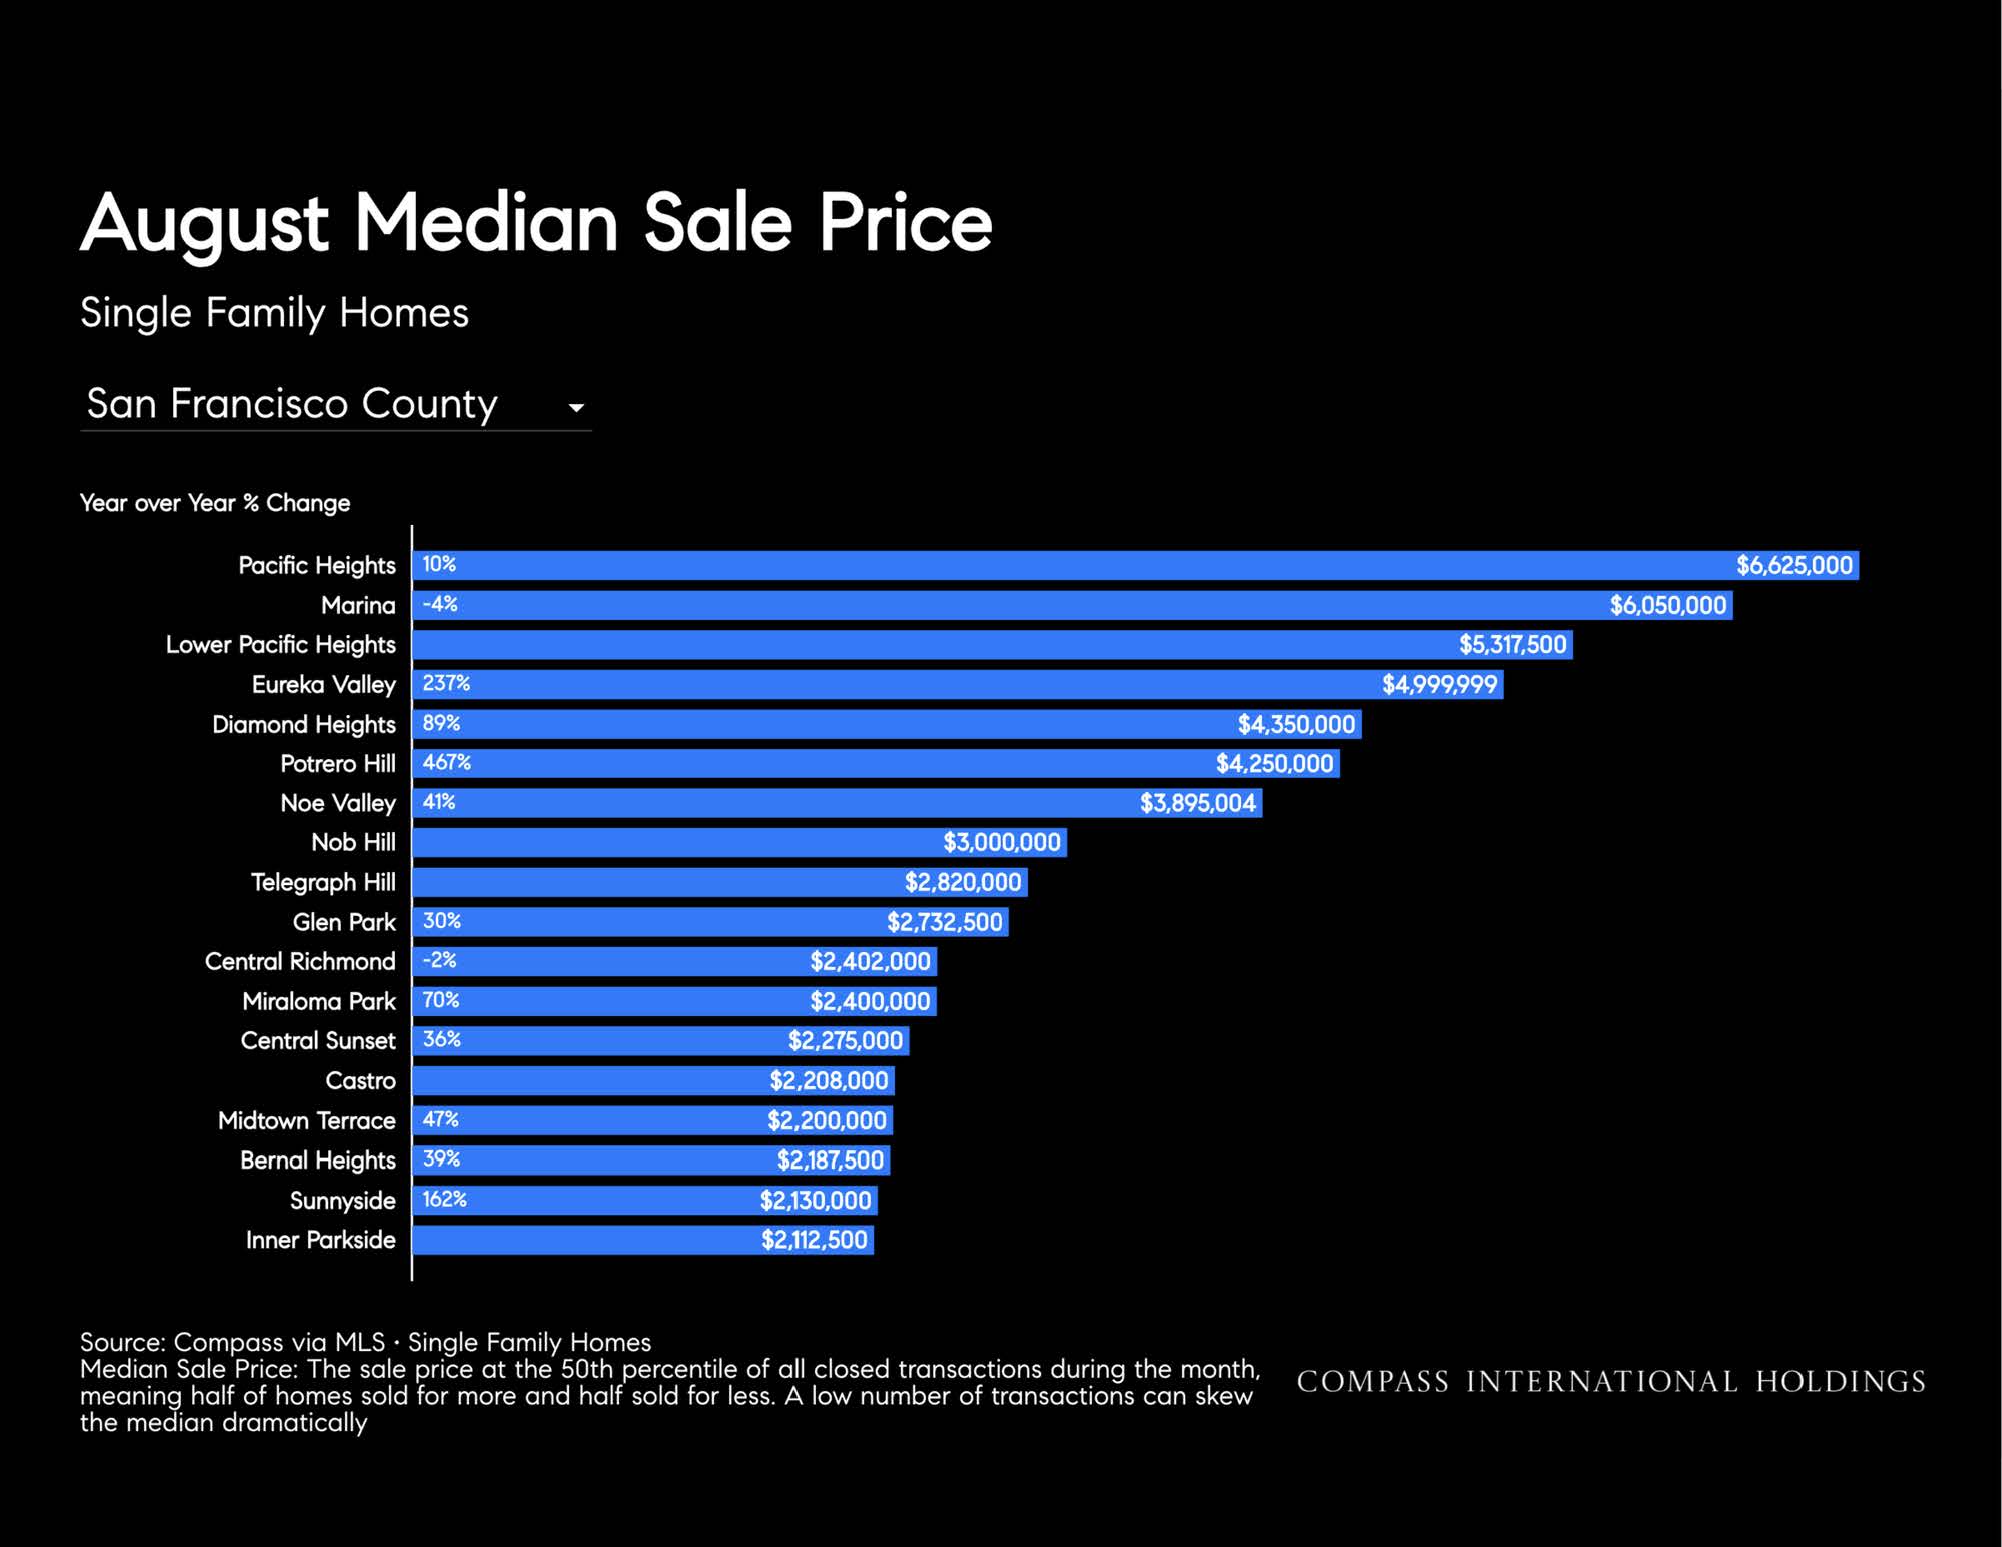
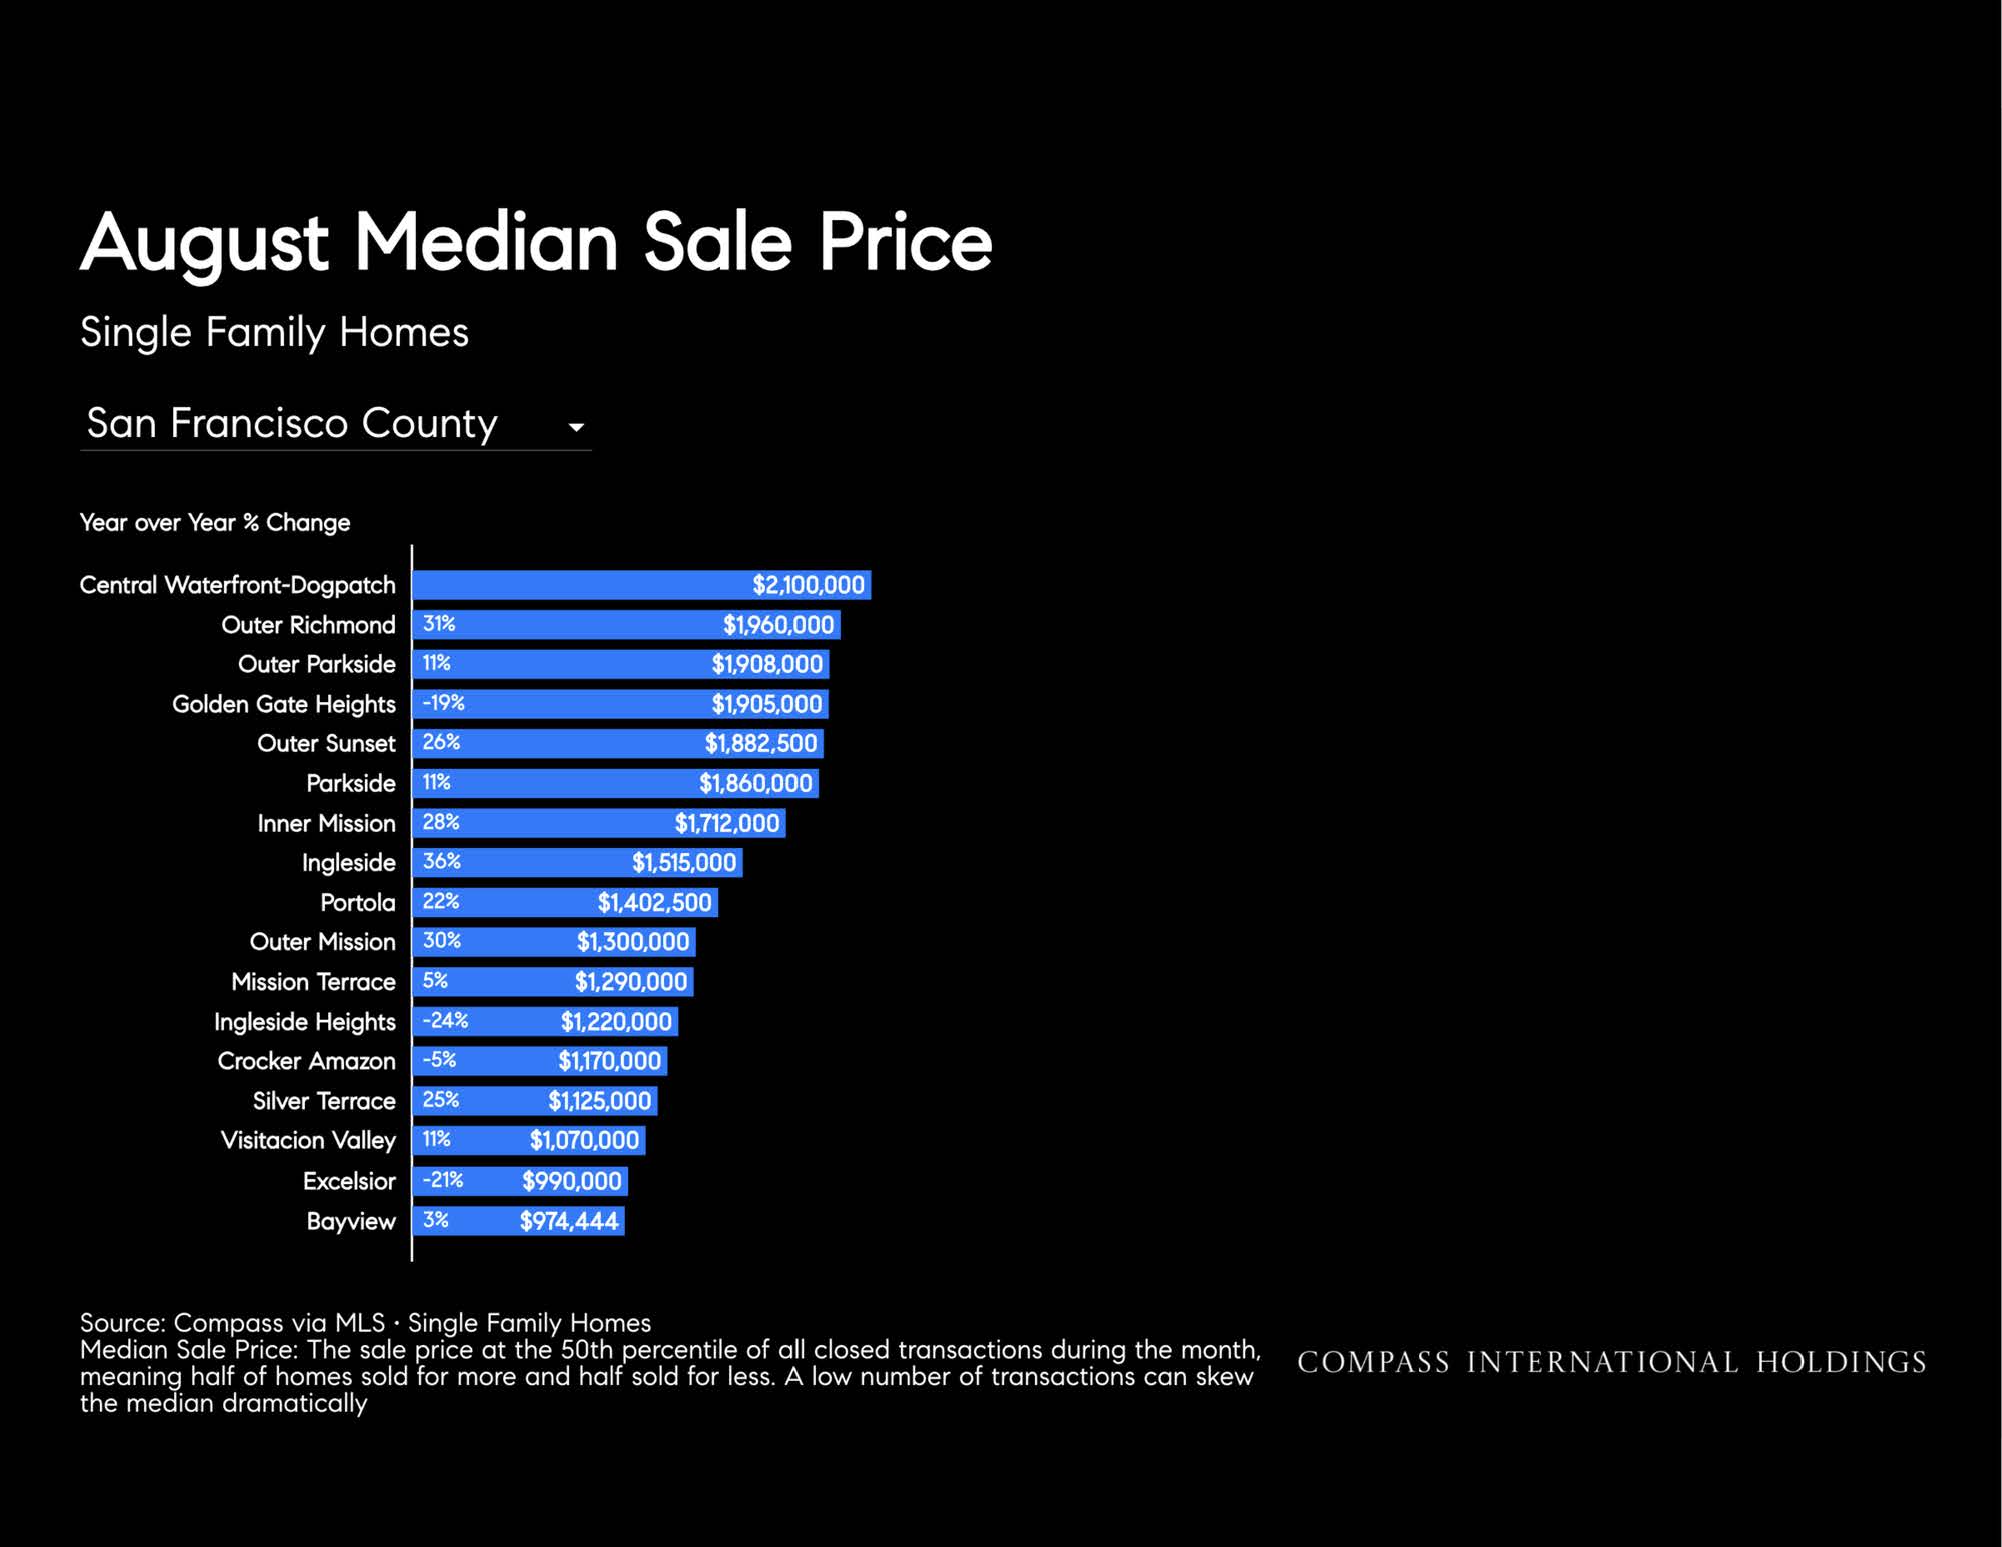
Median price: +23.3% to $1,855,000
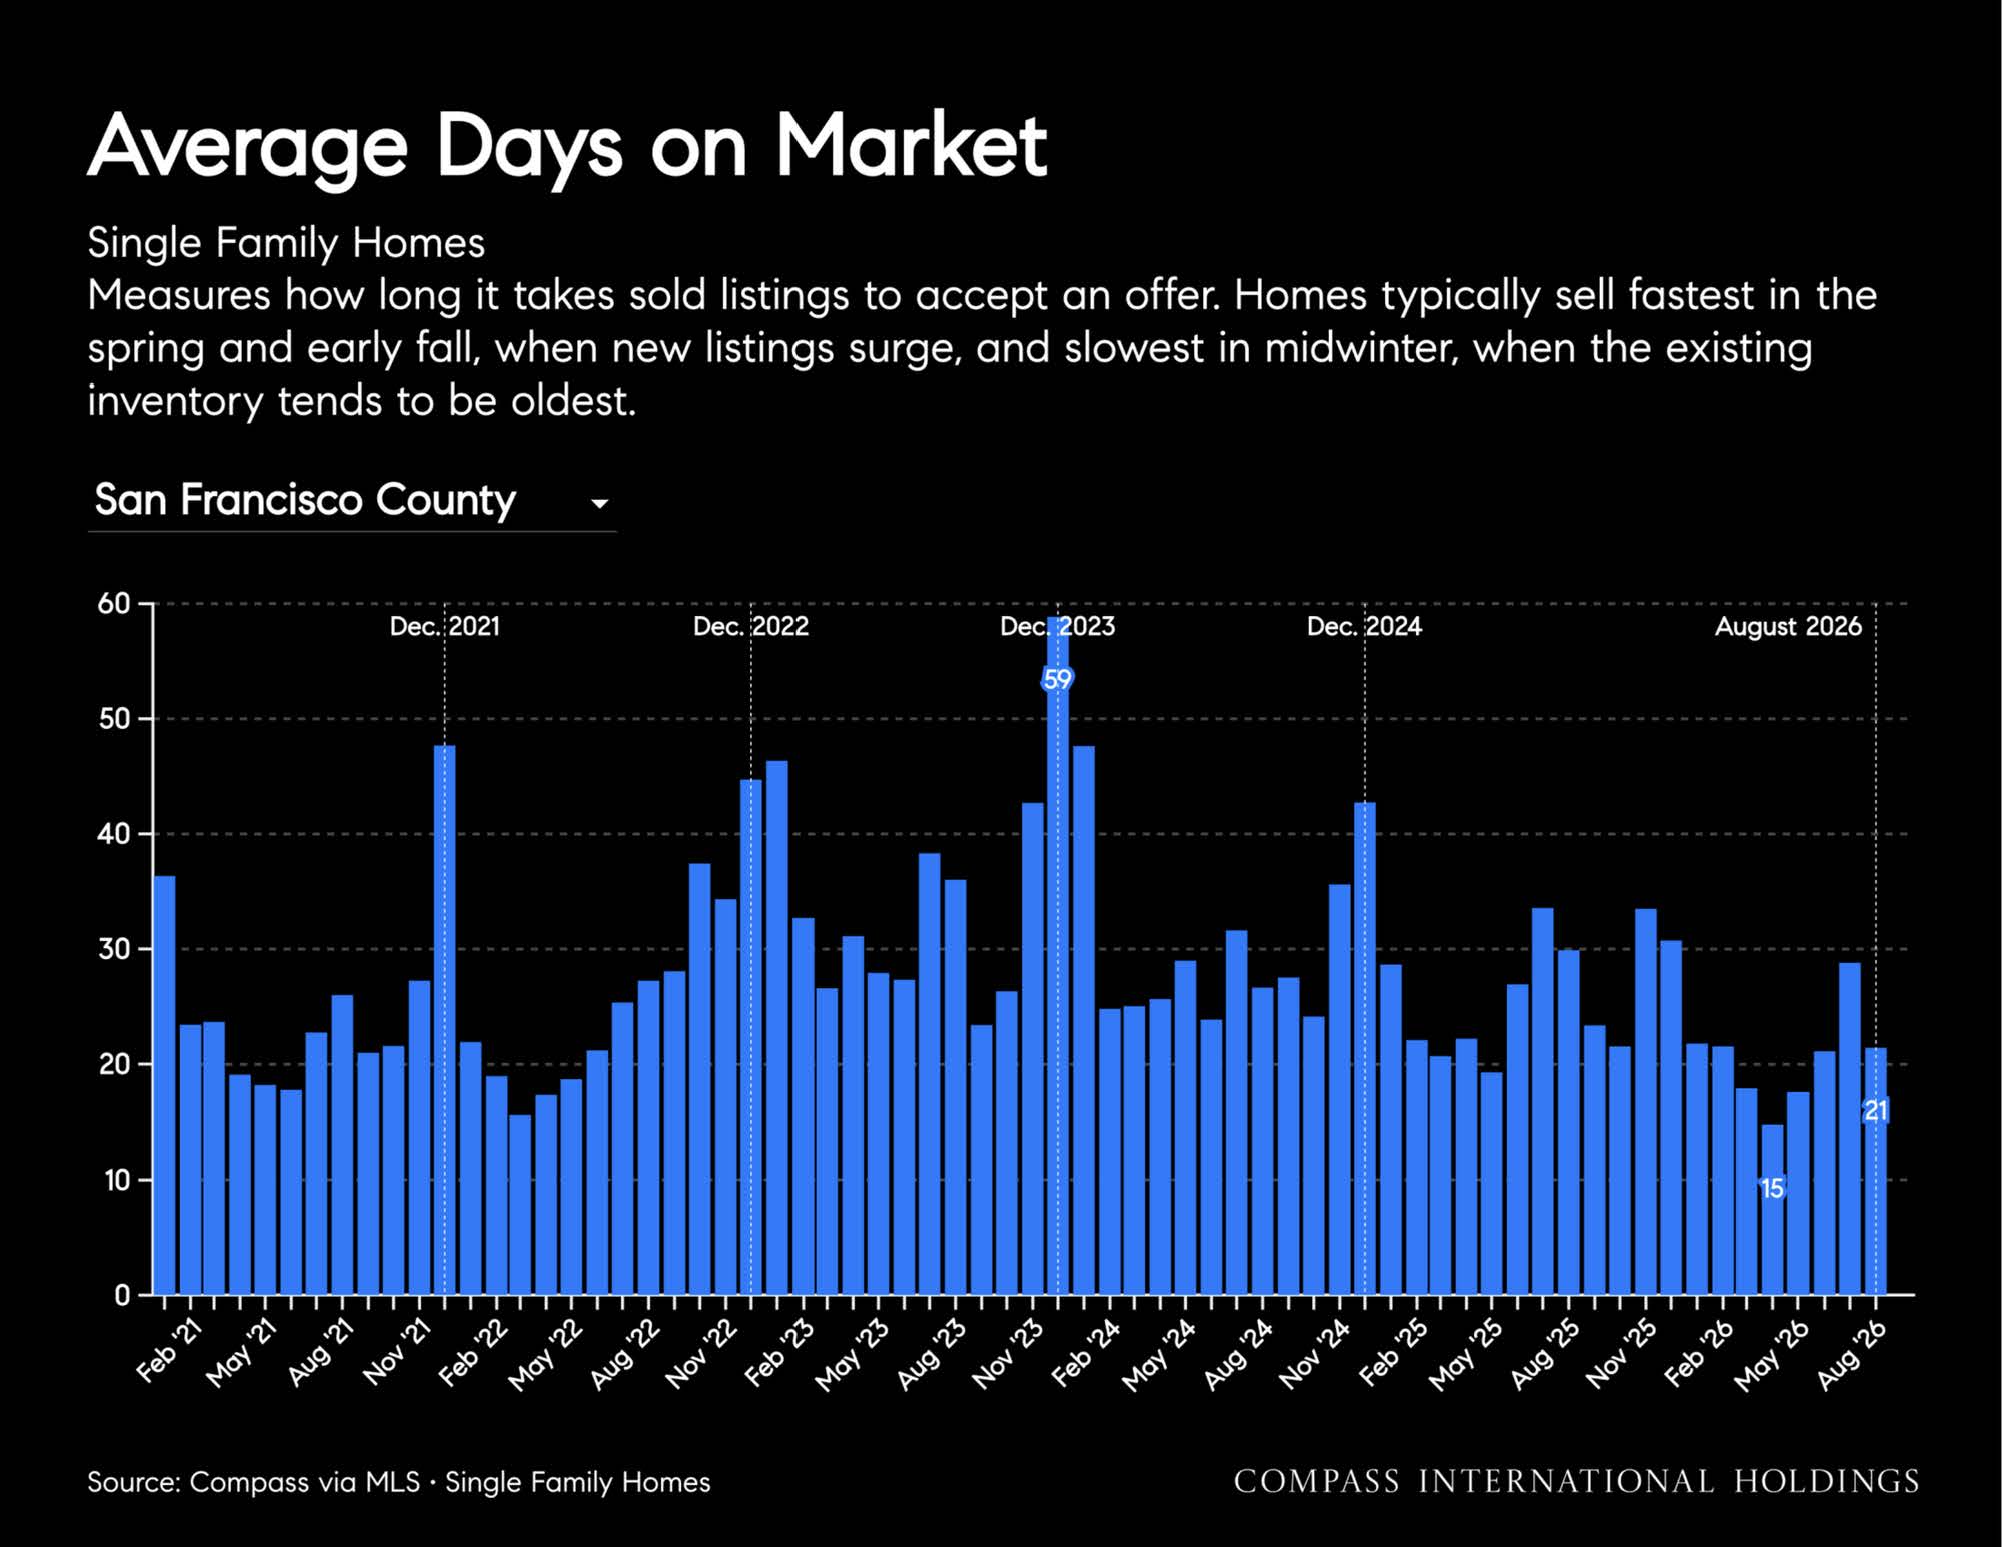
Days on market: -18.8% to 13 days
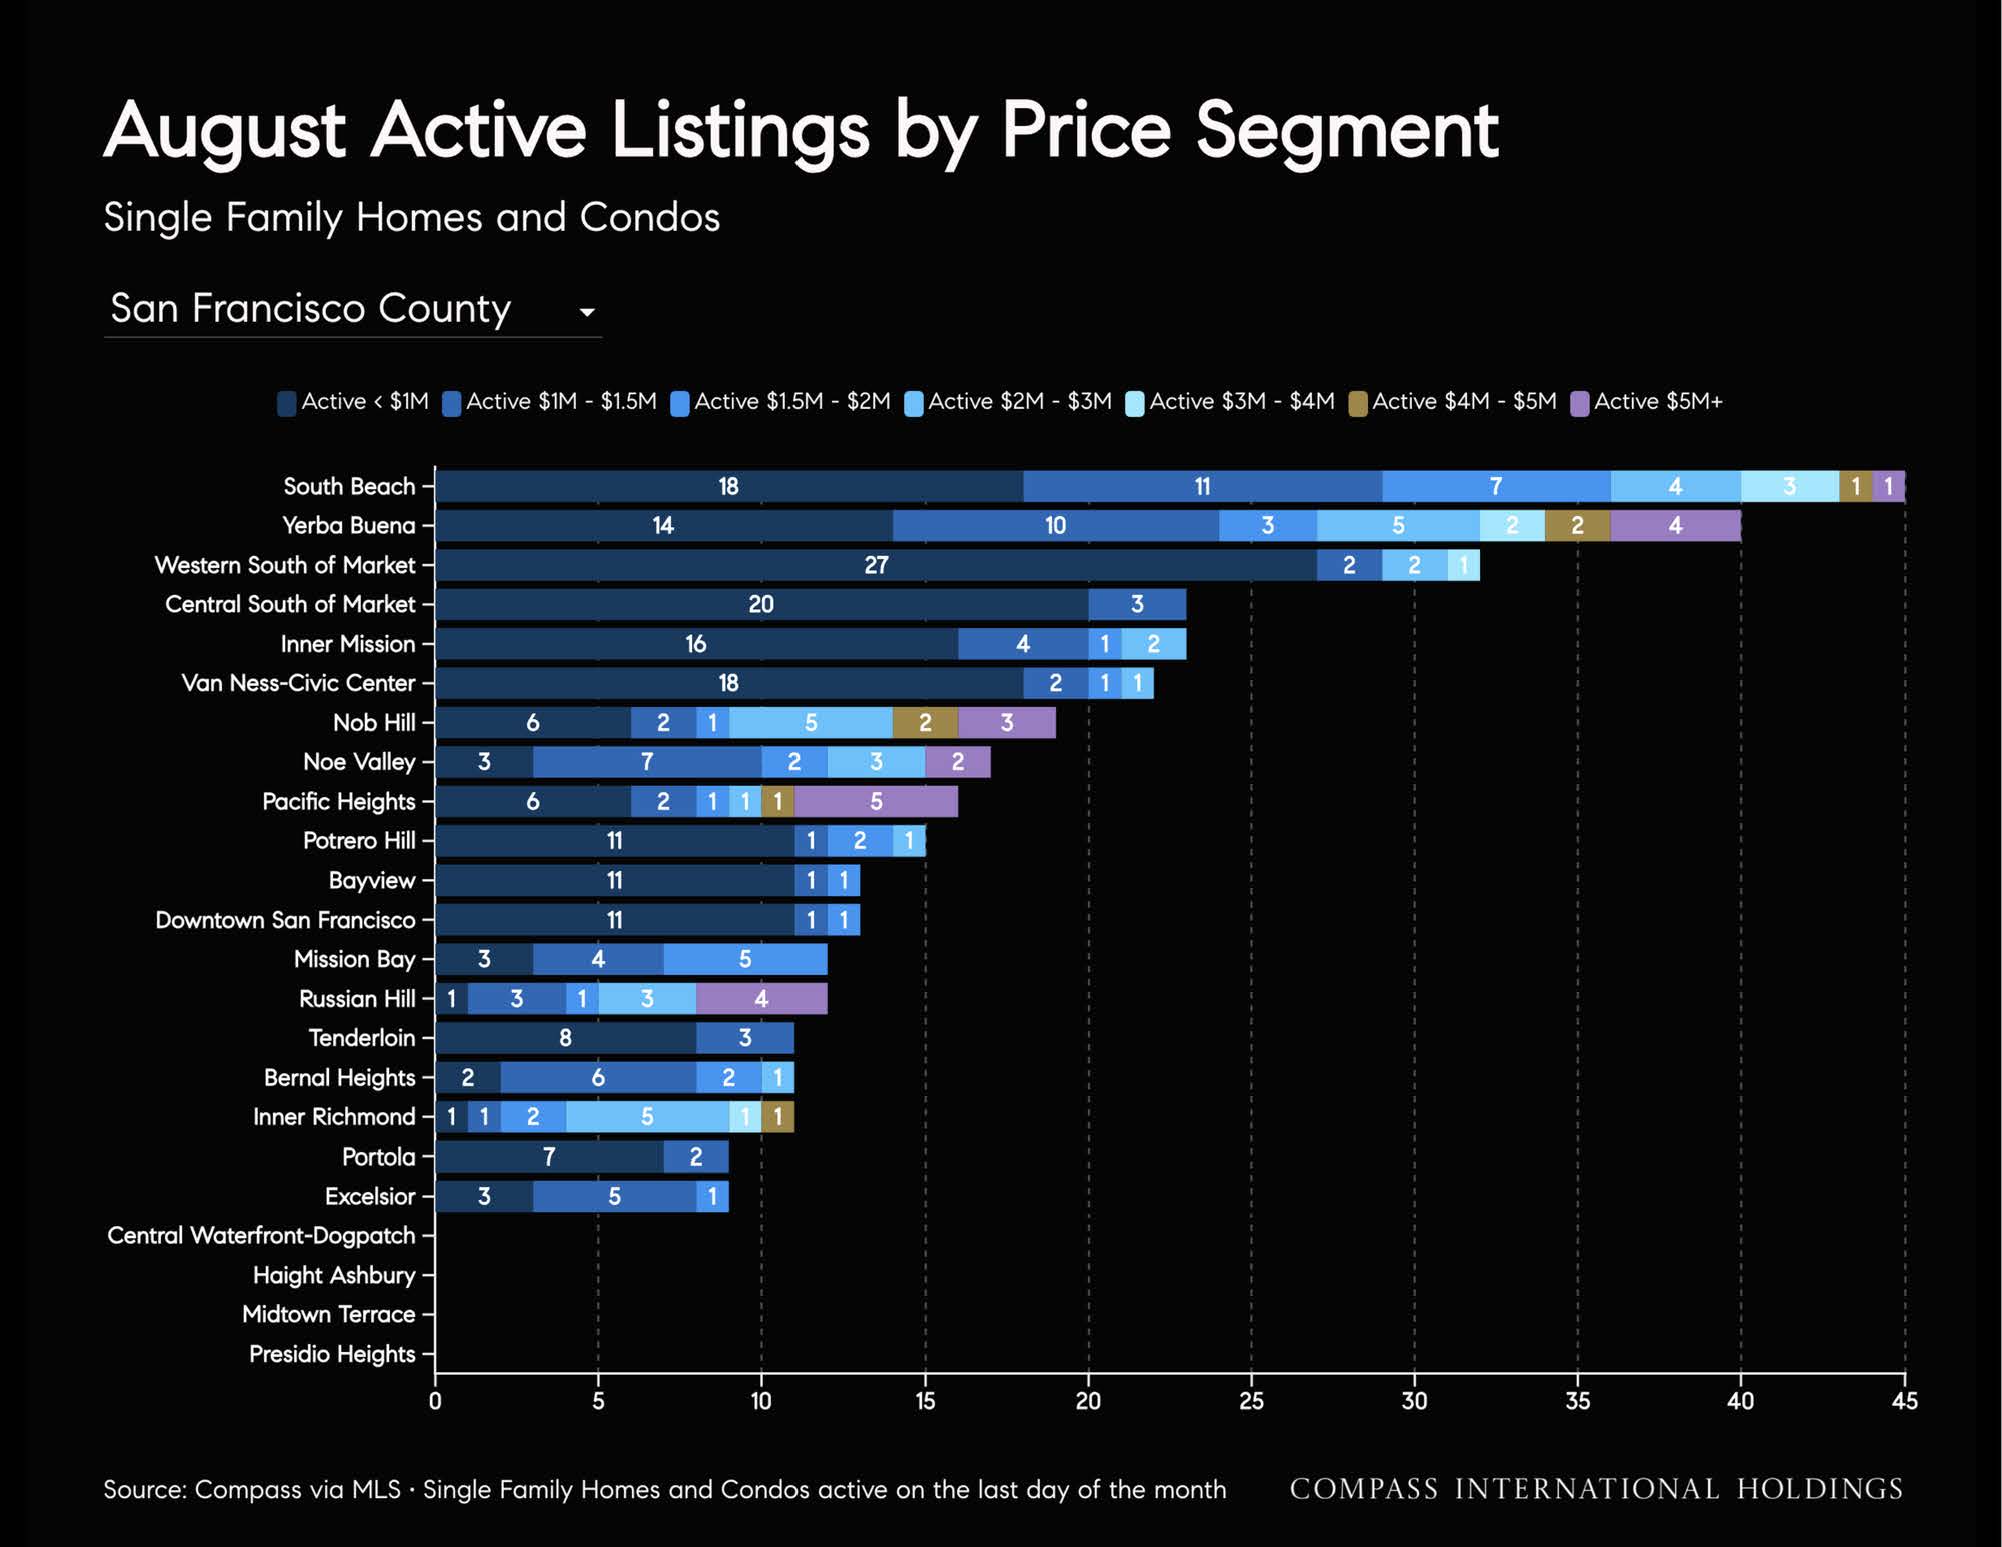
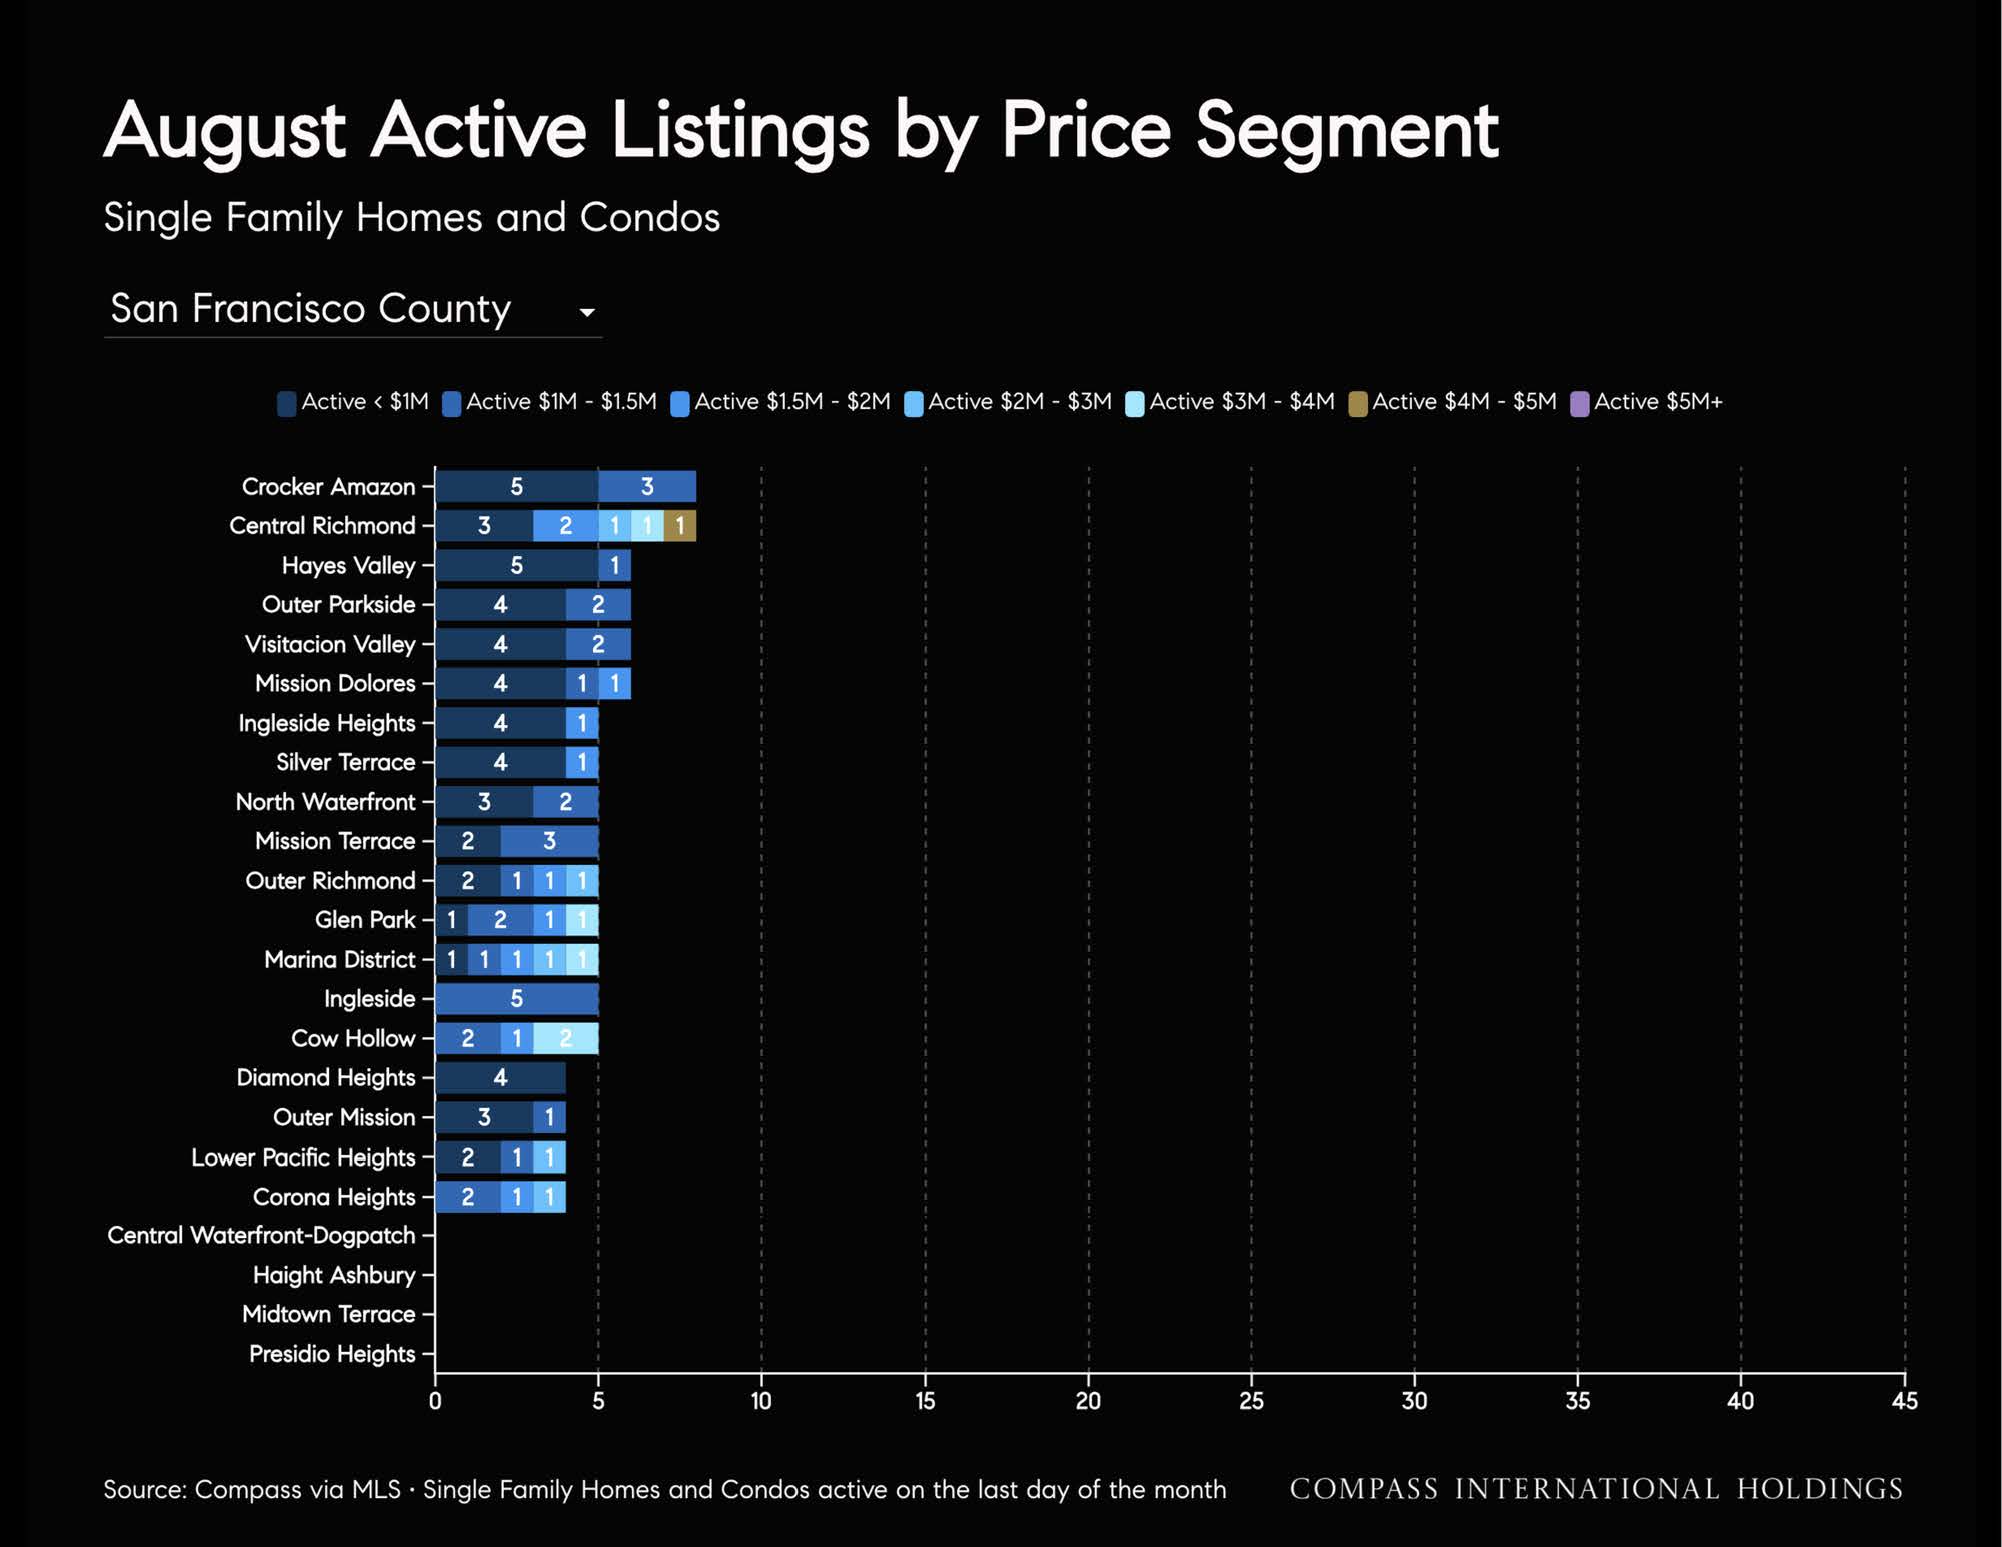
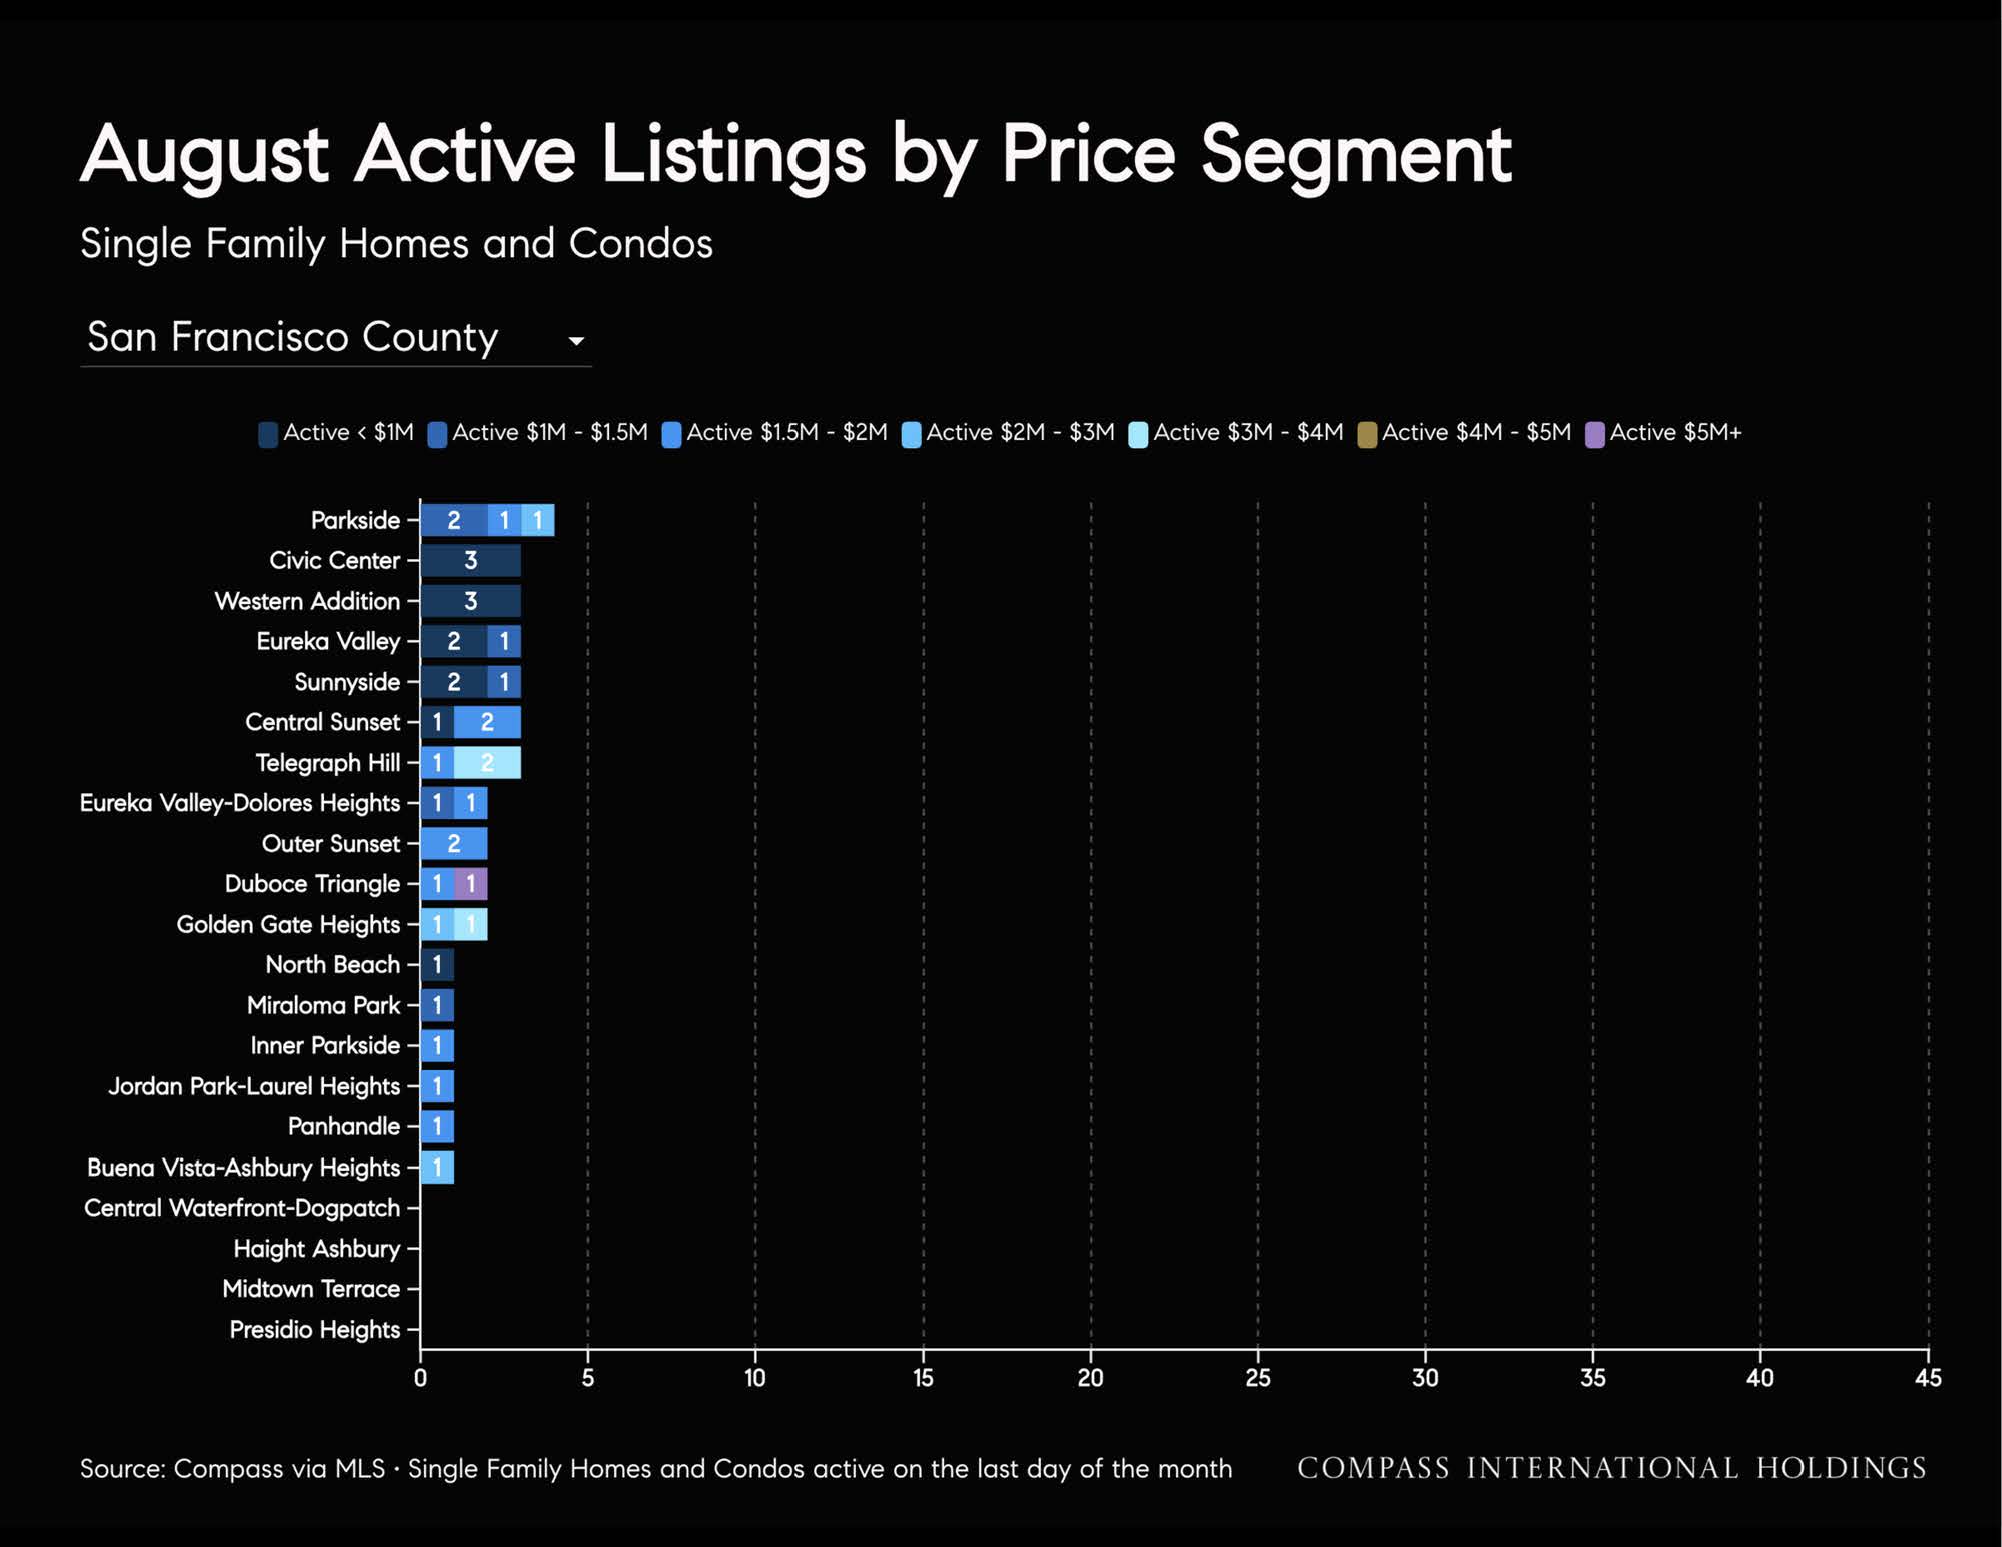
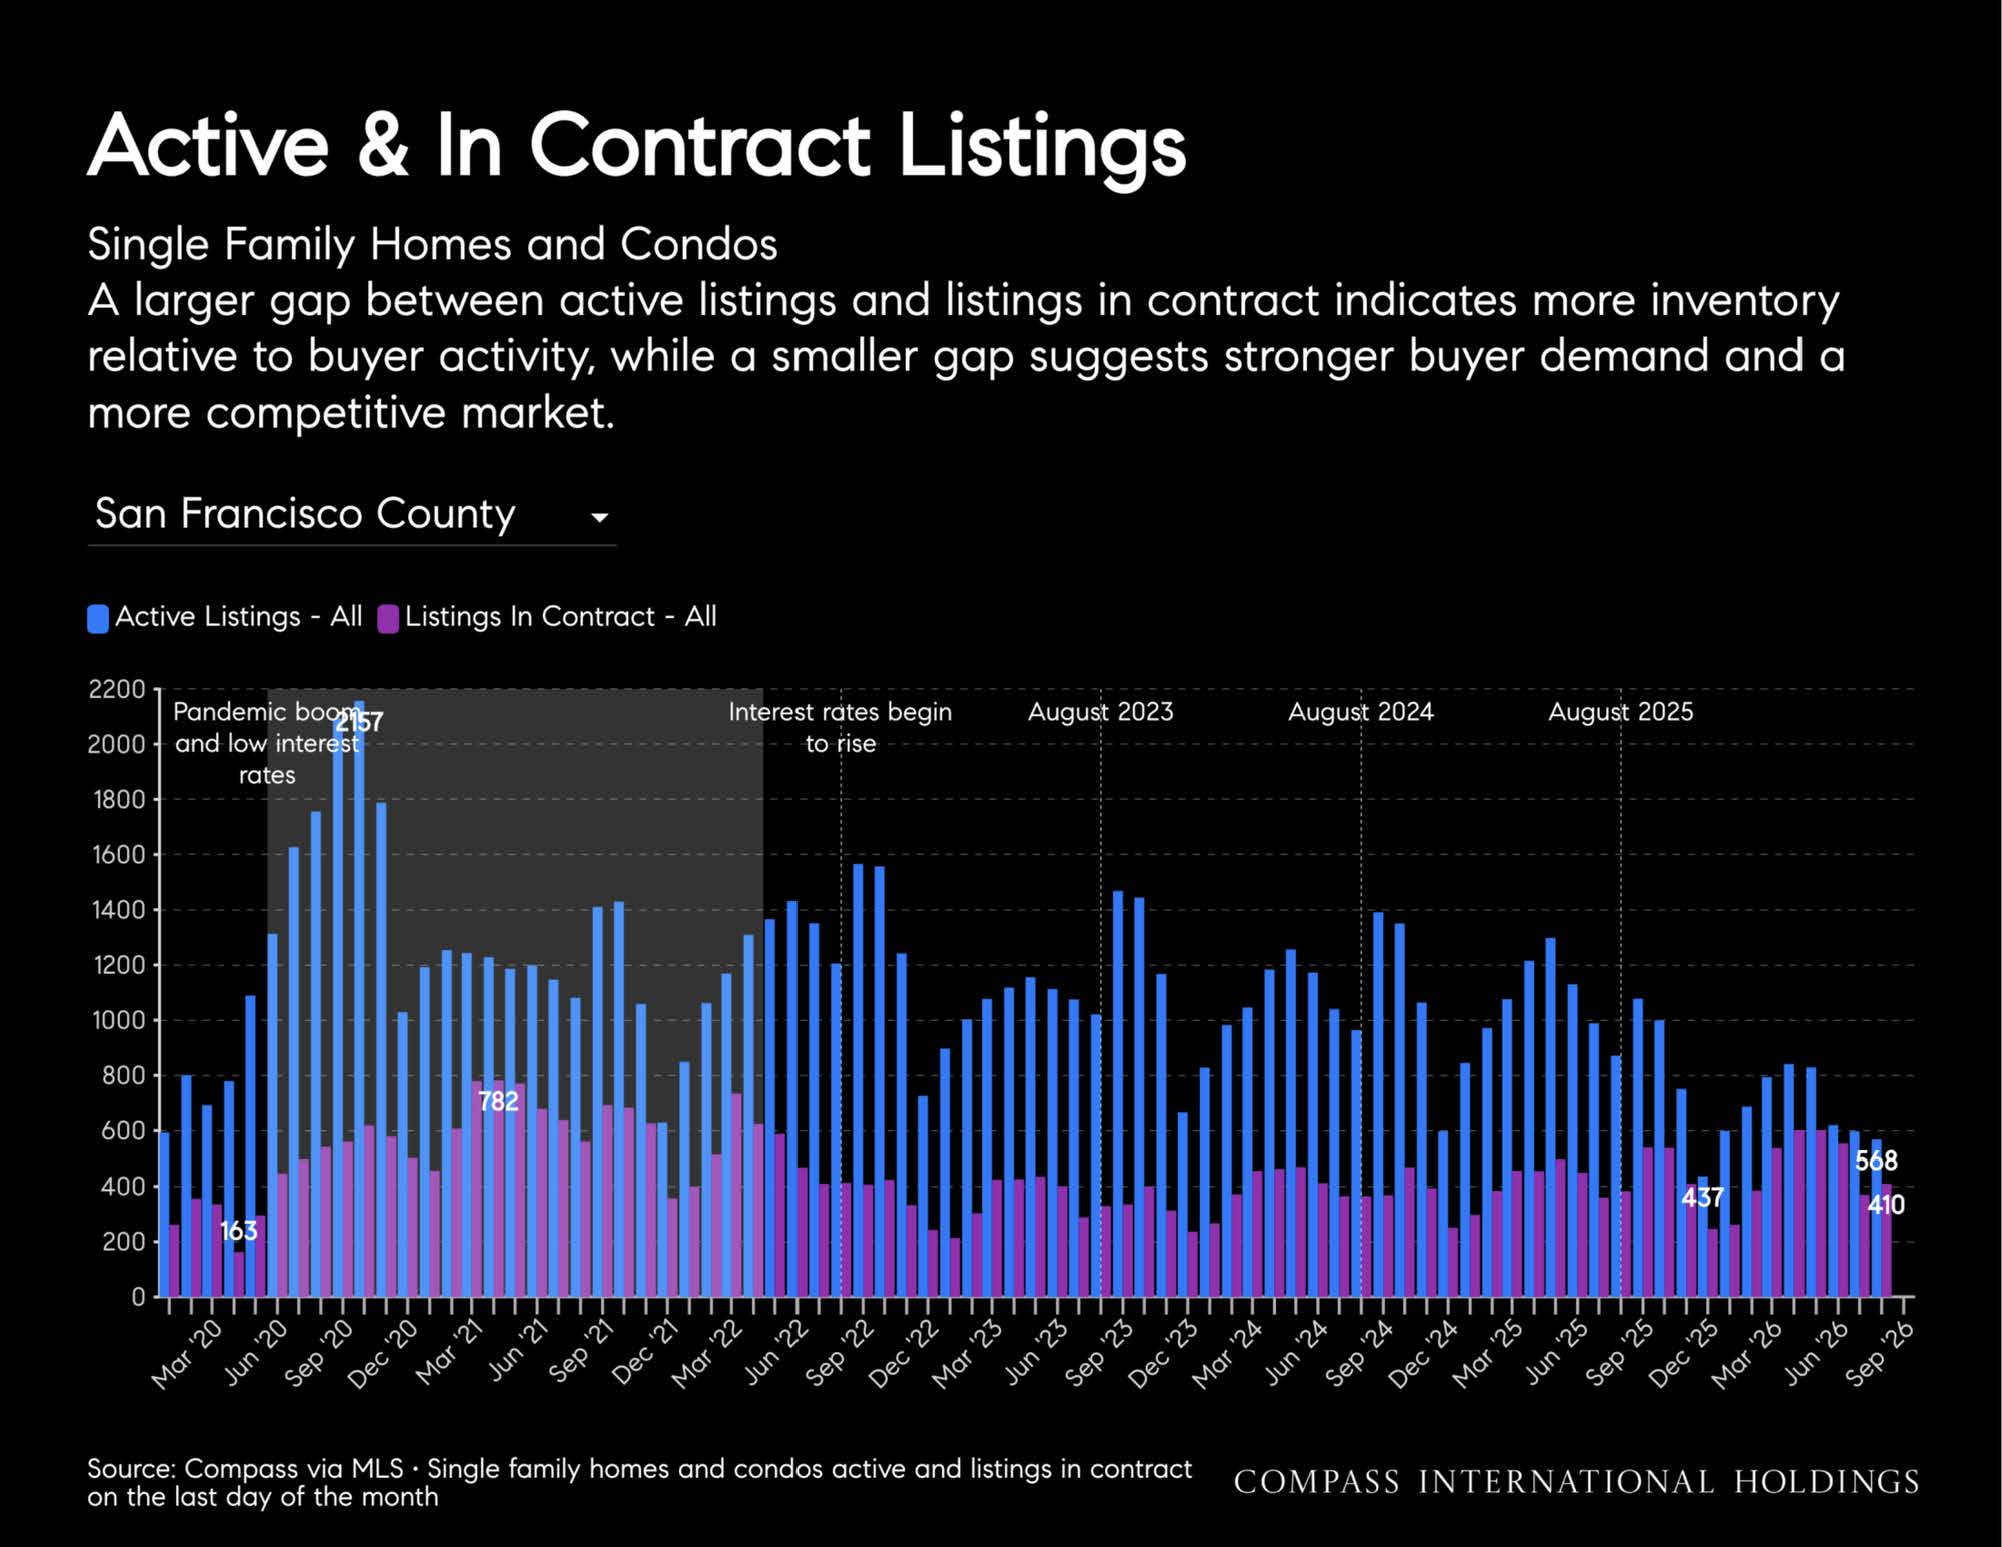
Active listings: -33%
Sold listings: -7%
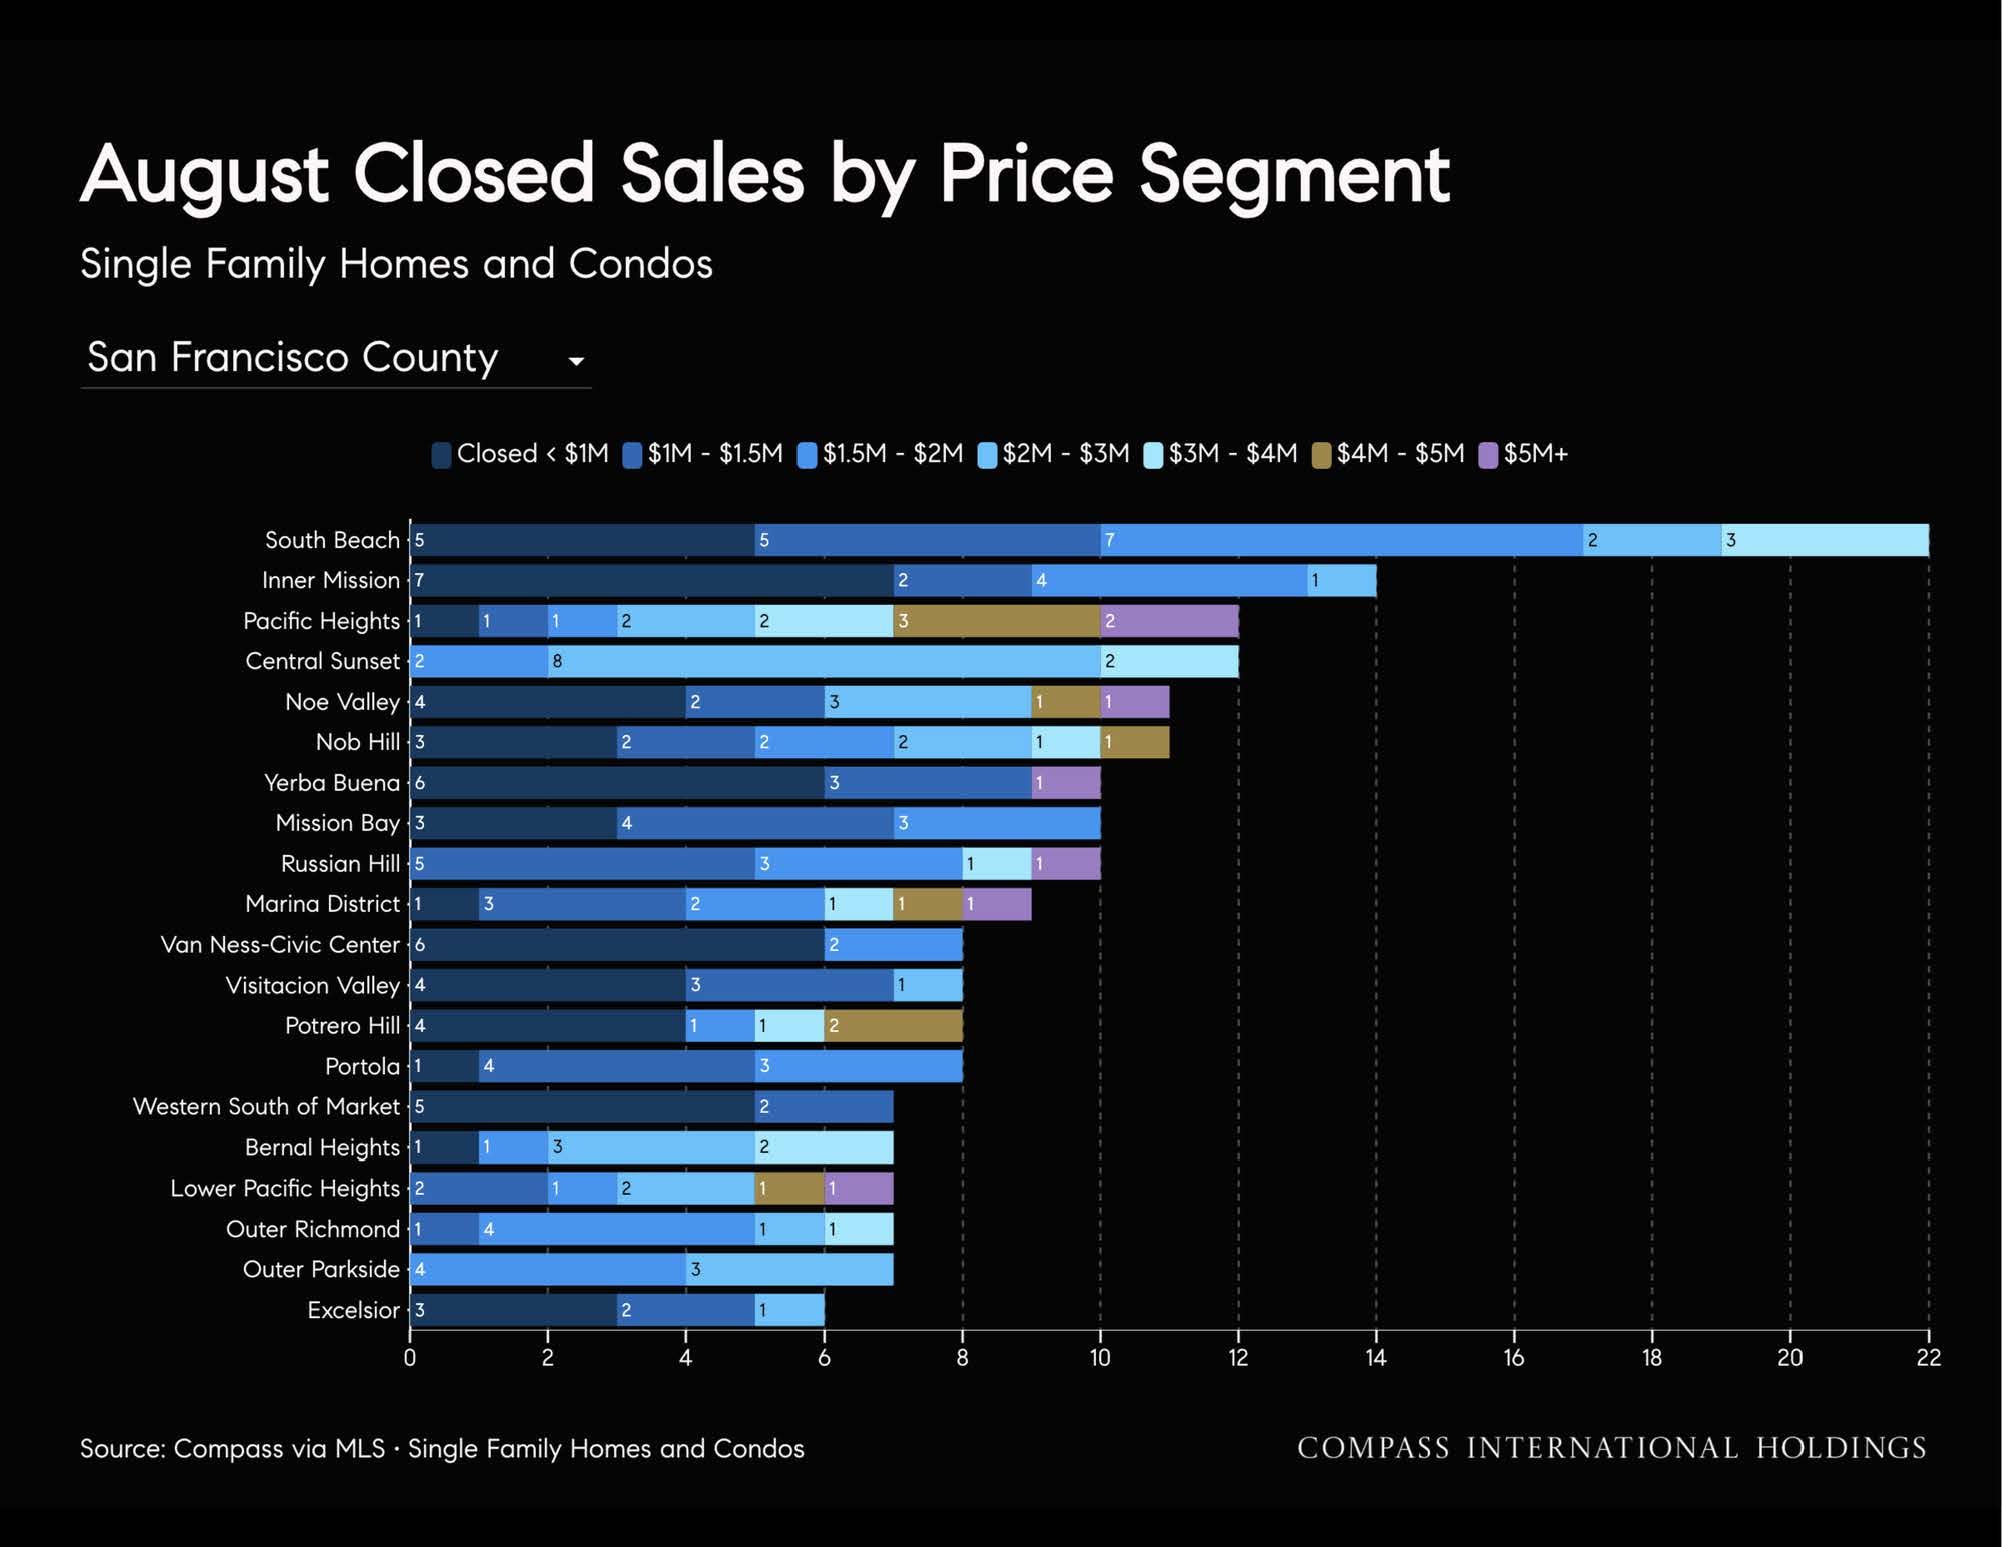
Condos
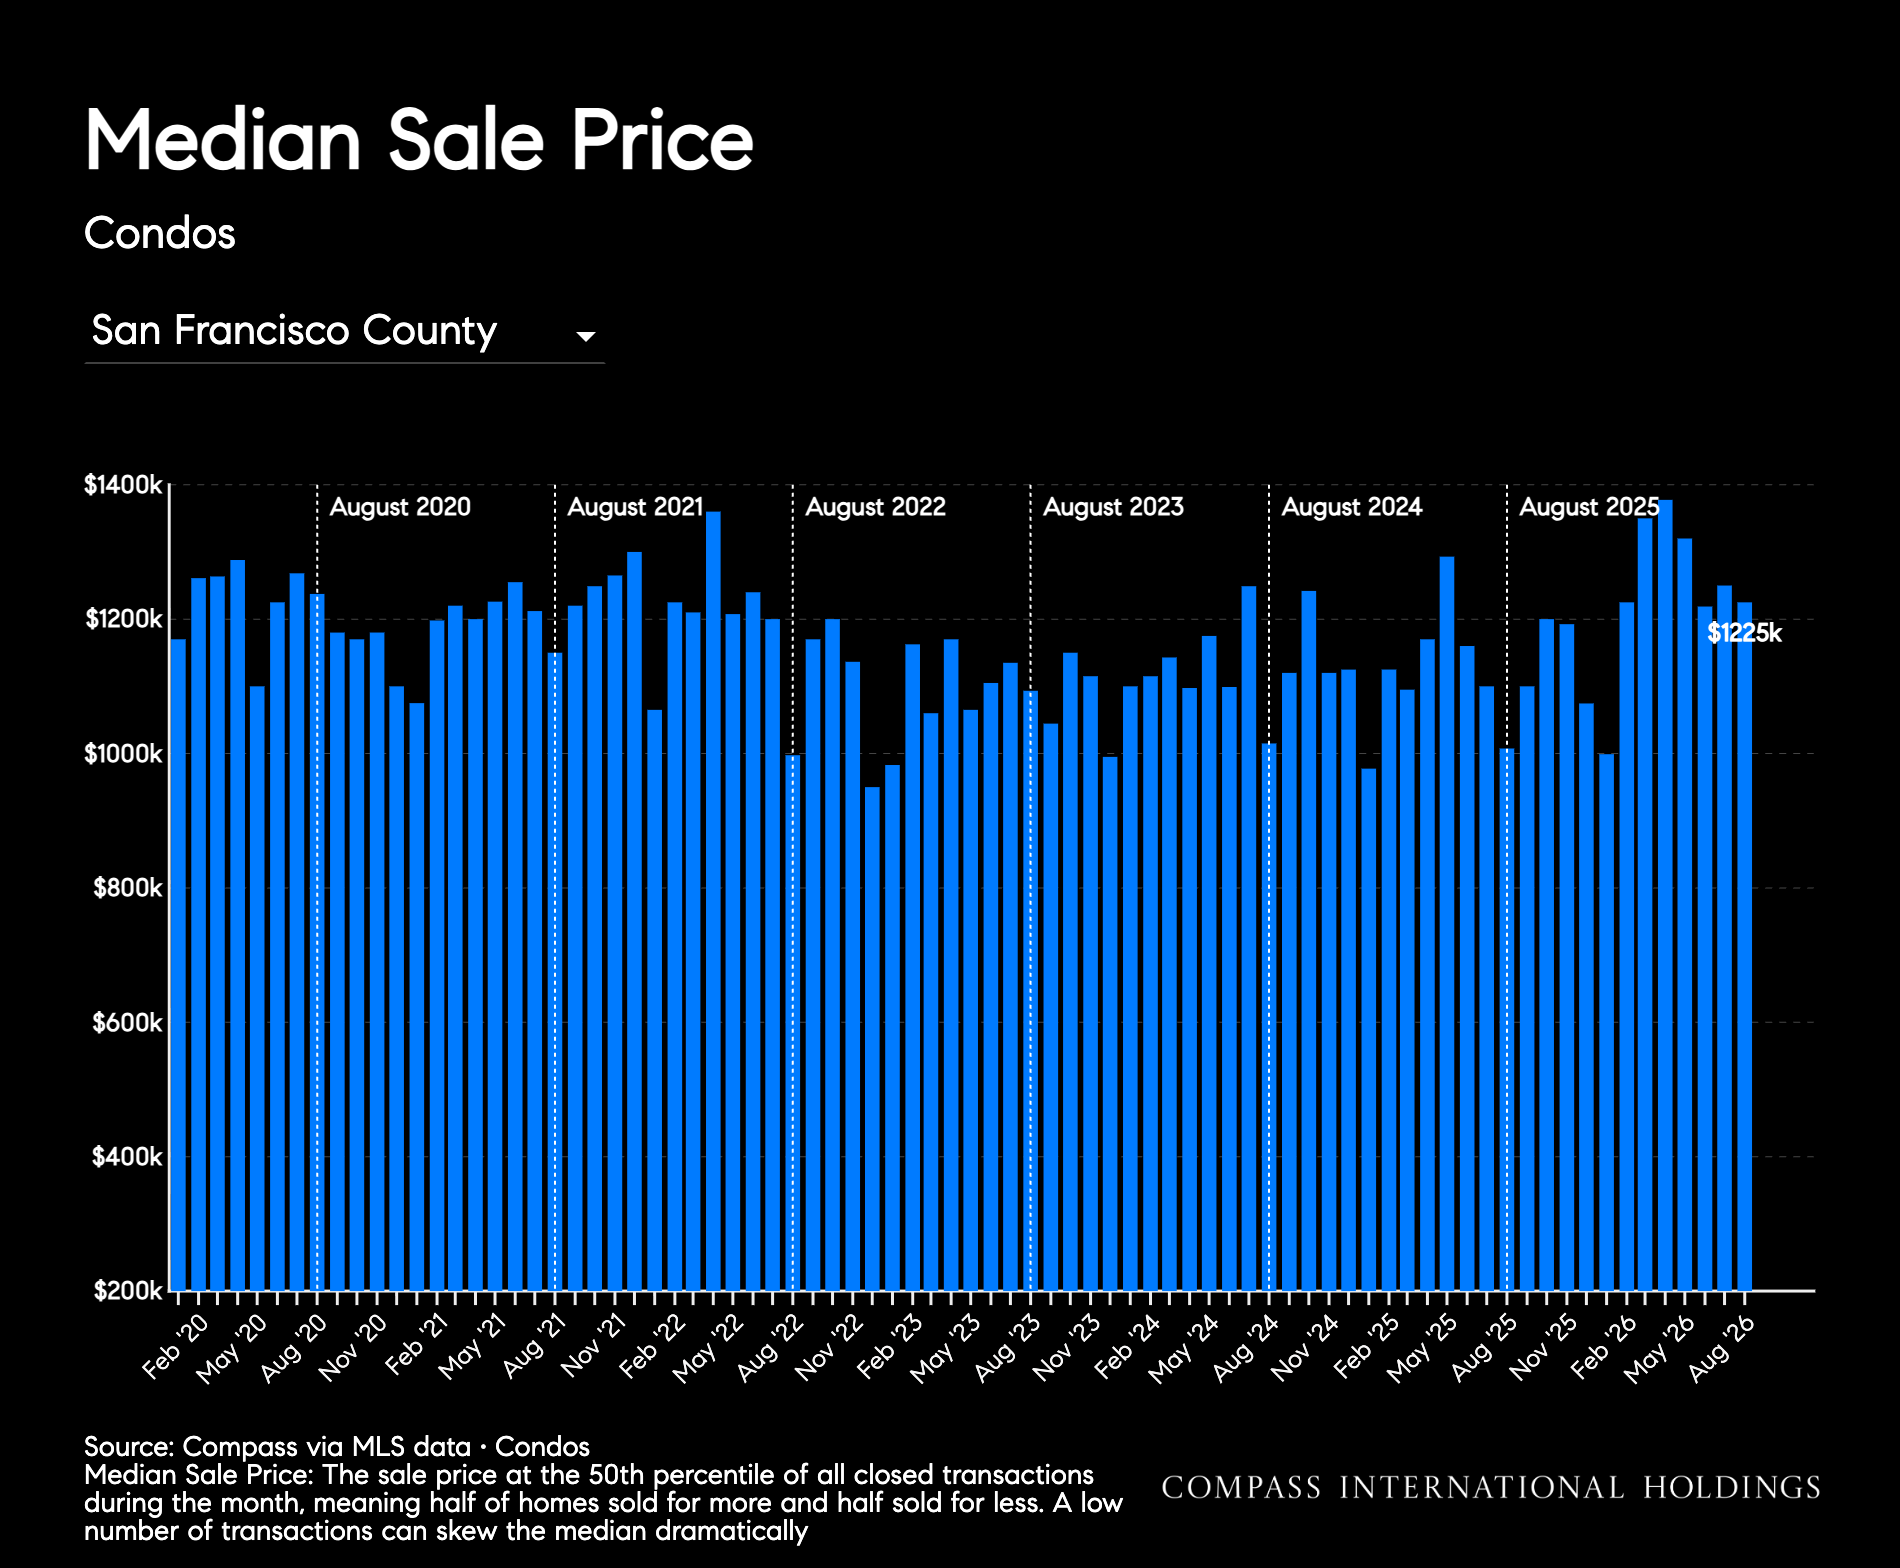
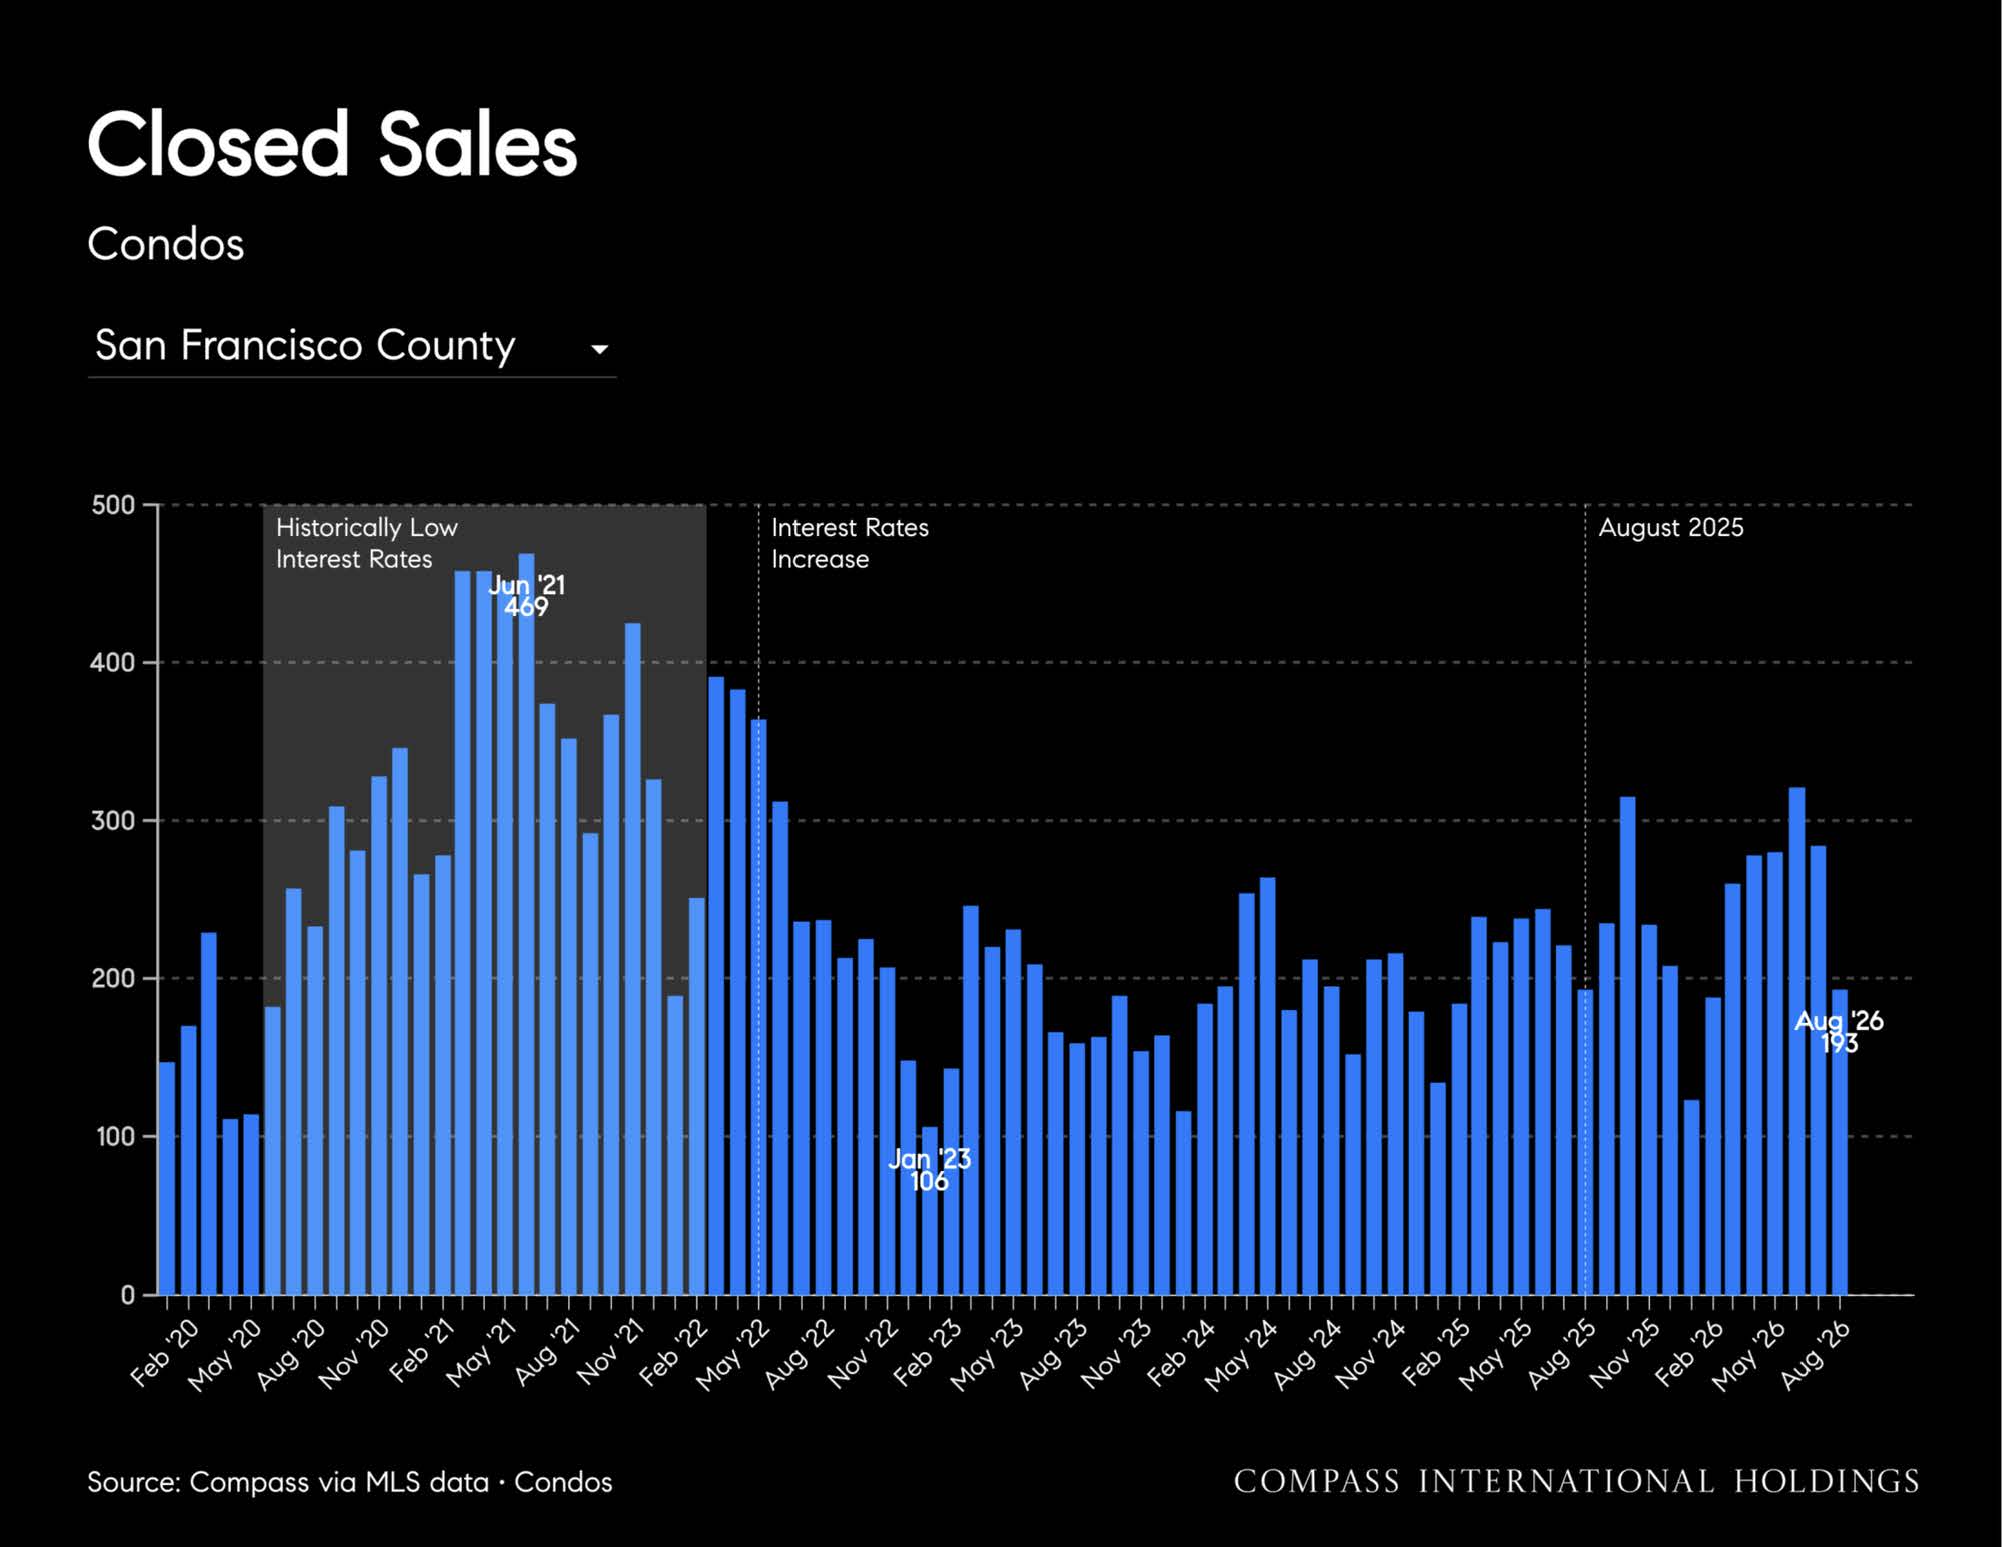
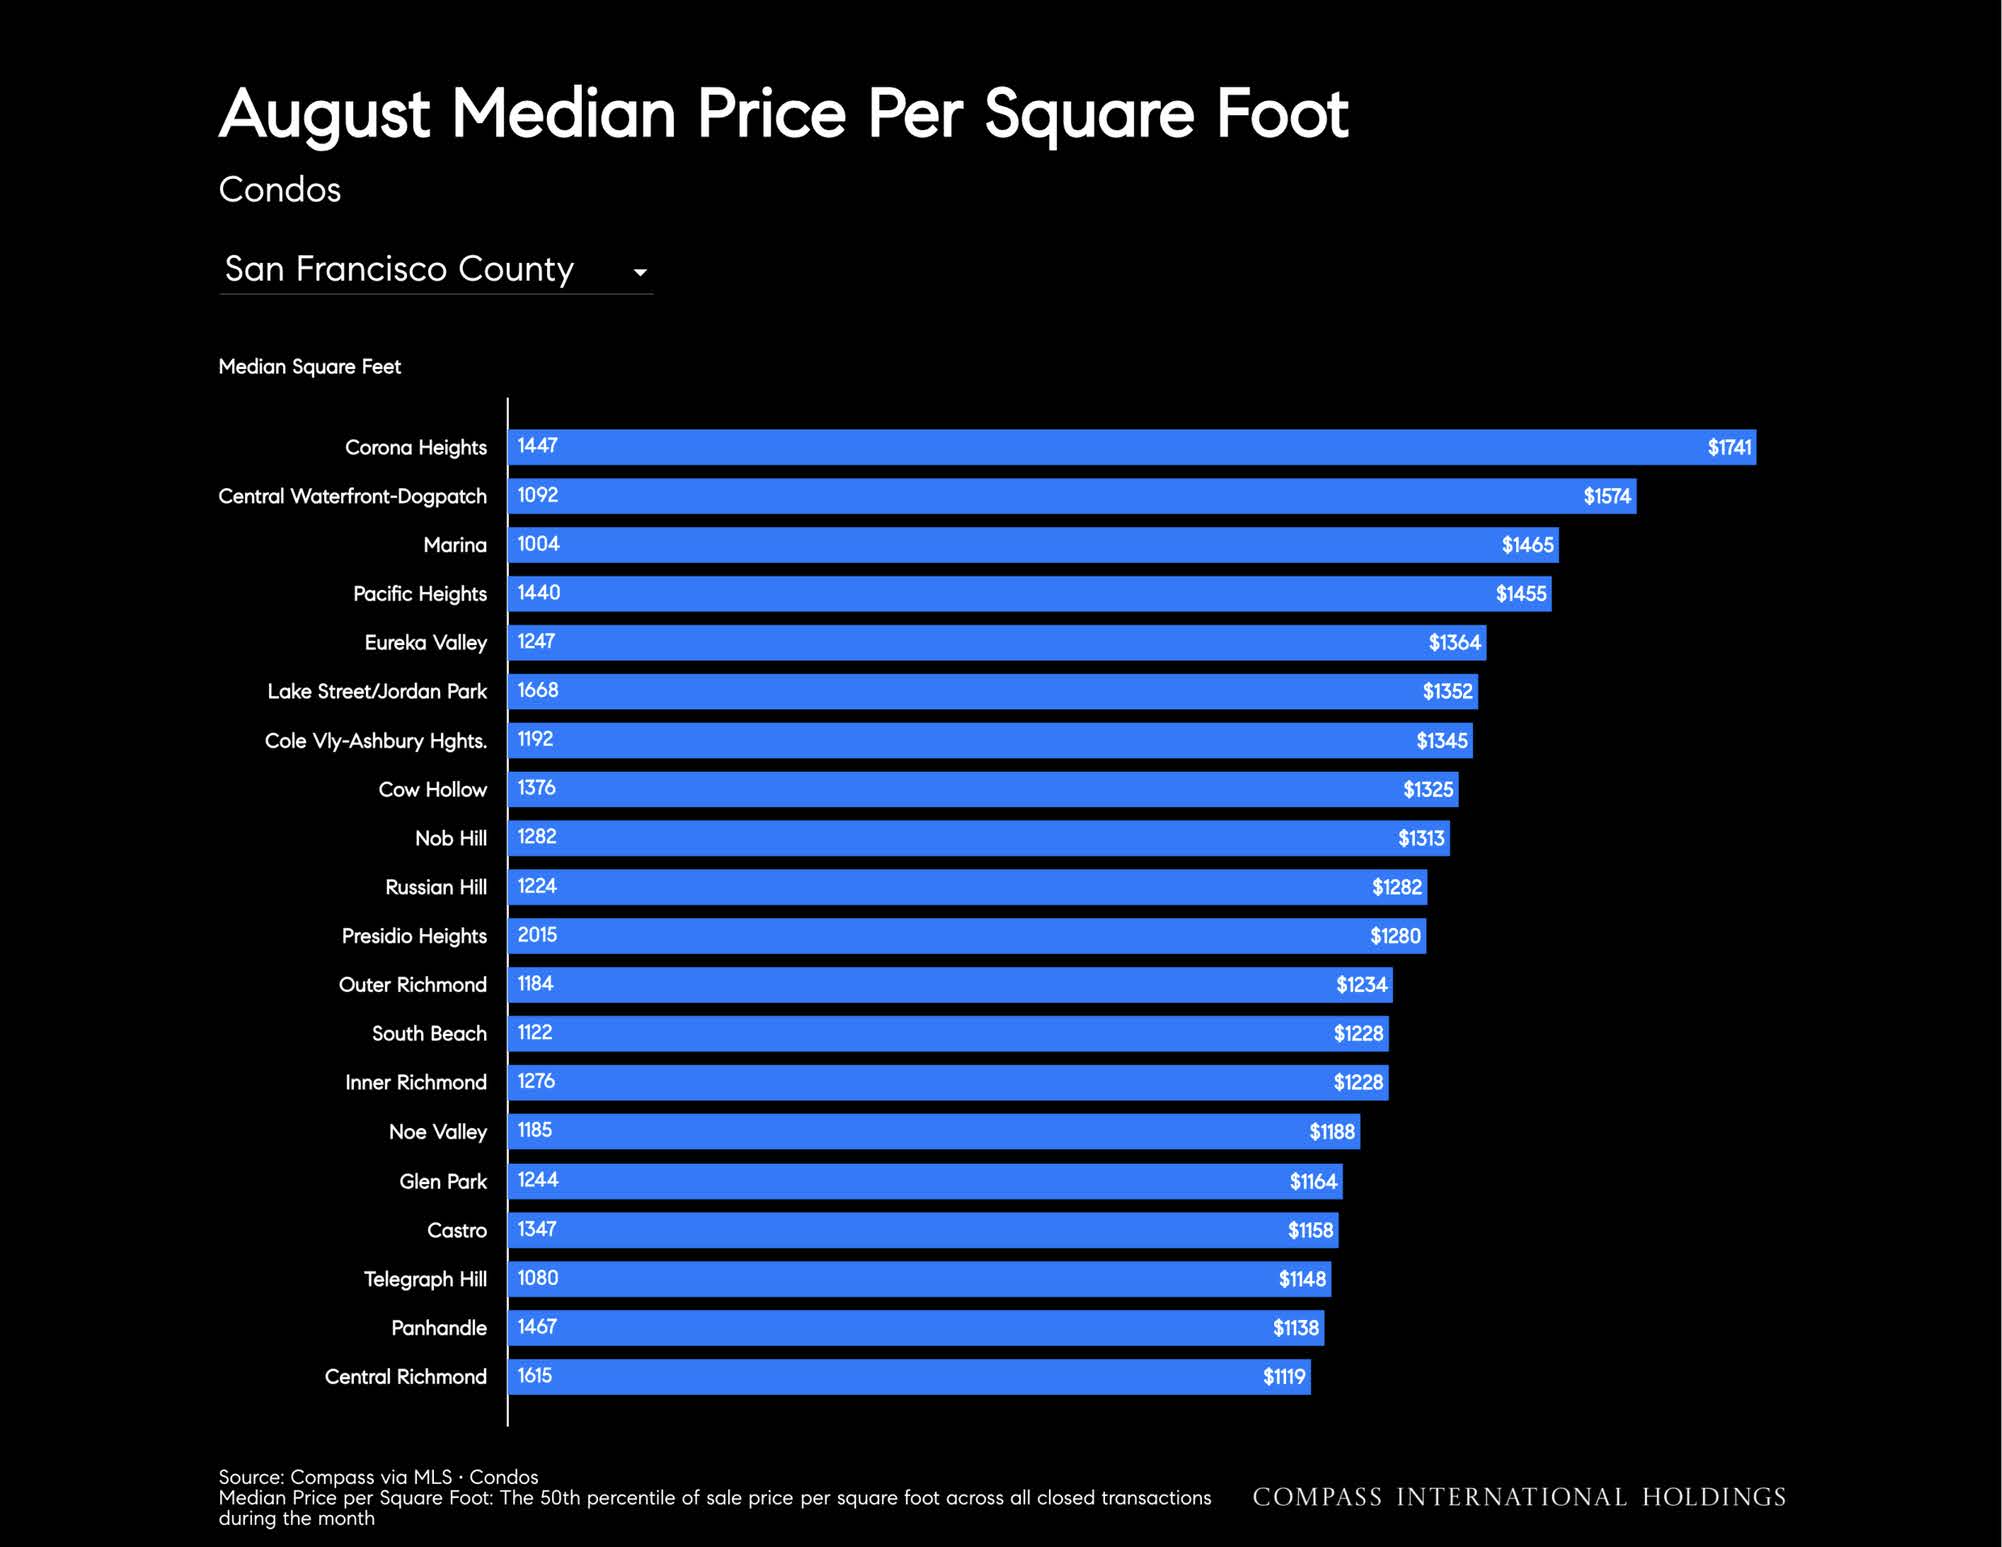
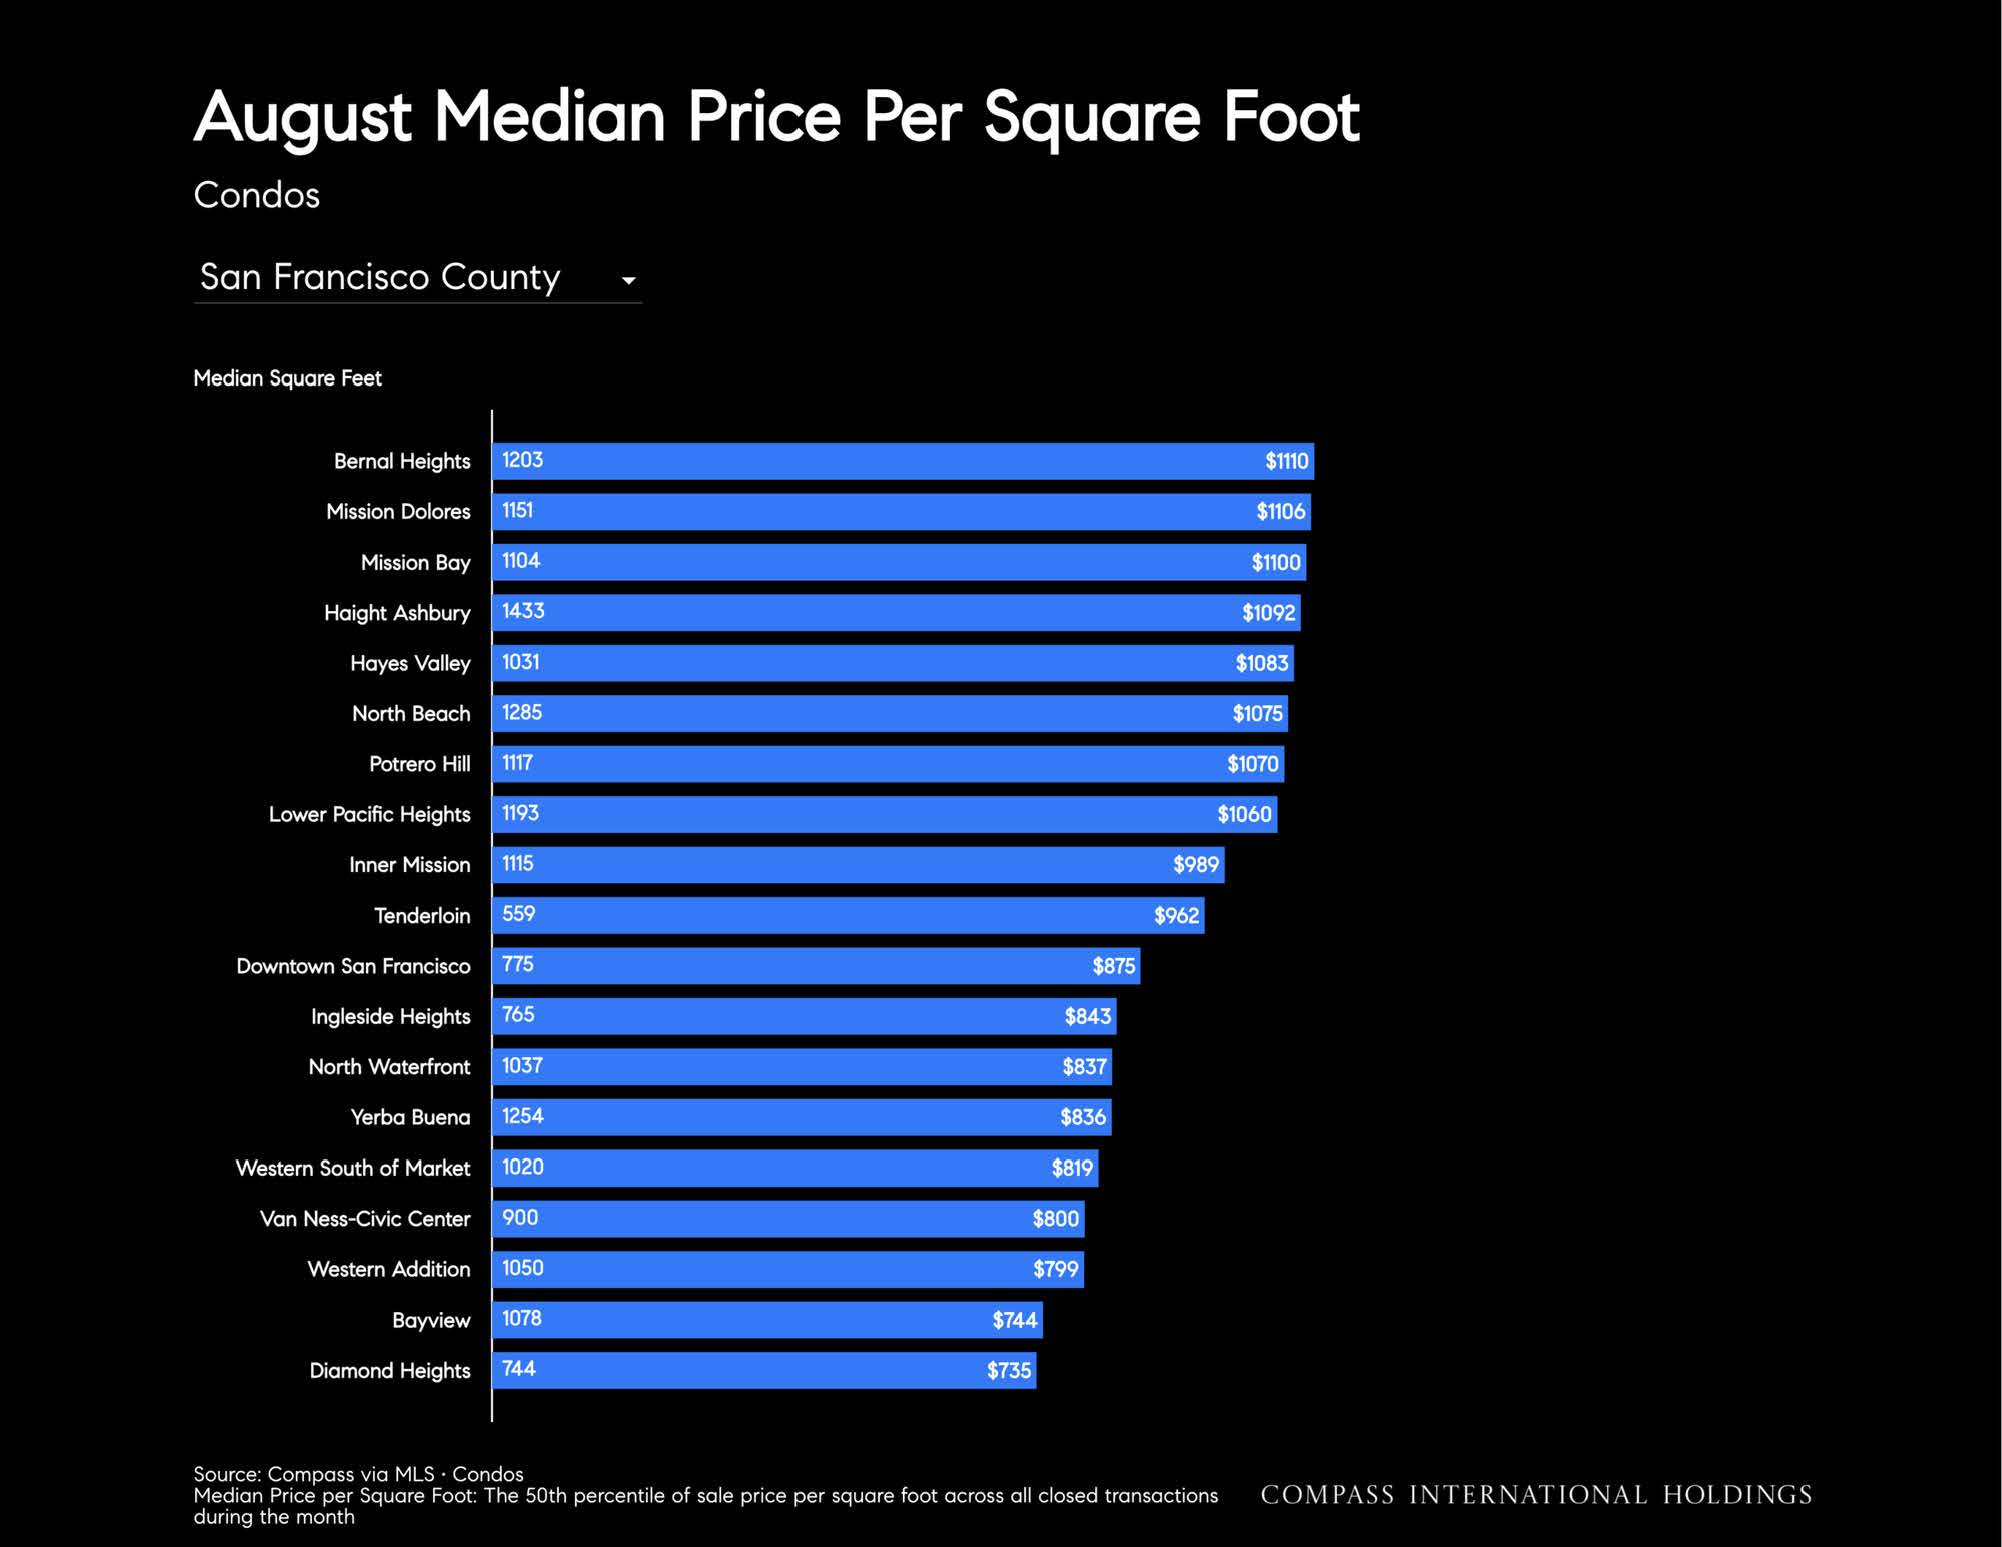
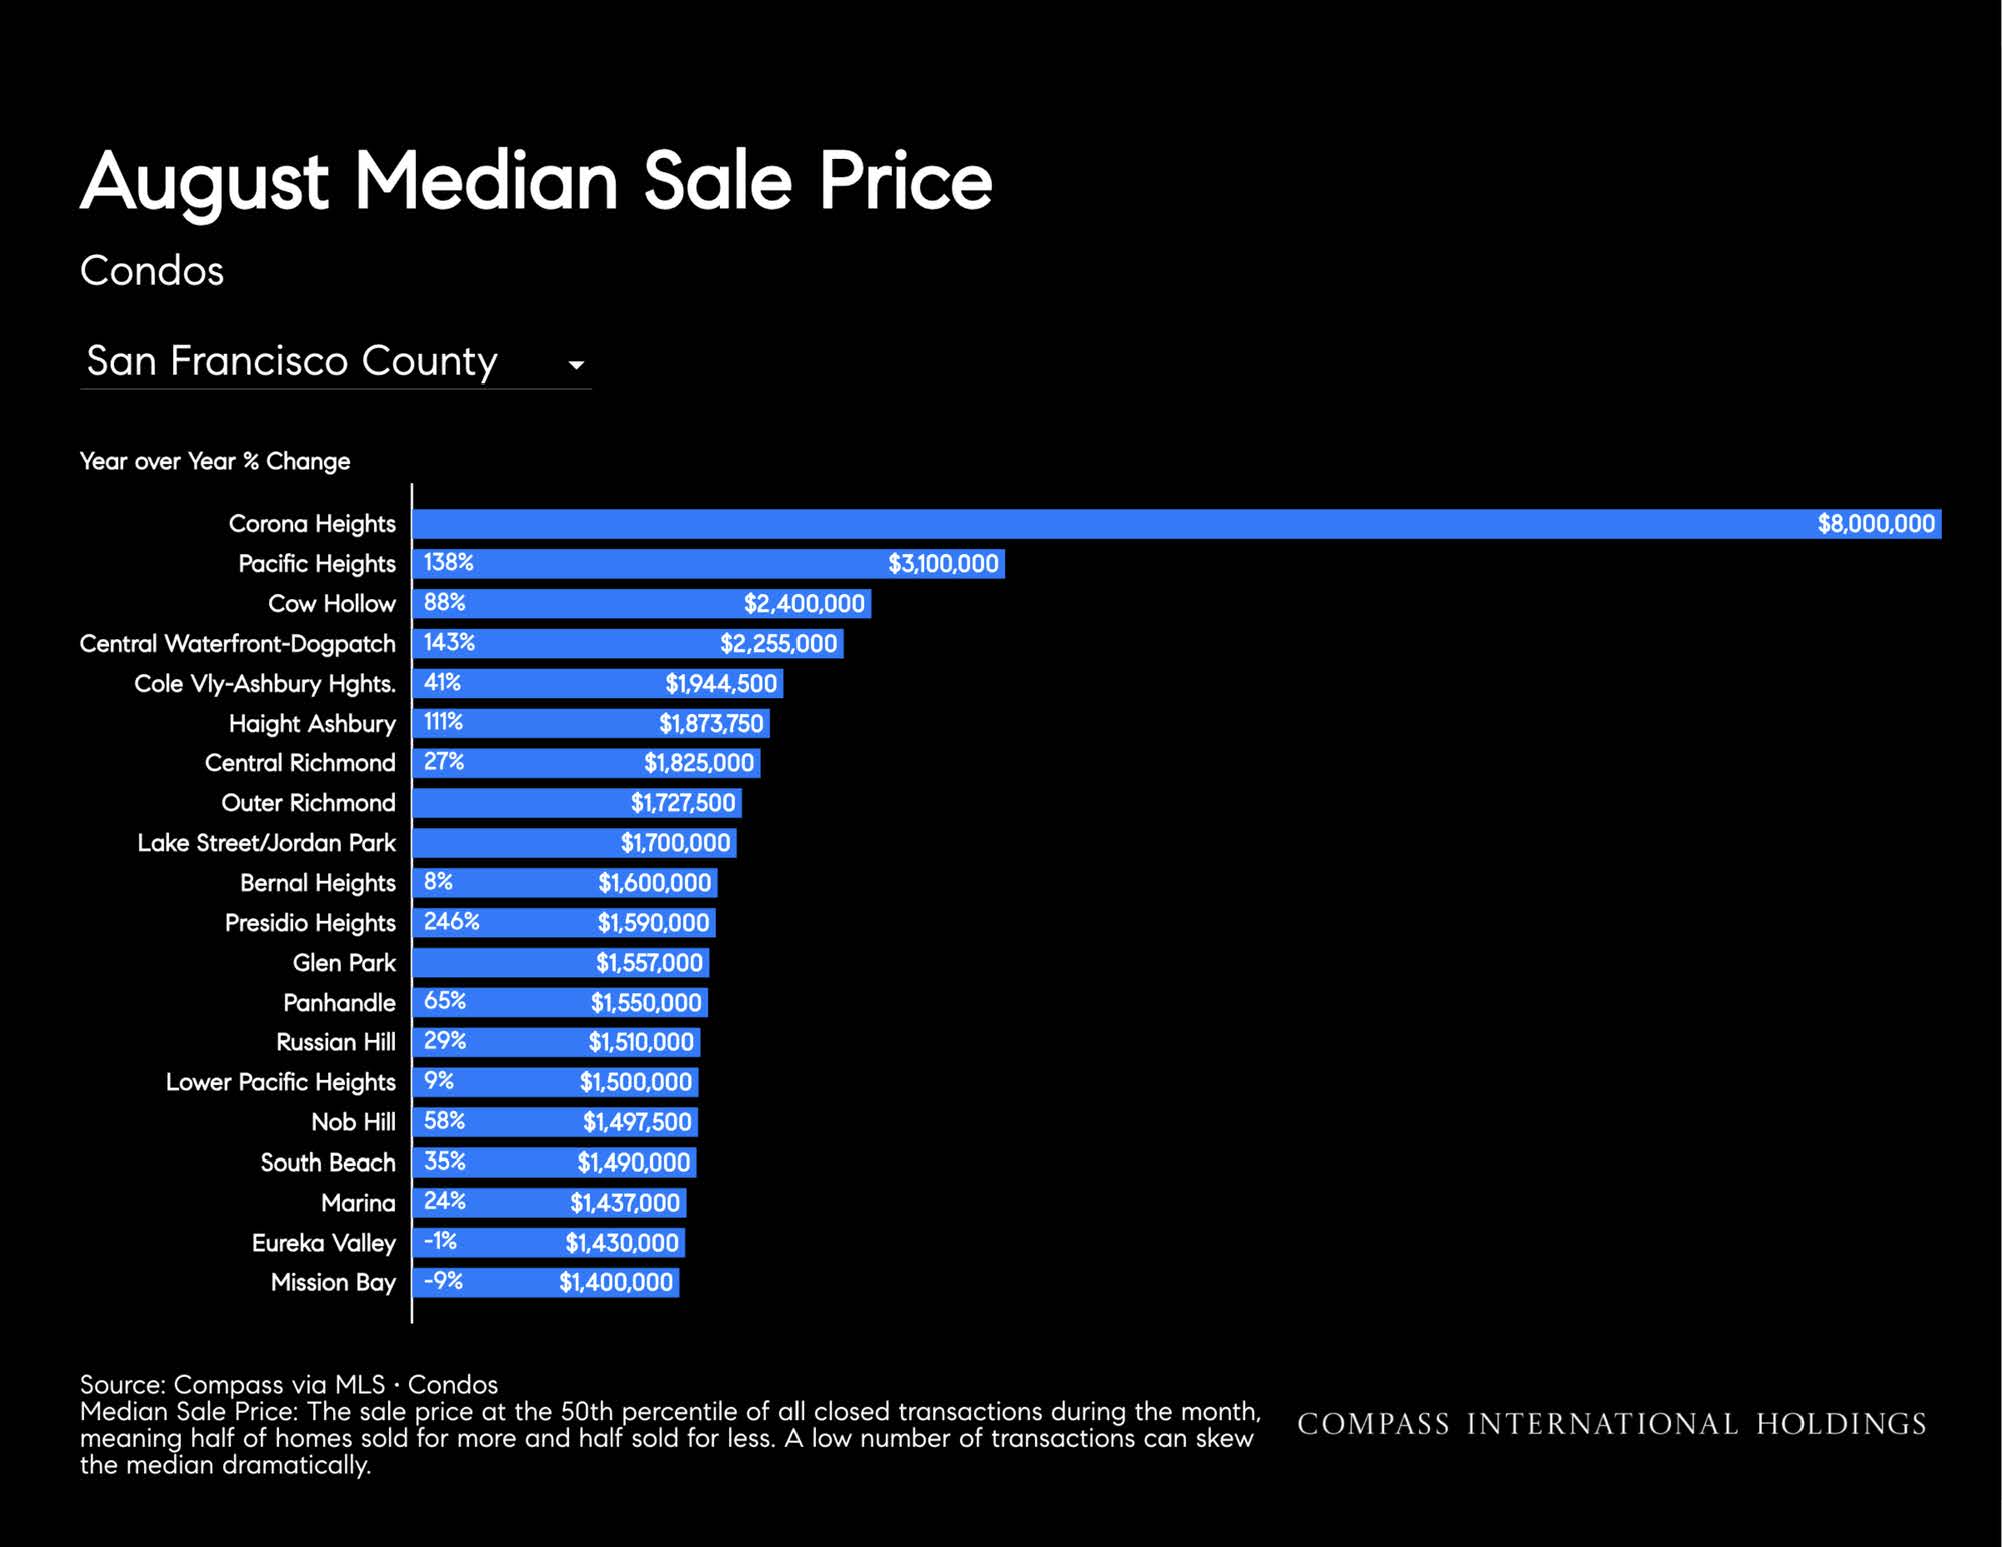
Median price: +23% to $1,257,500
Days on market: -63% to 19 days
Active listings: -33%
Sold listings: +15%
Here’s some additional color on the broader Bay Area market and how San Francisco compares:
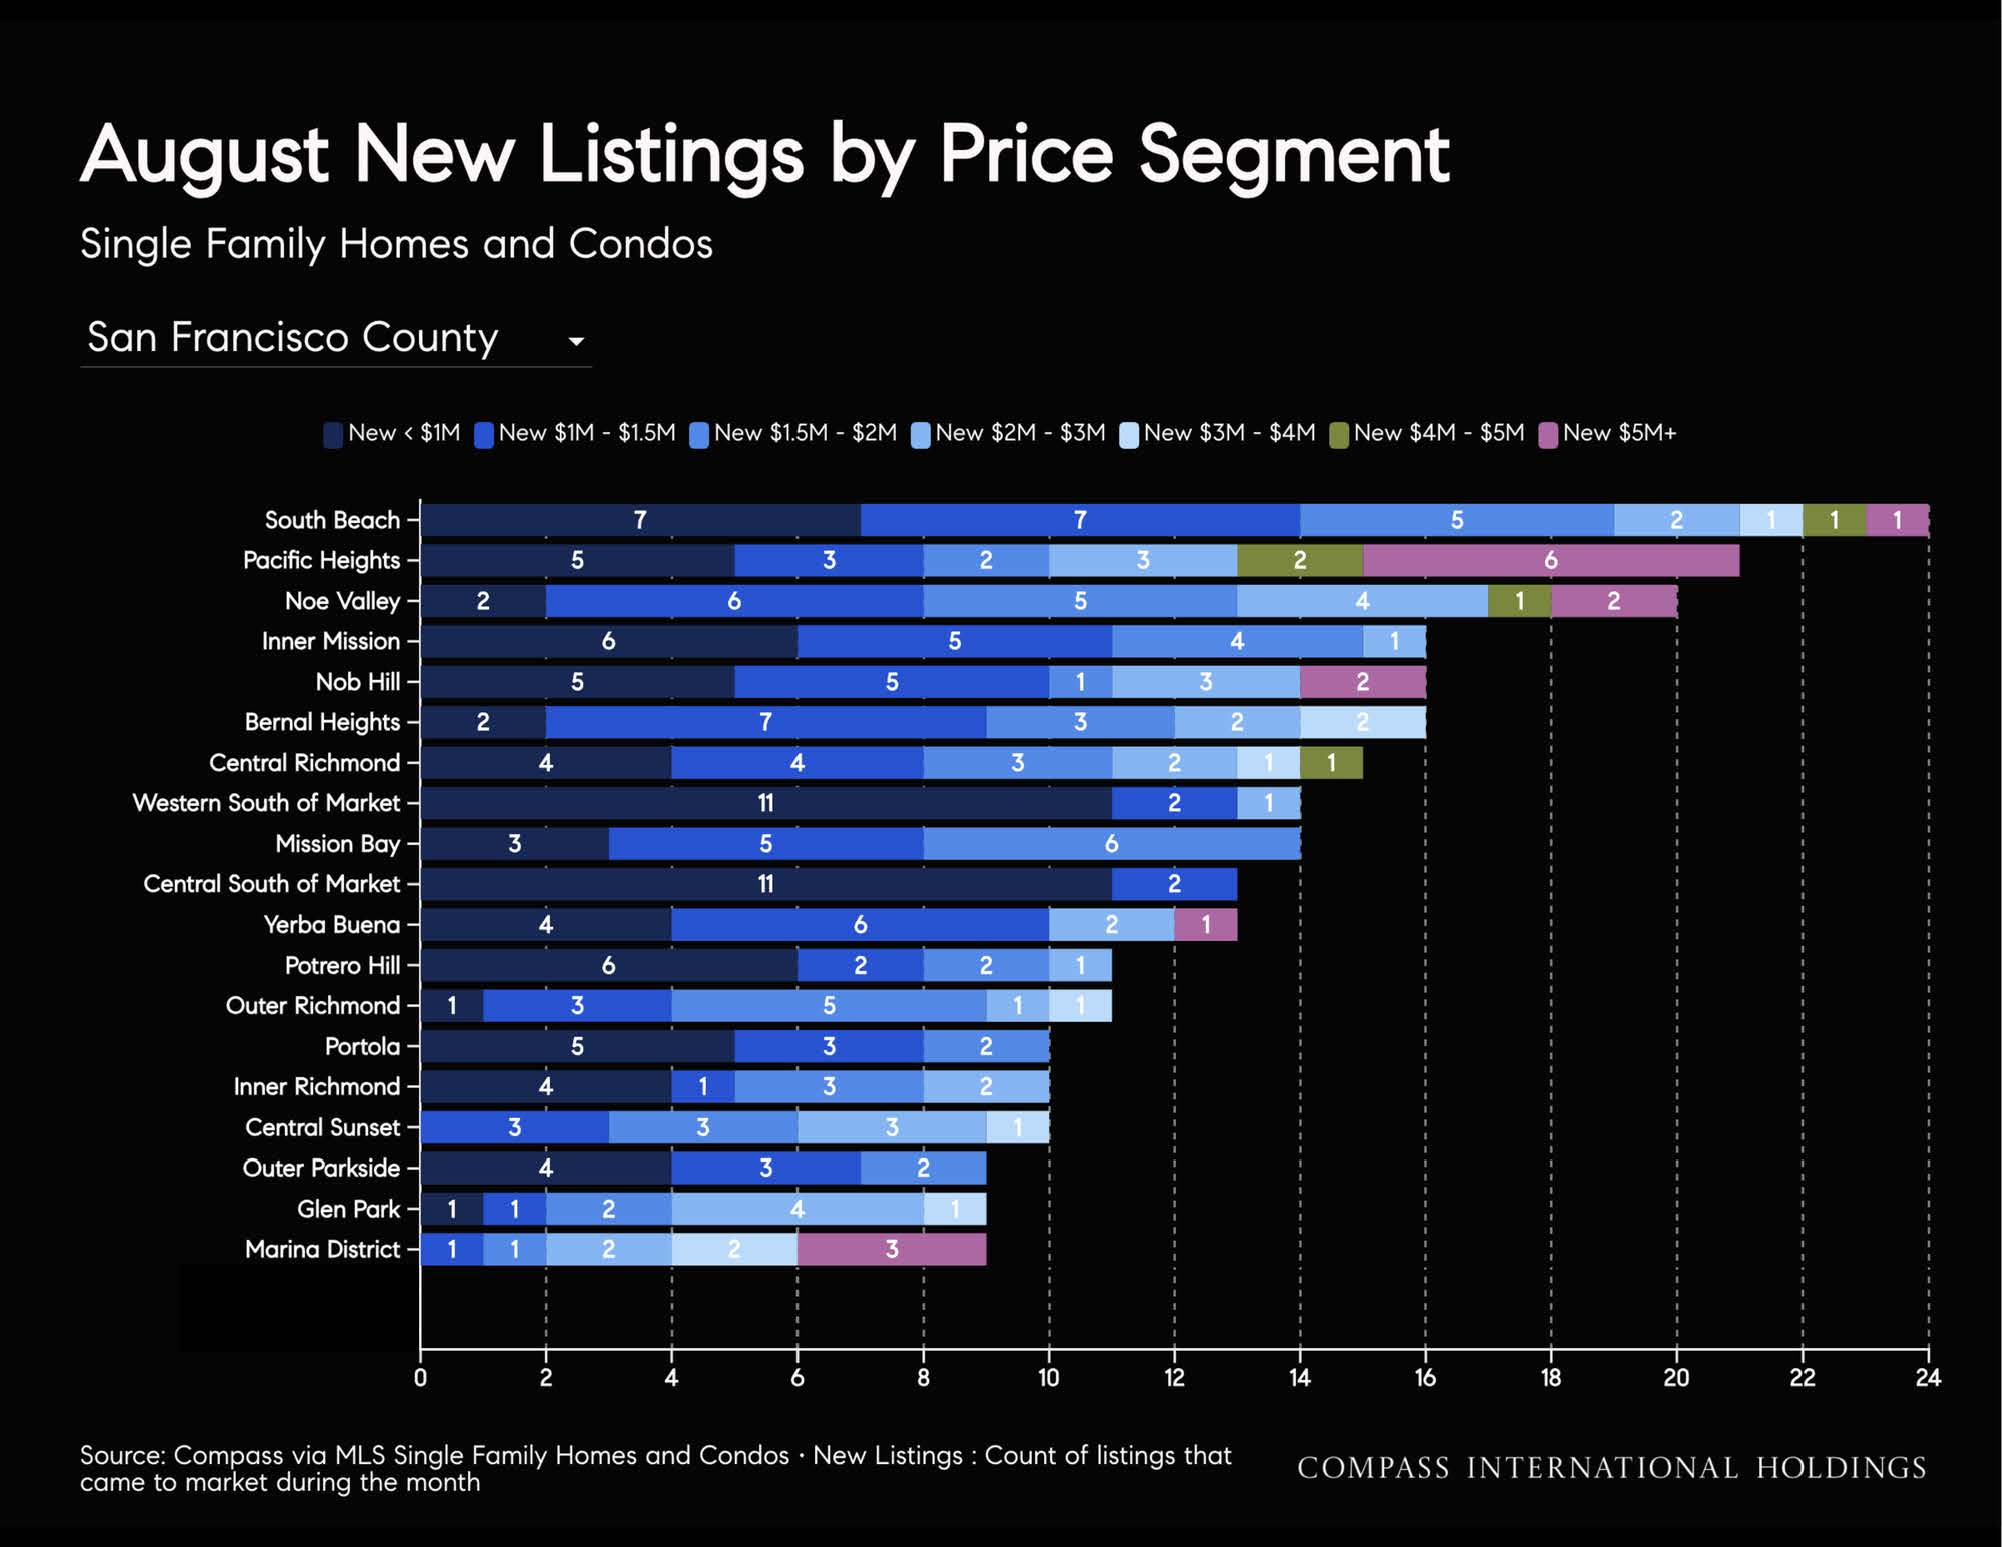
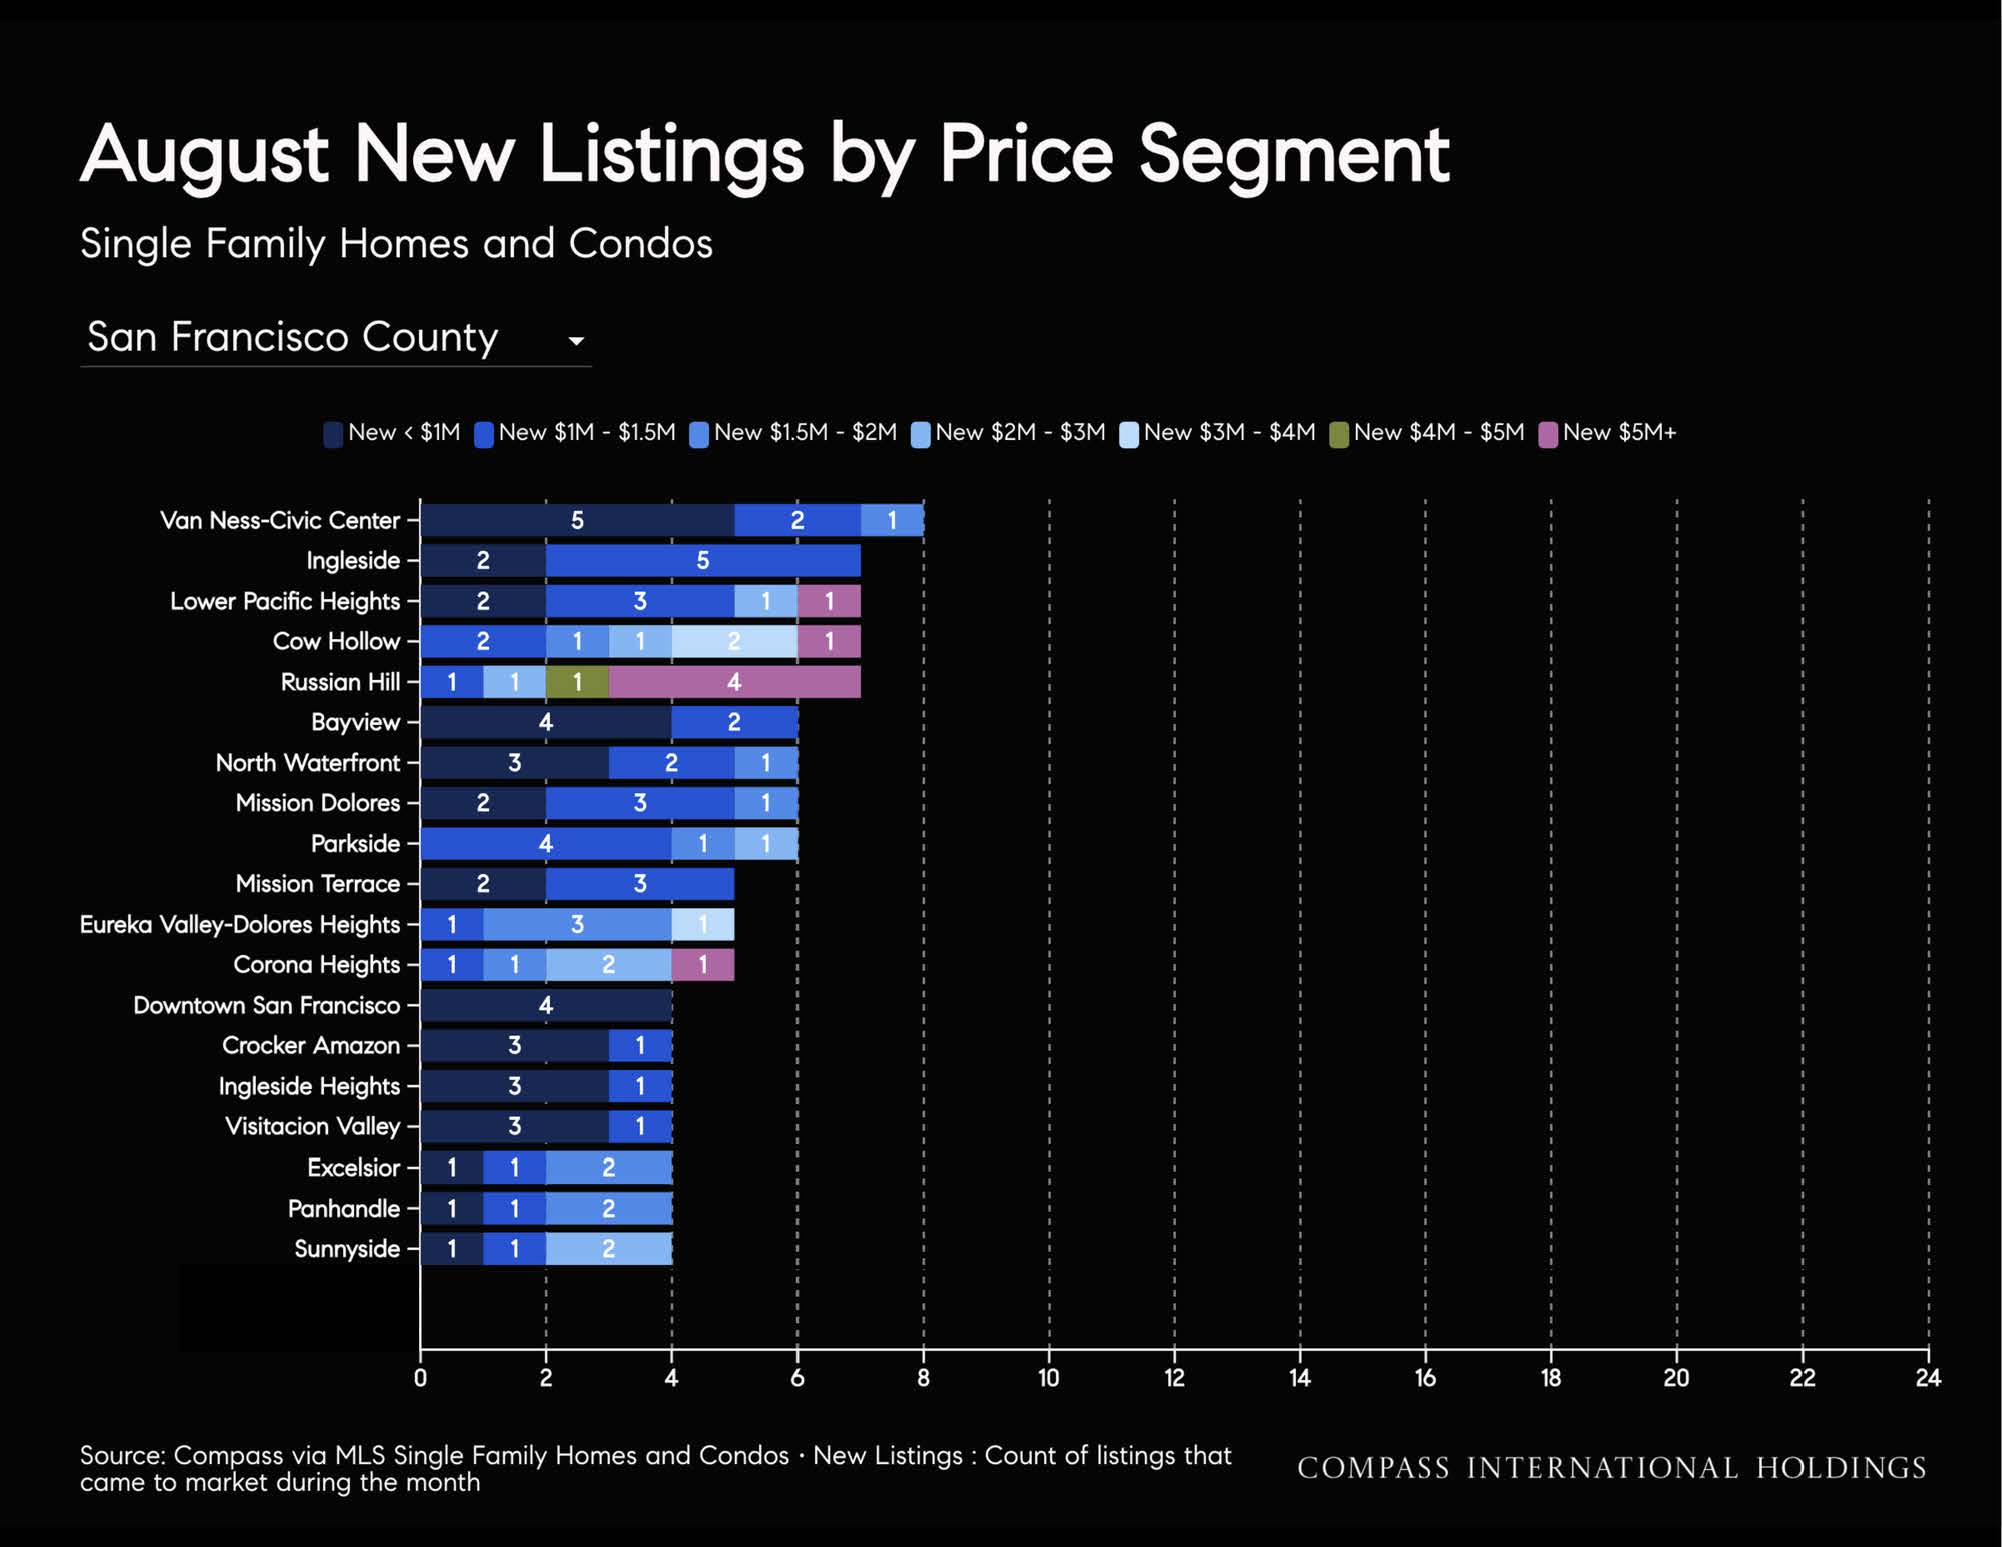
August marked a broad seasonal cooling across the Bay Area. Closings declined year over year in 13 of 14 counties and month over month in 12, while months of supply increased from July in 13 counties. That shift is consistent with the typical late-summer slowdown as the market transitions from the spring and summer peak toward the fall market.
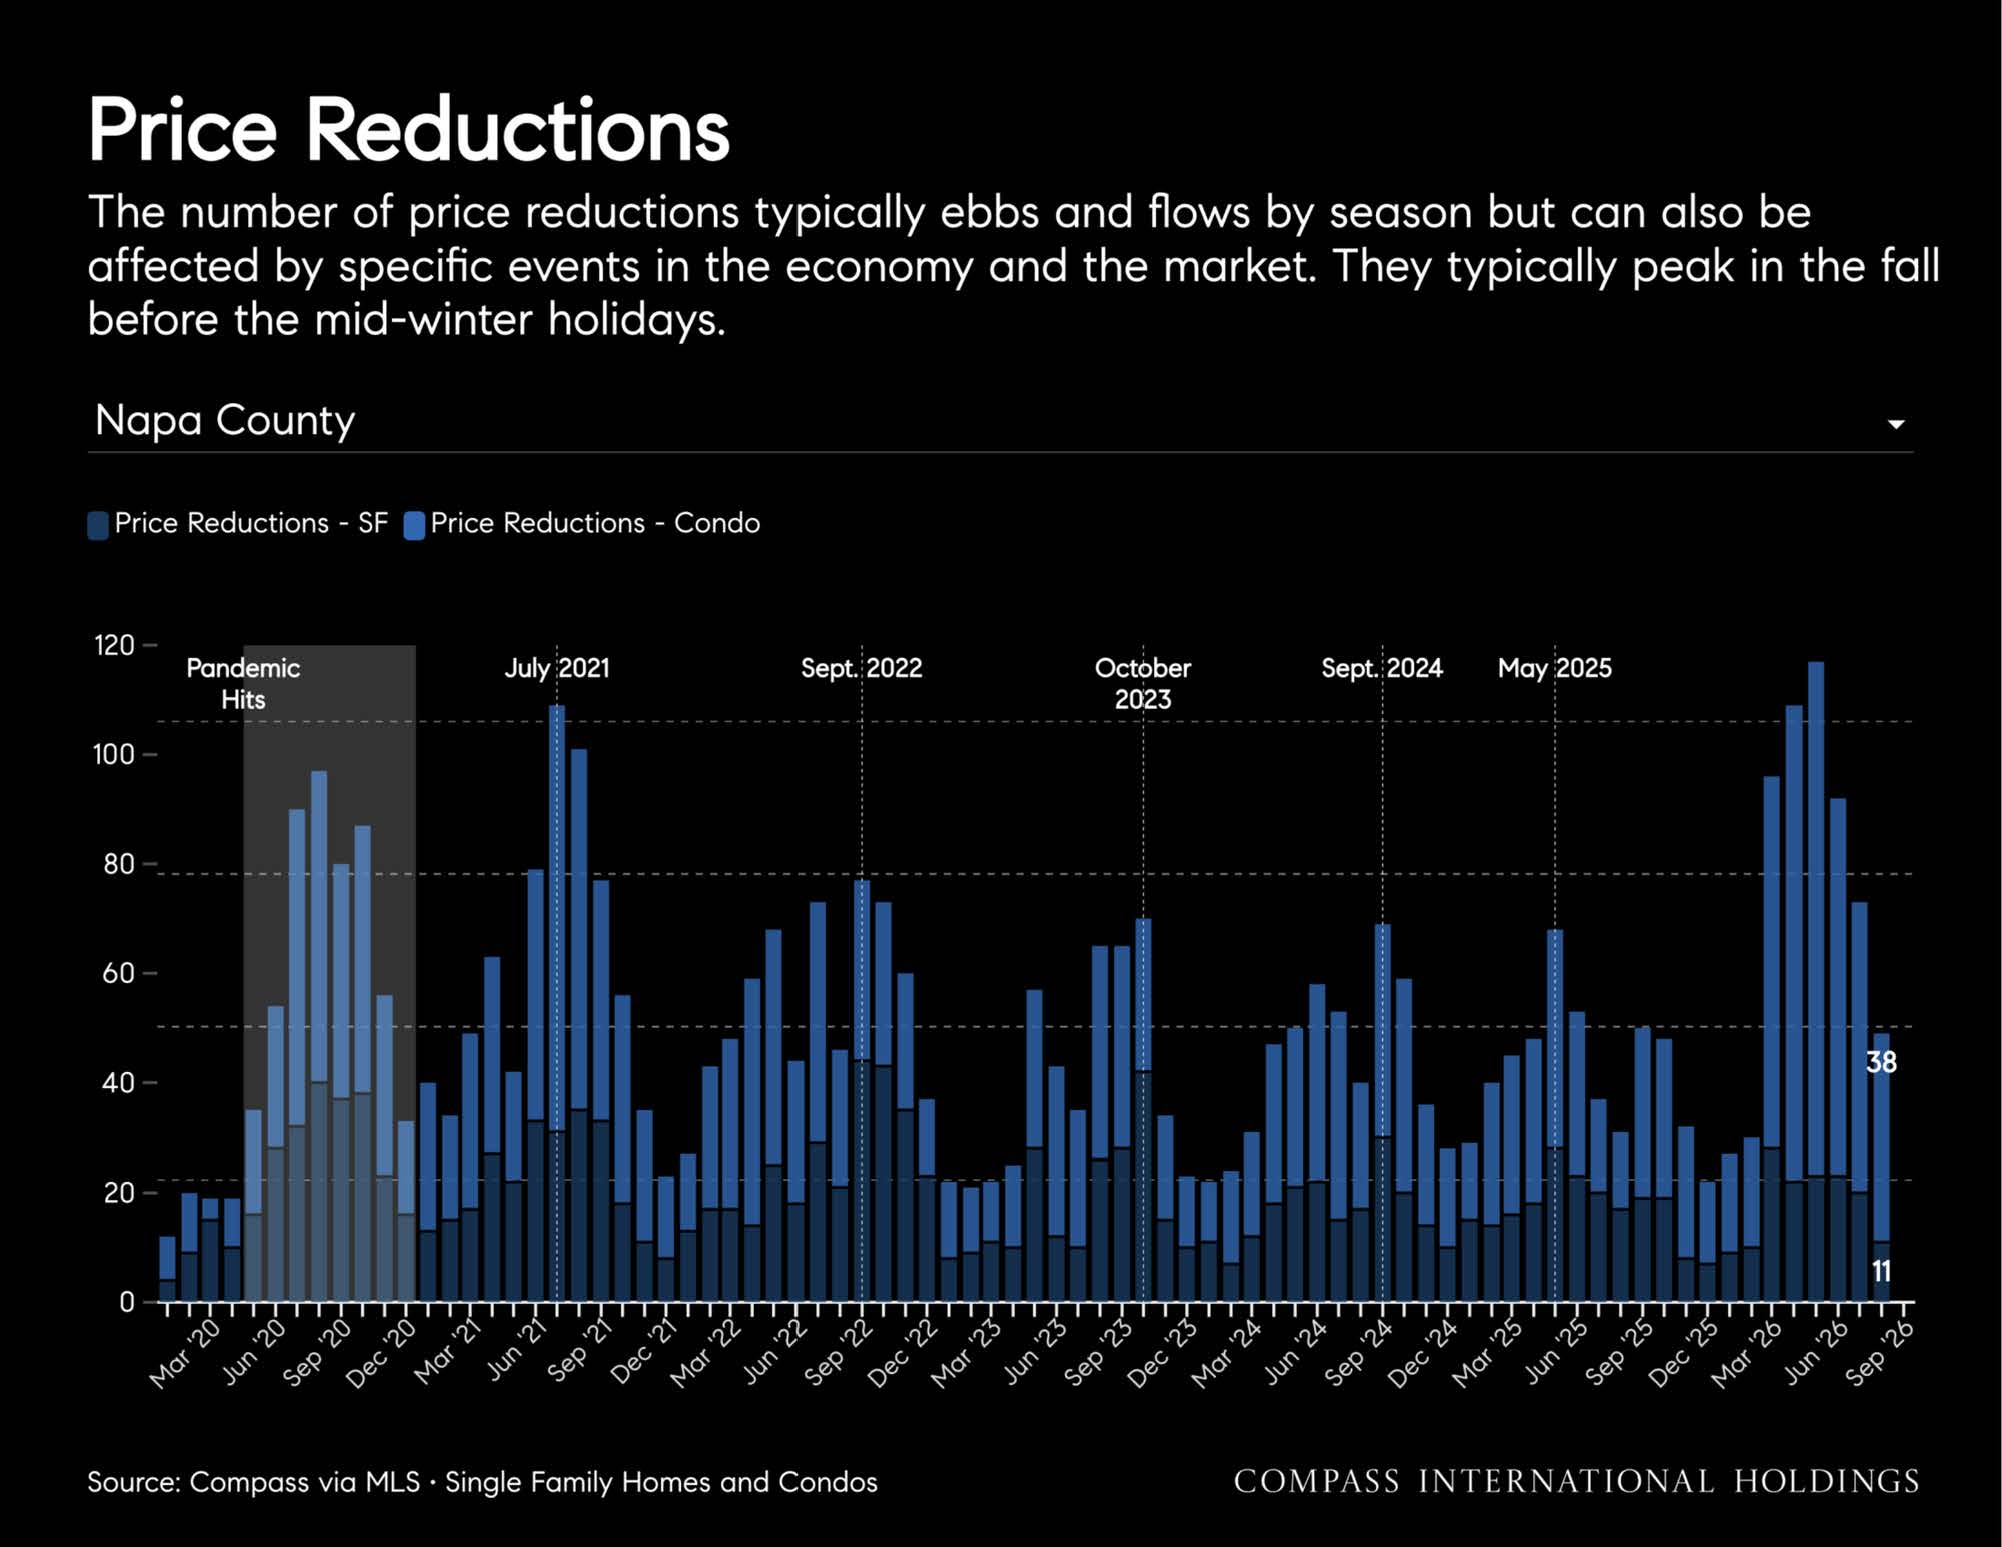
Competition, however, remained stronger than a year ago. The share of sales closing above list increased year over year in all 14 counties, while average days on market improved in 11. Price reductions increased in 10 counties, which is also consistent with the seasonal rise in listing adjustments as the market moves toward fall and winter.
Single-family homes continued to show stronger conditions than condos. Single-family closings fell year over year in nine counties but increased in five, and days on market declined in 13. The share of house sales closing above list increased across every county.
The condo market was more mixed. Condo price reductions increased in 12 counties, while condo days on market rose in six, suggesting a more uneven recovery after a strong summer.
Condo momentum also appears to be moderating somewhat. The condo median increased year over year in six counties and declined in eight, while the share of condos selling above list rose in only eight. August represents the first month of data following the new condo lending regulations, so it is still too early to know whether the slowdown reflects those changes or simply the normal late-summer seasonal pattern.
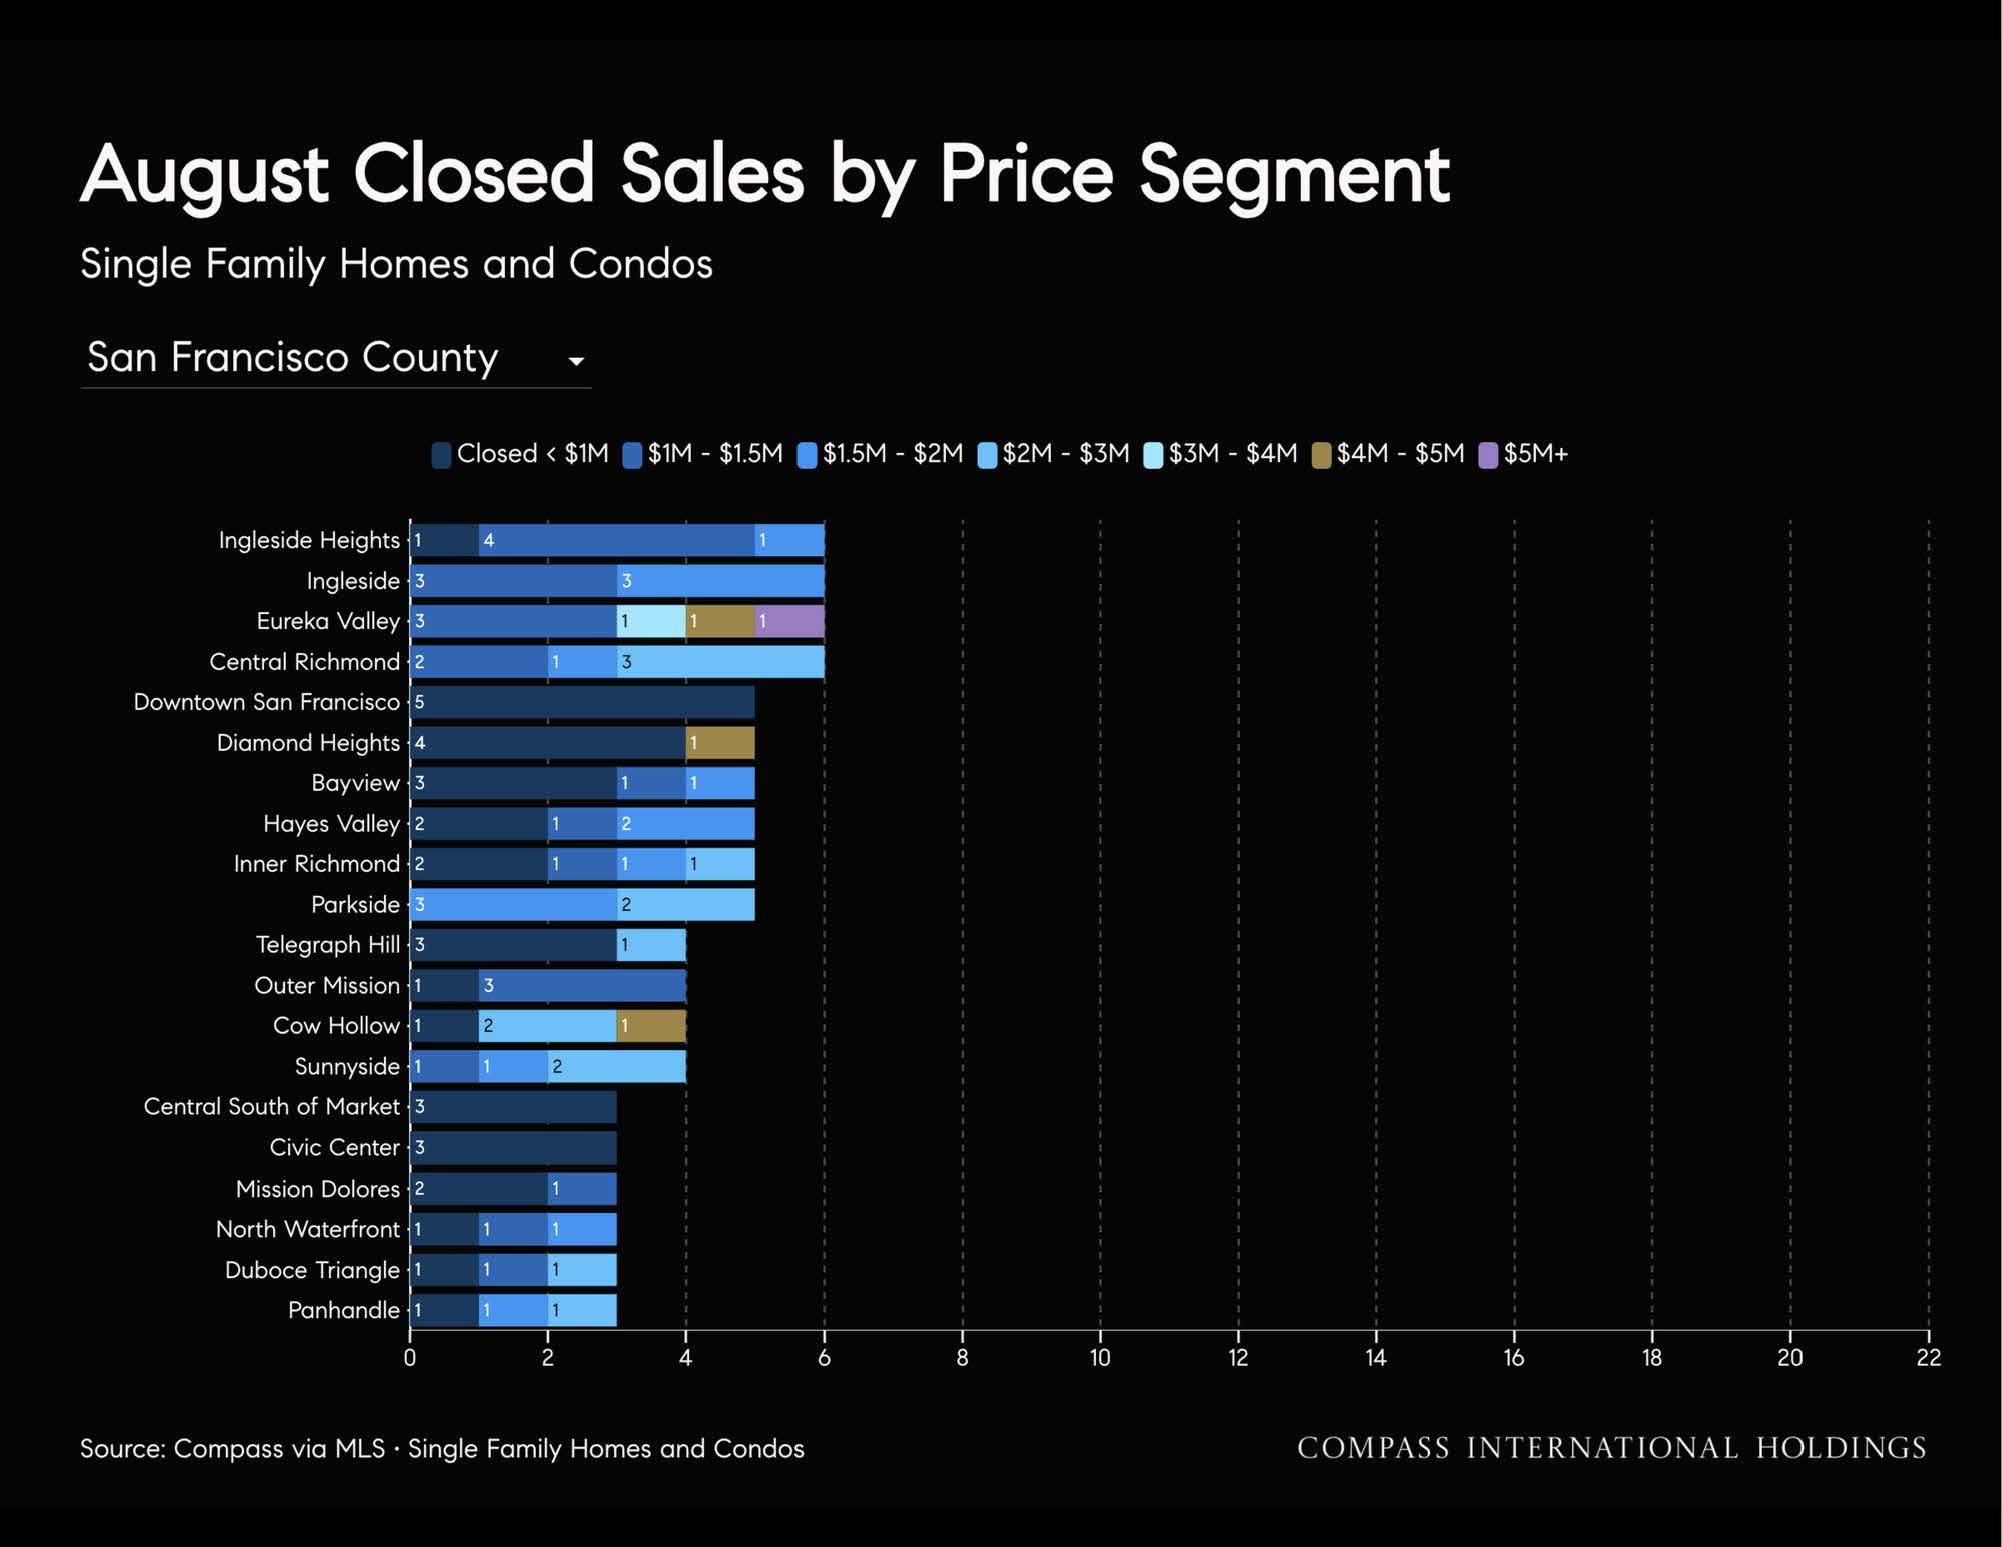
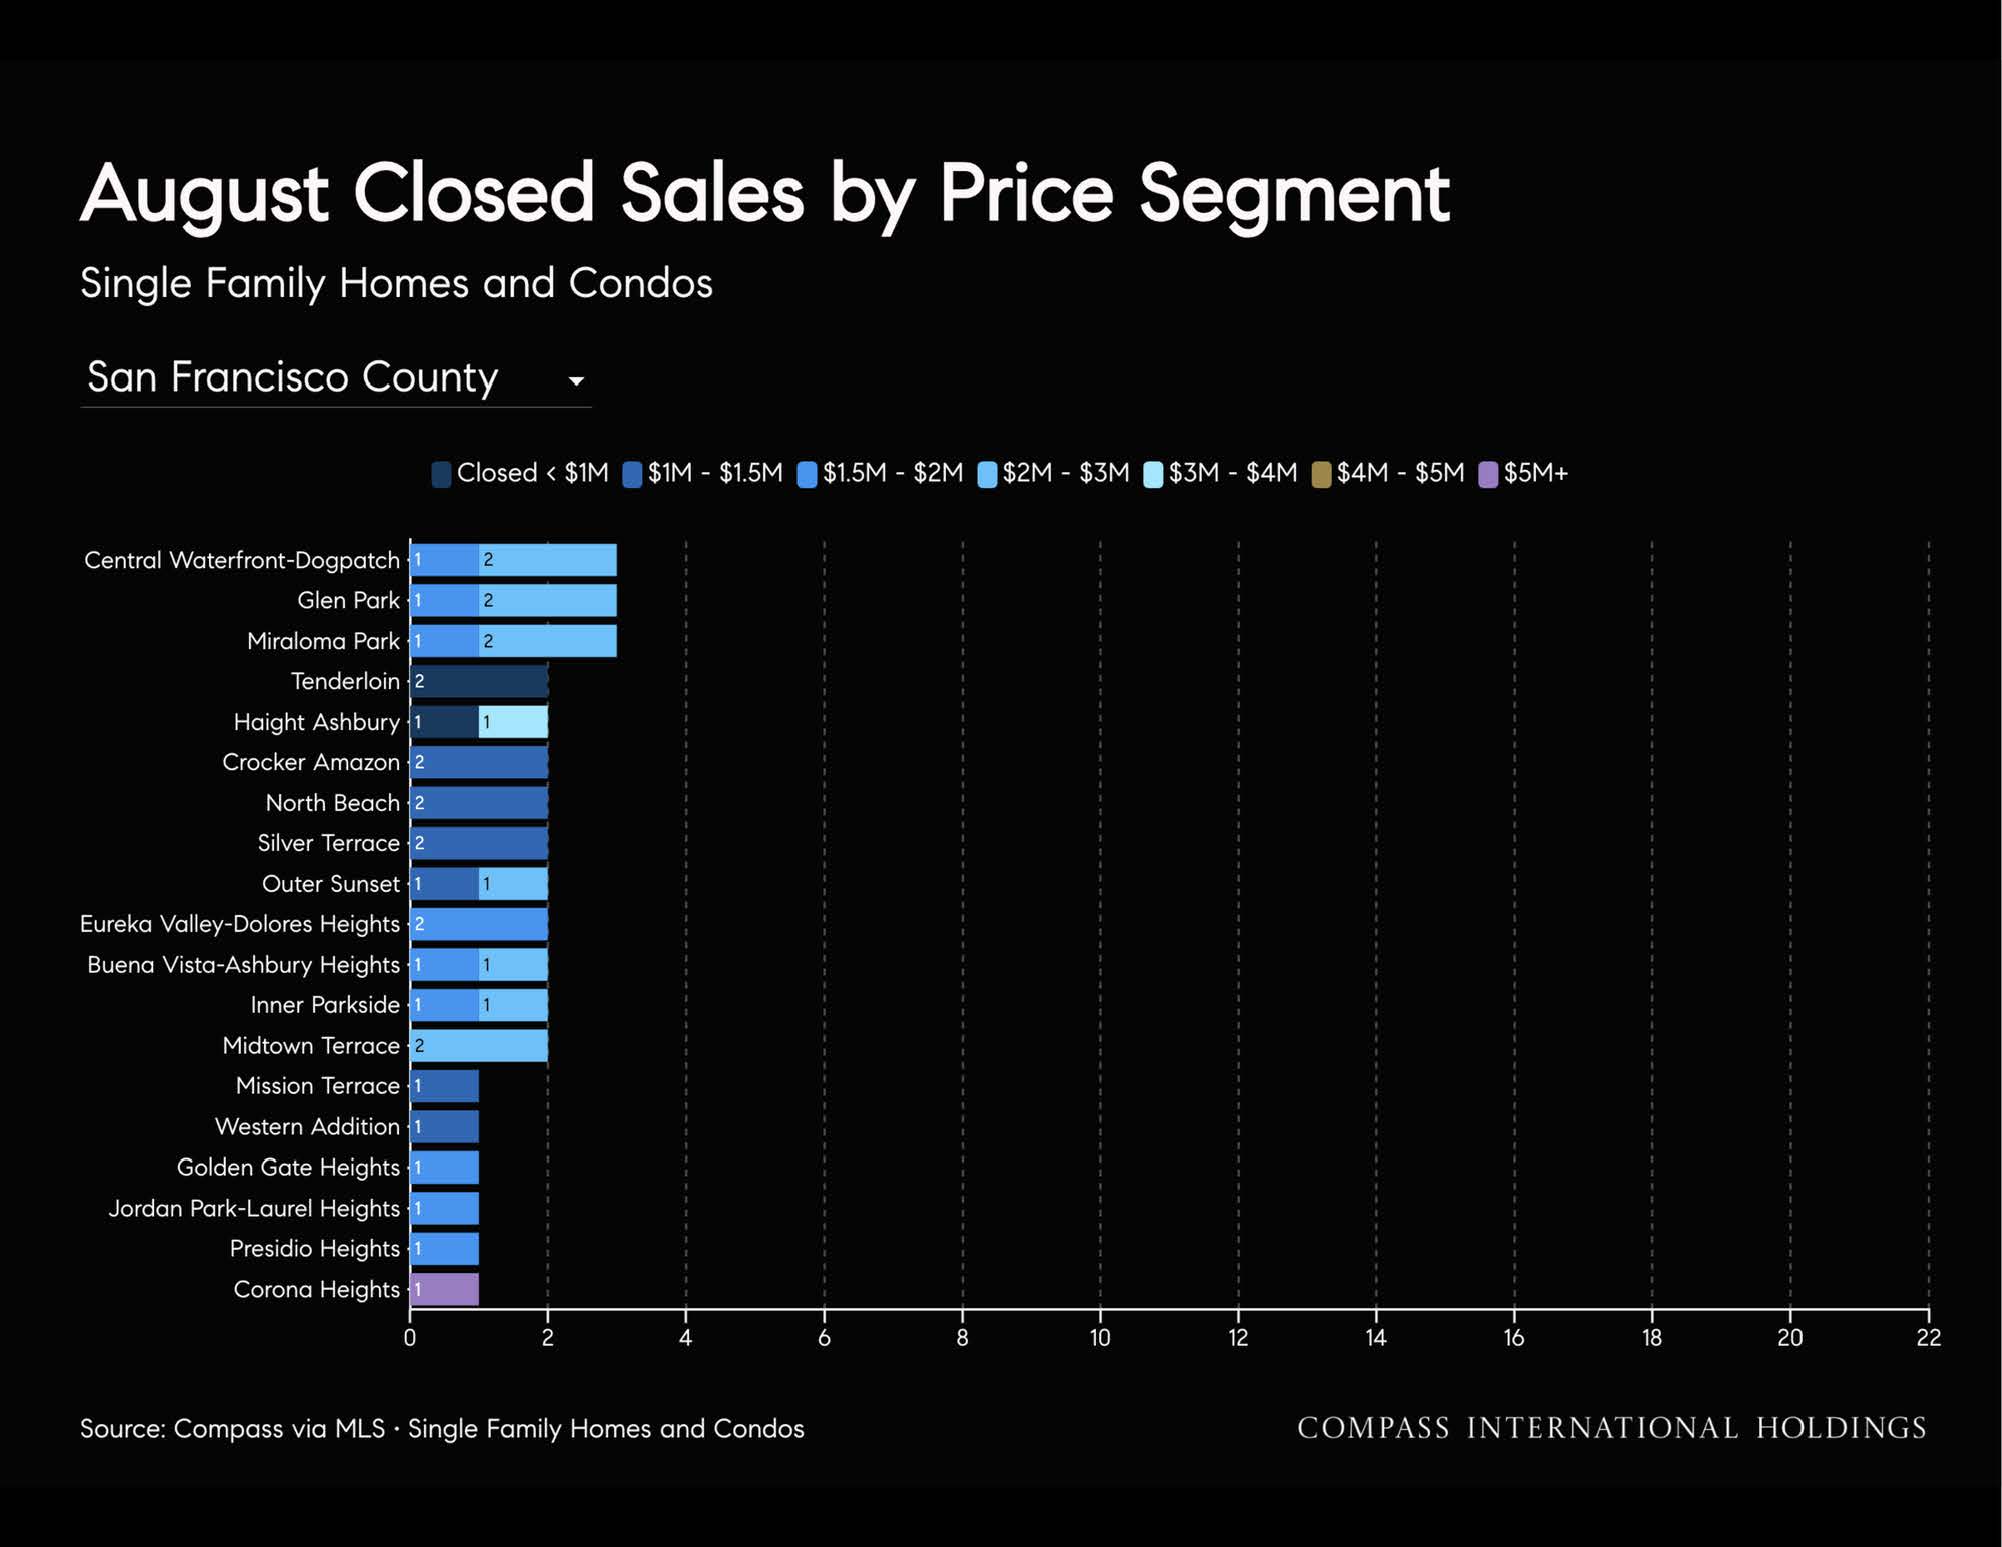
San Francisco remains the regional standout. Condo sales increased 11% year over year to 214, the condo median rose 22% to $1.23 million, and active condo listings fell 36%. San Francisco was the only county where condos showed both meaningful price growth and meaningful growth in closed transactions.
September watch: The strongest appreciation outside San Francisco has been concentrated north of the city, with Marin posting the region’s second-highest year-over-year gain. Condo sales and pricing will be worth watching closely to see whether August’s moderation is temporary or the beginning of a broader shift. The performance of smaller versus larger condo buildings will also be important as the impact of the new lending regulations becomes clearer. Atherton’s nearly $10 million increase in median price, driven by a small number of very high-value sales, will be another interesting data point to watch for sustainability.
If you have any questions about a specific property, the market, or how to navigate your current situation, I’m always here and happy to help.
Warmly,
Faye